DBS downgrades Shopee, Garena owner Sea to 'sell'
Singapore
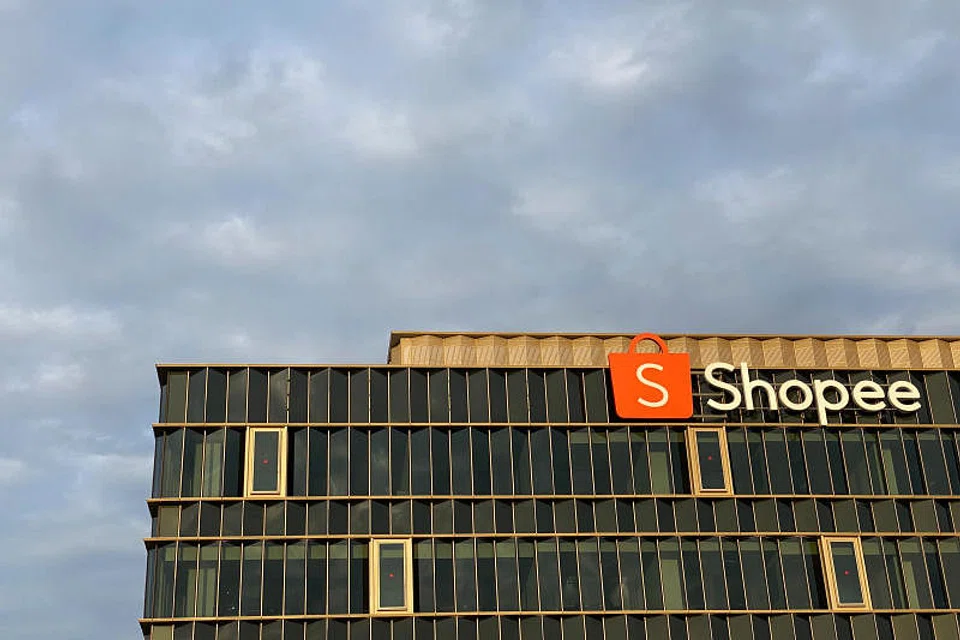
INTERNET company Sea Ltd, which owns e-commerce platform Shopee and game developer Garena, is now rated "sell" by DBS Group Research down from "fully valued", given its slower-than-expected e-commerce sales, higher losses in the e-wallet business, and rich valuations.
In a report on Thursday, DBS kept its target price unchanged at US$72.50 for the Singapore-based, New York-listed company. Sea shares had closed at US$114.46 on Wednesday, up US$7.11 or 6.6 per cent.
Analyst Sachin Mittal wrote: "We like Sea's gaming and e-commerce business, although we are less optimistic on the prospects of the hyper-competitive e-wallet business."
DBS values Shopee at US$32.70 based on enterprise value (EV) to FY21 forecast adjusted revenue of 4.5 times, Garena at US$33.90 per share with an EV to 12-month forward adjusted earnings before interest and taxes of 12 times, and SeaMoney at US$2.60 per share with an EV to FY21 forecast adjusted revenue of 15 times.
SeaMoney is the firm's digital financial services network in South-east Asia, and its offerings include e-wallet services, payment processing and micro-lending.
"While there is no denying that the wealth of data provided by gaining market share in this segment is highly valuable, SeaMoney is likely to be a money pit in the near to mid term," Mr Mittal wrote. "We expect the digital financial services segment to be a big drag, due to increasing customer acquisition cost for the e-wallet platform."
He noted that in Indonesia, e-wallet market leaders are "far ahead" compared with SeaMoney, and observers are expecting further market consolidation over the next few years.
As for e-commerce, there are further downside risks to consensus adjusted revenue estimates due to revised tax regulation on cross-border transactions, he said.
DBS's predictions for combined earnings before interest, taxes, depreciation, and amortisation (Ebitda) of e-commerce and digital financial services are 11 per cent below consensus for FY20 and 40 per cent lower than consensus for FY21. However, its forecasts for the gaming unit's adjusted Ebitda exceed consensus by 10 per cent for FY20 and by 9 per cent for FY21. Mr Mittal expects Sea's popular mobile game Free Fire, which has seen four "stellar" years, to continue to grow for another two to three quarters before stabilising in FY22, when consumers switch to newer titles.
DBS's bull-case fair value for Sea is US$90. For the stock to be at this level, the gaming arm's adjusted operating profit needs to grow by 50 per cent in FY20, higher than DBS's estimate of 30 per cent, while the e-commerce adjusted revenue has to register a 100 per cent compound annual growth rate, above DBS's estimate of 80 per cent.