

DBS posts 3% drop in Q4 profit to S$2.27b; full-year earnings hit record S$10.06b
The bank is proposing a higher dividend of S$0.54 per share and 1-for-10 bonus issue
Tan Nai Lun &
Mia Pei
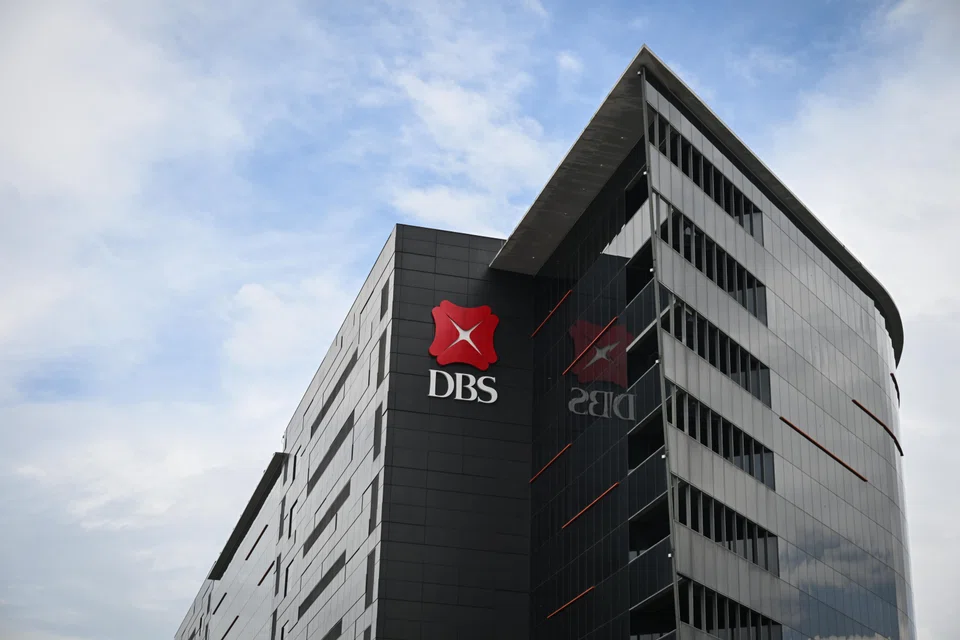
DBS reported net profit of S$2.27 billion for the fourth quarter ended December, 3 per cent lower than the S$2.34 billion recorded in the year-ago period.
The net profit, which included one-off costs, missed a S$2.39 billion consensus forecast in a Bloomberg survey of two analysts.
Excluding one-time items costs from the acquisition of Citigroup’s Taiwan consumer banking business and a S$100 million corporate social responsibility commitment to charitable causes, net profit would have been S$2.39 billion, up 2 per cent on year.
The figure also missed the S$2.44 billion estimate on the adjusted profit figure in a Bloomberg survey of three analysts.
Compared with the previous quarter, net profit fell 12 per cent due to a lower net interest margin and seasonally lower non-interest income, said Singapore’s largest bank on Wednesday (Feb 7).
“Overall, it’s a fairly good solid quarter. The key takeaways to me are that the momentum is coming back in the underlying business, especially in the fee income line,” said CEO Piyush Gupta at a media briefing.
Total income for Q4 stood at S$5.01 billion, 9 per cent higher than the S$4.59 billion in the same period the year before.
Net interest margin (NIM) for the group was up eight basis points (bps) to 2.13 per cent for the quarter, up from 2.05 per cent in the previous corresponding period, and down six bps on the quarter.
Net interest income under its commercial book rose 7 per cent year on year to S$3.64 billion for the quarter.
Commercial book net fee income rose 31 per cent from the year before to S$867 million, on the back of increases across most fee income streams and the consolidation of Citi Taiwan.
Commercial book other non-interest income rose 22 per cent to S$390 million on higher treasury customer sales to wealth management customers.
The bank’s non-performing loans ratio was at 1.1 per cent, unchanged from the same period a year earlier.
The lender declared a dividend of S$0.54 per share for the period, up from S$0.42 per share in the previous Q4. This brings the ordinary dividend for the full year to S$1.92 per share.
In addition, DBS proposed a bonus issue on the basis of one bonus share for every existing 10 ordinary shares held.
The bonus shares will qualify for dividends starting with the first-quarter 2024 interim dividend and will increase the pace of capital returns to shareholders.
It added that the annualised ordinary dividend going forward will be S$2.16 per share over the enlarged share base, 24 per cent higher than the S$1.92 per share for FY2023.
To hold the group’s management accountable for the year’s multiple digital disruptions, variable compensation for Gupta and other members of the management committee was collectively cut by 21 per cent from a year earlier.
Gupta took a deeper cut of 30 per cent, or about S$4.1 million, on the variable compensation. He earned S$15.4 million in FY2022.
DBS’ total allowances for Q4 of S$142 million were higher than the year before, on the absence of a general allowance write-back in FY2022.
Meanwhile, full-year net profit rose 23 per cent to a record S$10.06 billion.
Full-year total income grew 22 per cent to S$20.18 billion, also a record high, driven by a higher NIM, increased fee income and record treasury customer sales.
This brings the bank’s full-year return on equity (ROE) to a record 18 per cent.
“Although deposit costs also increased, the pace was slower compared to asset yields,” said DBS.
More settled macro outlook
Moving into 2024, Gupta noted that the macroeconomic outlook around the world is now looking brighter than it did during the bank’s last briefing in November for its third-quarter results.
“There are obviously still geopolitical risks – China’s still challenging, North Asia growth is subdued – but on the whole, the whole economic environment is actually a little bit better than I forecasted three months ago,” he said.
Gupta expects the bank to be able to sustain its underlying profits in a S$10 billion range, notwithstanding headwinds from interest rate changes.
Net interest income will likely be around 2023 levels, supported by the full-year impact of Citi Taiwan consolidation, while full-year NIM is likely slightly below its 2023 exit NIM of 2.13 per cent.
Gupta is expecting five rate cuts, beginning around June to July until the end of the year.
“If NIM drops more because rates are cut earlier or are sharper, (although) it is not my base case… I think we’ll be able to make it up through loan growth,.” he said.
The bank’s loan growth assumption is in the low single digits, but it may see a boost if rate cuts are sharper.
Meanwhile, Gupta expects the bank to post double-digit fee income growth with a boost from its new Citi Taiwan portfolio, strong new net money inflows and more settled market views.
The bank assumes its special provision will normalise to 17 to 20 bps in 2024, and general provisions will be released if special provisions are higher than expected.
Nevertheless, Gupta noted that the bank has not seen any pick-ups in delinquencies or poor credits. Non-performing loans are coming down, with no challenges in any sector in particular, or geography.
“I’m being a little cautious and saying 17 to 20 bps – because of the higher interest rate environment, you might see a pick-up, but it’s not that we’re seeing any issue anywhere,” he said.






