Earnings wrap: Singapore banks make handsome beat on estimates in Q1
SINGAPORE banks breezed through earnings estimates in Q1, with profits rising from the year-ago quarter on strong fee income and smaller impairments.
These more than offset the impact from weaker net interest income, reflecting compressed rates.
The local trio joined global banks that have also shot past expectations on stronger trading income, as well as writebacks on bad-debt provisions.
JPMorgan beat earnings estimates in Q1 with record gains, boosted by strong trading activity and a US$5.2 billion release of loan-loss reserves. US' largest bank posted a quarterly profit of US$14.3 billion, jumping from the year-ago quarterly profit of US$2.87 billion.
All three banks here are likely to review the Asia-Pacific assets put up for sale by Citi. The Wall Street giant had said it would exit 13 consumer markets. Many of these are key markets for Singapore and Asia-focused banks, and include Indonesia, Malaysia, Taiwan, Thailand, Vietnam, India and China.
Eugene Tarzimanov, vice president, senior credit officer, Moody's Investors Service said: "We expect that Singapore banks' profitability will continue to recover in 2021 amid receding asset risks and improving operating conditions."
Here is a summary of their results:
DBS
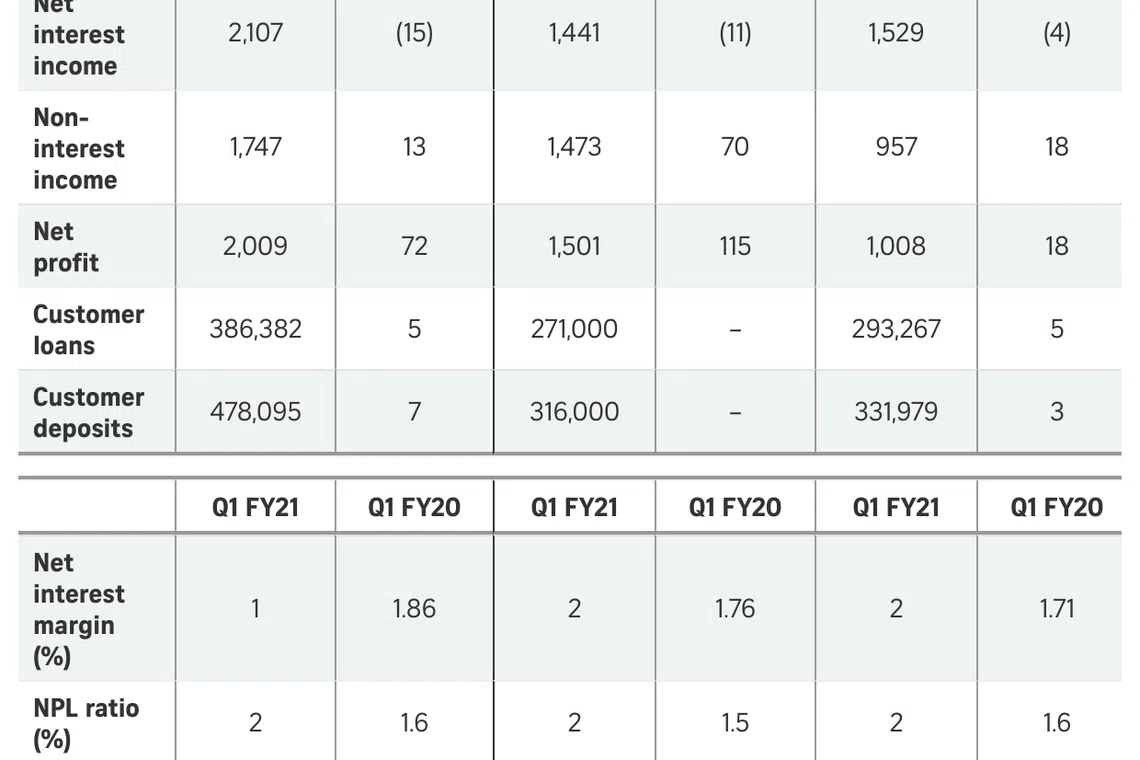
D05 posted a 72 per cent year-on-year rise in Q1 net profit, cracking the S$2-billion mark in quarterly net profit.
Net fee income increased 15 per cent from a year ago to a new high of S$953 million, with wealth management fees rising 24 per cent to a record S$519 million. Other non-interest income rose 12 per cent y-o-y to S$794 million, as trading income doubled on the back of new highs for both treasury markets non-interest income and treasury customer income.
Net interest income fell 15 per cent y-o-y to S$2.11 billion.
Credit costs also appear to be stabilising, resulting in a general allowance write-back of S$190 million and specific provisions back to pre-pandemic levels of S$200 million or 21 basis points.
With that, allowances for the first quarter in 2021 stood at S$10 million, miles off from the S$1.09 billion booked in the year-ago period.
Total allowances for the full year are likely to be below S$1 billion.
DBS, the only bank of the trio to offer quarterly dividends, has declared an interim dividend of 18 Singapore cents per share. This is lower than 33 Singapore cents in interim dividend declared for the same period of 2020, but in line with the Monetary Authority of Singapore's guidance for local banks to moderate their dividends. It will be payable on or about June 25.
OCBC
O39 said Q1 net profit more than doubled, hitting a new high in fee income while making a far smaller allowance compared with the year-ago period. Net profit for the first three months ended March 31, 2021 stood at S$1.5 billion, compared with S$698 million in the year-ago period.
Non-interest income in the first quarter surged 70 per cent from the year-ago quarter to S$1.47 billion. Fees and commissions rose 7 per cent to S$585 million. Profits from life insurance surged to S$422 million, compared with S$106 million from the year-ago period. Trading income rose several times to S$316 million from S$18 million in the year-ago period.
Net interest income for the quarter fell 11 per cent from the year-ago quarter to S$1.44 billion.
Total allowances were S$161 million, down 75 per cent from the year-ago period.
UOB
U11 posted an 18 per cent rise in net profit for Q1 on record fee income. Net profit for the first three months ended March 31, 2021 stood at S$1.01 billion, compared with S$855 million in the year-ago period.
Net fee income was up 24 per cent compared with the year-ago quarter to S$638 million. Other non-interest income rose 7 per cent over the year to S$319 million.
Net interest income for the quarter fell 4 per cent from a year ago to S$1.53 billion.
Impairment charges fell 29 per cent from a year ago to S$201 million.
The bank signalled that it deemed it a little premature to write back provisions at this point. While non-performing loan (NPL) emergence remains low, the various relief measures still in place may have a lagging impact on NPLs.
But UOB will look to ease the addition of provisions, with credit costs expected to come in below 30 basis points for the year. This was previously estimated at 30-40bps.
READ MORE: Singapore banks may shop for buys as fears over bad debts recede