

Elite Commercial Reit targets S$1 billion market cap to wow investors
Besides more acquisitions, it enjoys stability with a recession-proof tenant base as 99% of its portfolio is leased to the UK government.
Singapore
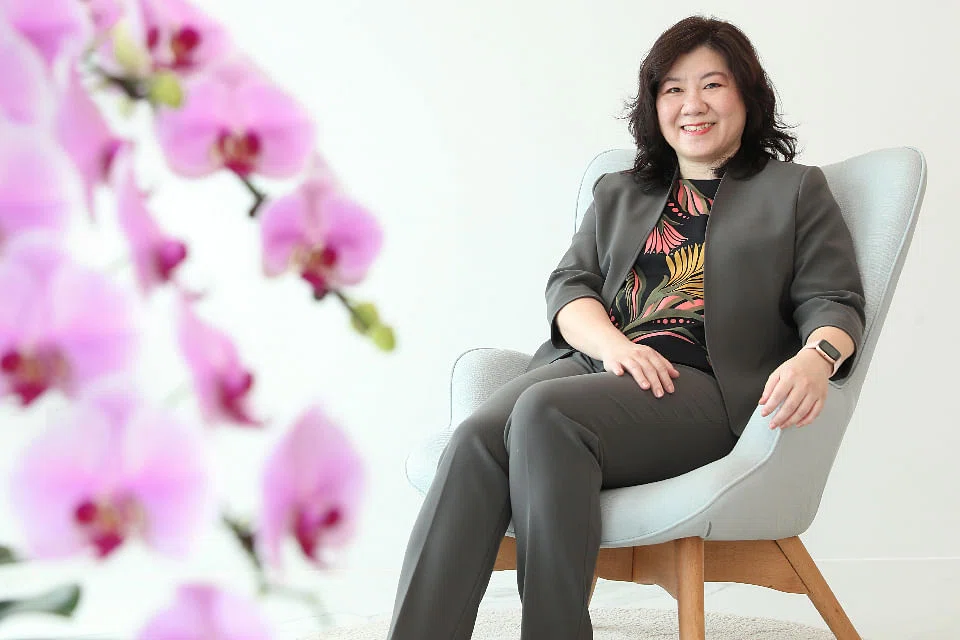
SHALDINE Wang, chief executive officer of the manager of Elite Commercial Reit, is on a mission to whet investor appetite with more acquisitions, bump up the Reit's market value and reassert its recession-proof appeal.
Elite Commercial Reit made its debut in February last year as the first UK-focused real estate investment trust (Reit) to be listed in Singapore. It is also the first Reit here to be denominated in the British pound.
On Feb 6, 2020, it opened 3.7 per cent higher than the initial public offering (IPO) price of £0.68 or S$1.21 per unit. Just over a week later, on Feb 18, it hit a high of £0.755.
Then, the world descended into coronavirus chaos.
"The Reit, unfortunately, listed at the time when everyone was going into a lockdown and hibernation," said Ms Wang. "Right out of the gate, we were struck with Covid-19 and everyone went down."
A month after its debut on the Singapore bourse, Elite Commercial Reit sank to a low of £0.485. Since then, the counter is right back where it started. Units of Elite Commercial Reit closed at £0.67 on Oct 1 - just shy of its IPO price in February last year. To date, the counter has barely moved from the £0.665 it recorded at the start of the year.
"We had rebounded quite quickly, so our recession-proof investment strategy has proven itself. The Reit has been performing well," Ms Wang said.
"We are probably not as exciting as people who are in the high tech space today. . . but this provides a very different kind of strategy and should have a place in everybody's portfolio, when you look at a balanced portfolio in terms of investments," Ms Wang said.
Pandemic- and recession-proof
At the heart of this stability is the Reit's tenant base. Over 99 per cent of the Reit's portfolio is leased to the AA-rated UK government.
Its largest tenant by far is the Department for Work and Pensions (DWP), which accounts for 92.8 per cent of the Reit's portfolio by gross rental income. Other tenants include the Ministry of Defence, the National Records of Scotland, and HM Courts and Tribunals Service.
"Although these are commercial offices, they are actually being used by the government as crucial social infrastructure buildings instead," said Ms Wang. "And because of the importance of these buildings, they're all fully occupied. We don't have any vacancies in our portfolio."
In the DWP, the UK's biggest public service department responsible for welfare, pensions and child maintenance policy, the Reit manager sees a counter-cyclical and recession-proof occupier.
Ms Wang explains that even in normal times, when the economy is performing fairly well, there is always a base level of claimants, including for pensions and disability benefits. During downturns, such as the global financial crisis and the current Covid-19 pandemic, there is a surge of claimants due to an increase in unemployment.
"If you are unemployed, you go to a Jobcentre Plus (under the DWP), and they will try to help you to get back to work," Ms Wang said. "They have actually increased the number of centres throughout this period, and they were so desperate that they were taking up empty slots at shopping centres on a temporary basis to address the needs."
Elite Commercial Reit enjoys a long weighted average lease expiry of 6.6 years. The majority of its leases, however, have a break clause after a certain tenure.
A key risk for the Reit is that just under two-thirds of its total portfolio rent have lease break options that will come into effect at the end of March 2023, with a minimum one-year notice to be served. If the break options are not exercised by March 31, 2022, the leases will continue up to the end of March 2028.
As pundits see it, it is "unlikely" that the tenants will choose to exercise the lease break option.
"The properties in the portfolio are assets that provide important social services to close to 30 per cent of the UK population and they are strategically chosen to serve the local communities," said DBS analyst Dale Lai in a recent report. DBS has a "buy" call on Elite Commercial Reit with a target price of £0.80.
The bad news for the Reit is that the lease break for East Street, Epsom has been exercised. The Reit manager says it has received an offer for the property at £2.9 million, about 21 per cent above the valuation of £2.4 million as at end-December 2020, and is undertaking due diligence on the offer and purchaser.
It added that it is also reviewing potential asset enhancement initiatives, as the building also offers potential for continued commercial use as well as conversion or redevelopment for alternative uses.
"The option was exercised as the property could not accommodate DWP's expansion plans. We believe that the likelihood of tenants exercising the lease break options for the other properties is fairly low as there are social implications involved when government agencies move offices," Mr Lai said.
"We also believe that these agencies have to undergo a rigorous assessment exercise before any relocation or commitment is made for long leases, making it unlikely for the tenants to exercise the lease break option," he added.
A case in point is The Forum, Stevenage, whose lease expiry will be extended to March 31, 2028, as the lease break option was not exercised.
Analysts see the end of March 2022 as a potential "key catalyst" for the Reit.
"Our current book values are conservative as we have assumed that half of the break options will be exercised. Given that it is highly unlikely that the tenants will exercise this break option, we can expect to see a significant uplift in book valuations," Mr Lai said.
Double threat
For the six-month period ended June 30, Elite Commercial Reit posted distribution per unit (DPU) of 2.63 pence - beating its IPO forecast of 2.42 pence by 8.7 per cent. The H1 DPU was also up 34.9 per cent from DPU of 1.95 pence in the year-ago period.
Gross revenue was up 37.7 per cent to £15.9 million for the half-year period, from its IPO projection of £11.5 million, while net property income of £15.4 million was 37 per cent higher than its IPO forecast of £11.2 million.
The stellar H1 results were driven by contributions from the Reit's maiden acquisition of 58 properties in the UK for £212.5 million in March this year.
The acquisition - just over a year into its listing, and amid a protracted recovery from the pandemic - came as a surprise to some market watchers. But the Reit manager sees it as part of its plans to attract investors.
"When we were listing this portfolio, we were cognisant that it is a very small Reit compared to a lot of big players in the market," said Ms Wang.
She noted that smaller Reits tend to be dogged by the double threat of lower market capitalisation and poorer liquidity, and hence face challenges with attracting investors.
One of her biggest challenges has been reaching out to potential investors amid the Covid-19 pandemic that has plagued most of the Reit's listed lifetime.
While the Reit manager says it continues to engage with investors via virtual conferences and webinars, Ms Wang added: "We can't really meet face-to-face, there are no retail events that are being held on a large scale ... So a lot of work needs to be done to just get people to understand who we are, what we do, and the things that we focus on.
"We think that if we can quickly acquire, we will be able to attract more investors. And true enough, that's how we have gotten more institutional investors onto the books today," Ms Wang said. "We are continuing to look into acquisitions. Once it gets to a certain size that institutional investors are interested in, I guess you will see a bit more liquidity in the stock.
"There's always the ideal market cap that everyone looks at - the S$1 billion target - so that investors, or institutional investors, start to look at you. So that's our target as well."
Following its acquisition in March, the Reit's portfolio has grown to £515.3 million. Its market capitalisation stood at £317.8 million as of Oct 1.
Maybank Kim Eng notes that the Reit is fast approaching the S$1 billion mark for assets under management.
"Elite Commercial Reit has been sizing up rapidly," said analysts Matthew Shim and Chua Su Tye in an "unrated" report on Oct 1. "Given its lease structures, inorganic growth is the priority. On this front, management is actively on the look-out for further acquisitions within the UK, specifically those that fit its 'social infrastructure' thematic.
"Potential third-party deals are aplenty, though its sponsor has another £150 million tailor-made portfolio of UK properties with public sector tenants in the pipeline."
Ms Wang pointed out that the Reit can potentially grow organically as well. "In terms of growth, something that maybe investors are not that aware of is that we do have some land bank," she said. "We have about 42 acres of land that has not been developed."
Notably, Elite Commercial Reit is one of 10 actively traded S-Reits not included in the FTSE EPRA Nareit global index series. This will see the Reit miss out on some expected benefits, including improved liquidity, investor visibility and potential investability, as well as lowered cost of equity and ease of making distribution per unit-accretive acquisitions via partial equity raising. All the 10 excluded S-Reits had market caps below S$1 billion.
Already, the March acquisition has pushed Elite Commercial Reit's gearing ratio to 42.1 per cent. This gives the Reit an available debt headroom of approximately £29 million based on a gearing ratio of 45 per cent, or about £85 million based on the maximum gearing ratio of 50 per cent.
Well-capitalised
As at end-June, it had total debt of £228 million with an average weighted debt maturity of 2.5 years and interest coverage ratio of 6.4 times. The Reit manager says it is looking at ways to reduce its debt ratio, but adds that it remains well-capitalised with adequate working capital and debt headroom to meet its ongoing obligations. One of these avenues is the establishment of the distribution reinvestment plan (DRP), which was announced in June to allow unitholders to elect to receive new units in the Reit in lieu of cash.
In addition, the Reit's wholly owned subsidiary, Elite UK Commercial Holdings, was listed on The International Stock Exchange (TISE) in August.
The TISE listing will see the tax treatment of the Reit be on par with other UK Reits. Elite Commercial Reit said its applicable principal tax rate will be reduced to 15 per cent, from the current 19 per cent, based on the double taxation treaty between the UK and Singapore. Any latent capital gains and corresponding deferred tax liabilities of the properties held by Elite Commercial Reit will be eliminated.
"This could ultimately improve distributable income and DPU for unitholders," said Maybank KE analysts.
For now, analysts are not too worried about the Reit's finances. "Elite Commercial Reit remains well capitalised with a strong balance sheet," said CGS-CIMB analysts Lock Mun Yee and Darren Ong in a recent report. "(It) continues to maintain a healthy debt maturing profile and will not face refinancing risks until FY2023, in our view."
CGS-CIMB has an "add" recommendation on the Reit, with a target price of £0.826.
"Elite Commercial Reit currently offers the second-highest yield among the S-Reit offshore universe and trades below book value," said Maybank KE's analysts. "This is despite its reported DPU figures over the last six quarters consistently surprising on the upside relative to initial IPO projections by an average of 4.4 per cent.".
They note that consensus estimates put Elite Commercial Reit's yield at an average of 8.1 per cent for FY2021, and a price-to-book ratio of 0.94 time.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Can CDL become a powerhouse in fund management?

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

Data centre energy demand from Asean telcos not a ‘big risk’, says industry group

