

Emerging-market bonds poised for ‘very strong run’ after years of outflows: Aberdeen
Drivers include the improved credit ratings of these economies and potential Fed rate cuts
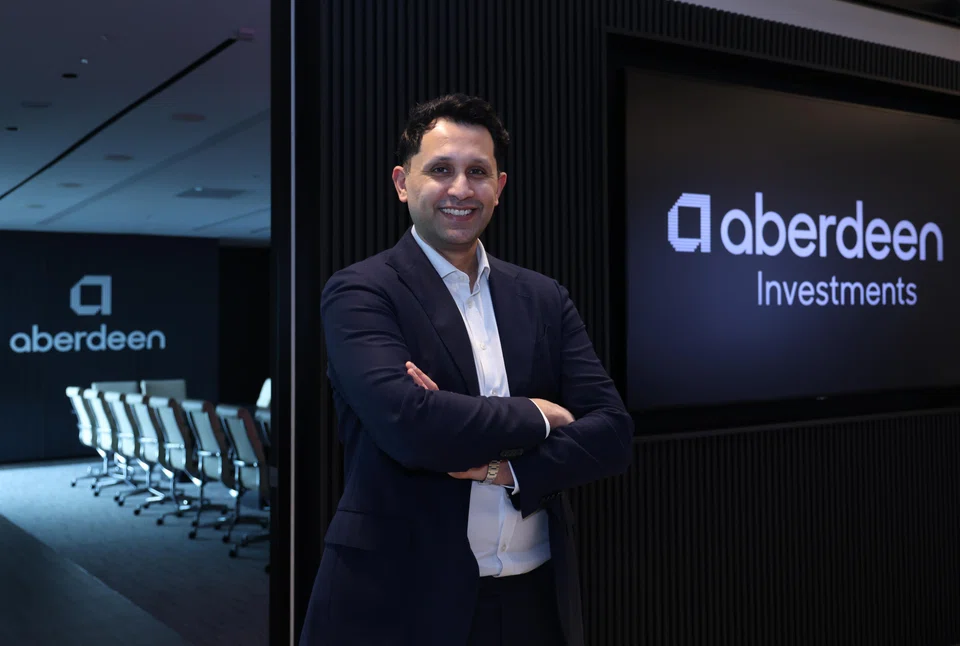
[SINGAPORE] Emerging-market bonds are trading at historically attractive levels and could be headed for a period of “very strong performance” after years in the doldrums, said Siddharth Dahiya, global head of emerging-market debt at Aberdeen.
Real yields – the inflation-adjusted return that investors earn – on many emerging-market bonds are now in the 3 to 4 per cent range, noted Dahiya, in a recent interview with The Business Times.
This is higher than the 1 to 2 per cent, or even negative rates seen during the Covid-19 years when inflation spiked, and above much of what was seen over the past 10 to 15 years.
The growth differential, or the difference in real interest rates, between emerging and developed economies is also broadly higher, with the differential for “frontier” markets near decade highs, he added.
Emerging markets typically refer to faster-growing developing economies such as Brazil, India and Indonesia, while frontier markets are generally smaller or less-liquid markets, such as Nigeria or Kenya.
Because these economies tend to have less-stable policy frameworks, shallower capital markets and greater currency volatility, their assets are generally seen as riskier than those in developed markets.
Investors therefore demand higher yields as compensation, which is why emerging-market bonds typically offer higher potential returns.
In 2025, the JPMorgan Emerging Markets Bond Index Global Diversified Composite, a global benchmark for emerging-market bonds issued in US dollars, returned 14.3 per cent, based on Bloomberg data, compared with 6.5 per cent in 2024.
Meanwhile, the JPMorgan Government Bond Index - Emerging Markets Global Core – which tracks bonds issued in emerging markets in local-currency terms – returned 19 per cent in 2025, compared with minus 2.4 per cent in 2024.
The outperformance in 2025 came after what investors coined as a “lost decade” in emerging-market debt. This was marked by outflows, the most significant of which occurred in recent years, before reversing last year.
In 2025, emerging-market bond funds saw US$31.8 billion in inflows, after three years of consecutive outflows between 2022 and 2024, according to data from JPMorgan.
The three-year period of outflows, in particular, was “cumulatively the worst three years of flows for emerging-market debt in its history”, observed Dahiya.
The reversal in 2025 is down to a few factors, and not just the “de-dollarisation” theme that many investors attribute it to, he said.
“It would be wrong to say that it’s only (because of) the de-dollarisation theme, or moving away from US assets. That has played a part somewhat, but the real drivers for emerging-market performance have been more fundamental, more intrinsic, rather than extrinsic or external drivers.”
These include improved credit ratings – and subsequently rating updates by ratings agencies – and stronger balance sheets from emerging markets, particularly frontier ones.
Many went through “painful restructuring” during the Covid-19 period and in the years surrounding it, but are now “enjoying the tailwinds” from having done so, he pointed out, citing Nigeria as an example.
This has resulted in the growth differential between frontier markets and developed economies now at a decade-high in favour of the former, he said.
“Why is the growth differential important? It’s because this tends to bring more attention, more flow into emerging markets,” he added. “Money comes when there is more growth in emerging markets, and growth brings flows, and flows brings performance.”
US Fed tailwinds
Another factor that boosts emerging-market debt’s outlook is rate cuts by the US Federal Reserve.
High interest rates, implemented by the US central bank to combat inflation in the past few years, have led investors to be “put off” from more risky asset classes, such as those in emerging markets.
“If you could earn 4.5, 5.5 per cent on fairly risk-free assets, then your inclination to go out and buy something with a 7, 7.5 per cent (yield) is much lower,” Dahiya explained.
“But if we think that the US Fed will continue to cut, and there’re maybe two more (rate) cuts baked in, and the short-term risk-free rate is going to be lower from here, then emerging markets become attractive.”
The weaker greenback also helps with emerging-market bonds’ constructive outlook, particularly for those trading in local-currency terms, as a softer US dollar reduces currency losses for foreign investors and boosts total returns when local-currency bond payments are converted back into US dollars.
Buyers of emerging-market debts remain predominantly Western, as Asian investors typically show little inclination to increase their positions in these markets.
That is because there is already a “big enough investment universe” in Asia, and some investors also carry “fatigue or carefulness” on emerging-market assets, due to having made losses in the Chinese property market.
“The appetite for emerging markets – it feels like the rest of the world has a slightly higher appetite,” he said.
Risks that could derail the constructive outlook for the asset class include external shocks such as spikes in inflation, or a sell-off in commodities, as many emerging markets are large commodity exporters.
Another theme to watch are national elections, with some major Latin American countries, such as Brazil and Colombia, heading for the polls later this year.
“It’s the free will of the people (as to who) they (will) choose, but markets can like – or not like – those people,” Dahiya noted.
Yet, the outlook for emerging markets remains strong, he said, notwithstanding unforeseen shocks.
“The tailwinds that we are seeing in emerging markets – this is not a short cycle. We think that this is a longer-term cycle and more structural in nature for now, and we are towards the beginning of this cycle,” he added.
TRENDING NOW

MAS allocates S$1.45 billion to five asset managers in third EQDP batch: Chee Hong Tat

UOB found ‘grossly negligent’ over Stamford Land rights issue advice, to pay S$1.9 million
East Coast Road, Serangoon North View private-housing sites launched for sale

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

