

Europe-focused S-Reits at multi-year lows, but Reit managers say their assets can withstand shocks
THE trio of Singapore-listed real estate investment trusts (S-Reits) focused on the UK and Europe – Cromwell European Reit (CE Reit), IReit Global and Elite Commercial Reit – have suffered the brunt of a risk-off sell-off this year, shedding between 21.6 per cent and 30.8 per cent in the year to date.
In comparison, the FTSE Straits Times Reit Index is down about 14 per cent in the year to end-September; and the benchmark Straits Times Index is flat.
But some market observers say the sell-off may have been overdone. Fundamentals in the UK and Europe markets remain stable despite inflation, recession and currency risks clouding the outlook.
“The drop in share prices came largely on the back of persistent inflation in the US, resulting in the US Federal Reserve delivering another huge 75-basis-point hike (in interest rates) in September 2022 but also guiding that more is to come till ‘the job is done’ in taming inflation,” DBS analysts Derek Tan, Rachel Tan, Dale Lai and Geraldine Wong said in a recent report.
The analysts note that the Europe-focused S-Reits are “looking attractive” as they are trading at multi-year lows in terms of price-to-book valuations while yields are close to decade-high levels.
“We believe this is an opportunity to look at selected real estate investment trusts (Reits) with a more stable earnings profile,” they said.
One of the names DBS said investors should consider is CE Reit, due to its stable earnings profile.
Simon Garing, chief executive of the manager of CE Reit, noted that the Reit’s distribution per unit (DPU) for the first half of FY2022 was up 2.3 per cent year on year despite external challenges.
He added that CE Reit generated a total return of 13.5 per cent in FY2021, outperforming that of the FTSE S-Reit index.
“This demonstrates CE Reit’s ability to withstand prolonged economic shocks,” Garing said.
As Garing describes it, the unit price performance of listed Reits is driven by three main factors: portfolio performance in terms of DPU and total returns, trust in the management team, and market sentiment as a product of perception of risk.
“Despite having demonstrated credible operational performance, CE Reit’s unit price is not immune to external headwinds,” he said.
But he believes “underlying European real estate fundamentals are in good shape”.
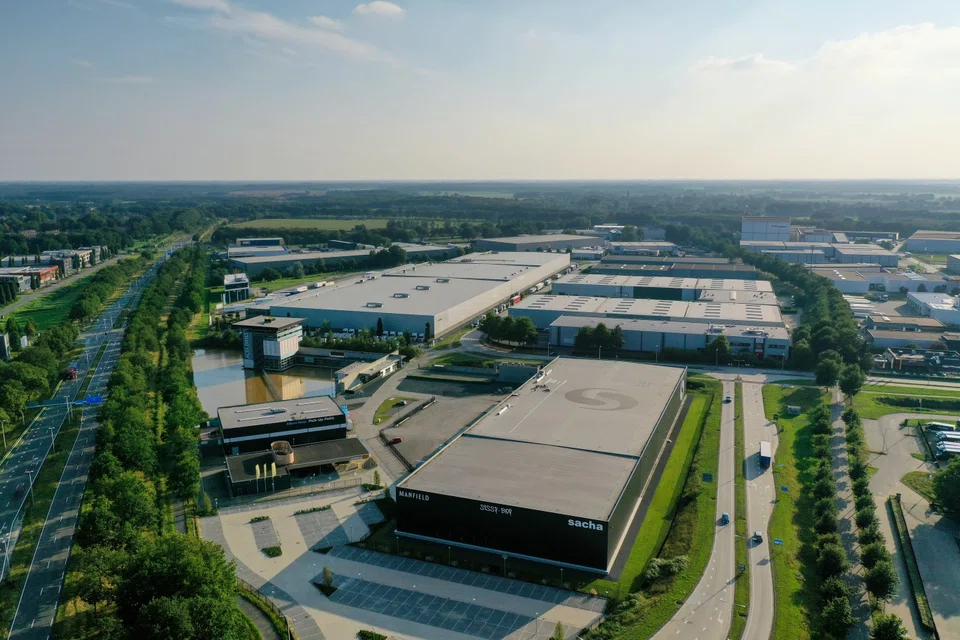
For example, he noted that average vacancy rates in CE Reit’s light industrial and logistics segment fell to a record-low average of 2.5 per cent as acceleration in e-commerce and supply chain reorganisation continue to drive strong demand for such spaces in Europe.
In addition, he pointed to data that showed the average office vacancy rate for CE Reit’s investment markets was at 9.7 per cent in Q2.
“Data from the Google Mobility Index for workplace and transit stations shows that returns to the workplace and access to transit stations are almost back to pre-pandemic levels in CE Reit’s key office markets,” Garing said. “CE Reit is well-positioned to capitalise on the strong occupier demand for strategically located logistics space, as well as the recovery in office leasing in Europe.”
The manager of another Europe-based Reit, IReit Global, noted that its portfolio has “remained resilient” in H1 due to its stable leases with blue-chip tenants.
Louis d’Estienne d’Orves, CEO of the manager of IReit Global, added that this resilience is also boosted by the fact that IReit “has exposure only to core western European markets with strong liquidity and political stability”.
Importantly, he noted that, similar to his Europe-focused Reit counterparts, IReit Global is likely to suffer less impact from the surging inflation that has left investors jittery.
“It is worth noting that most of IReit’s portfolio leases have rental escalation clauses pegged to inflation, hence IReit has been benefiting from higher rents due to rising inflation,” d’Estienne d’Orves said.
“On the cost side, all the utilities costs for the leased spaces and common areas are directly paid by the tenants. This is unlike assets located in some parts of Asia, including Singapore, where the utilities costs for the common areas are borne by the landlords themselves – and not the tenants,” he added.
Another of IReit Global’s merits, he said, lies on the capital management front.
IReit’s bank borrowings – almost all of which have been hedged with interest rate swaps and capped at an all-in interest cost of 1.8 per cent over the tenure of the borrowings – will only mature in 2026 and 2027. This, d’Estienne d’Orves said, limits any impact from rising interest rates.
“IReit’s aggregate leverage has improved to 30.8 per cent as at Jun 30, from 32.1 per cent a quarter ago, as a result of higher portfolio valuation,” d’Estienne d’Orves said. “This is one of the lowest within the entire S-Reits sector – a reflection of IReit’s strong financial position.”
The third Europe-focused S-Reit, Elite Commercial Reit, is drawing some concern due to its high gearing ratio.
In a separate report, DBS analysts Yeo Kee Yan and Janice Chua flagged Elite Commercial Reit as one of the S-Reits likely to be worst hit by higher-for-longer interest rates ”given its gearing of 41.9 per cent and 45 per cent of debt expiring in FY22-23”.
“The interest rate movement is something we are watching closely as it would impact our cost of debt, which was last reported at 2.3 per cent as at Jun 30,” said Shaldine Wang, CEO of the manager of Elite Commercial Reit.
“About 63 per cent of our interest rate exposure is fixed, thereby limiting the impact of rising rates on the Reit,” she added.
Wang also noted that Elite Commercial Reit has an extension option built into the existing agreement for the £94 million (S$149.4 million) loan facility that is expiring in January 2023.
“We are currently at an advanced stage (of negotiations) and remain on track to finalise refinancing ahead of the maturity date in January 2023,” Wang said, adding that the manager will update the market when the refinancing matters are completed.
“The group remains well capitalised, with excellent relationships with funding partners and banks,” she added.
The Reit manager also sought to allay fears of the impact of a weakening British pound on the Reit. “The assets, liabilities and distributions by Elite Commercial Reit are all in pounds sterling, hence there is a natural hedge,” Wang said.
At the same time, the Reit manager said the Reit’s counter-cyclical nature – with 99 per cent of the portfolio leased to the UK Government, especially the Department for Work and Pensions (DWP) – provides a stable rental income profile.
“The Reit’s assets are used as centres to provide social benefits and support to the local communities, such as helping the unemployed get back into the workforce. Hence, the demand for such centres remains resilient throughout economic cycles, and may increase during times of economic uncertainty,” Wang said.
TRENDING NOW

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

