

Fortis' woes pile pressure on Singapore-listed RHT Health Trust
S$950 million deal to buy Fortis' healthcare assets at risk over hospital chain's debt and legal woes, probes by regulators and slashed credit rating
Anita Gabriel
Singapore
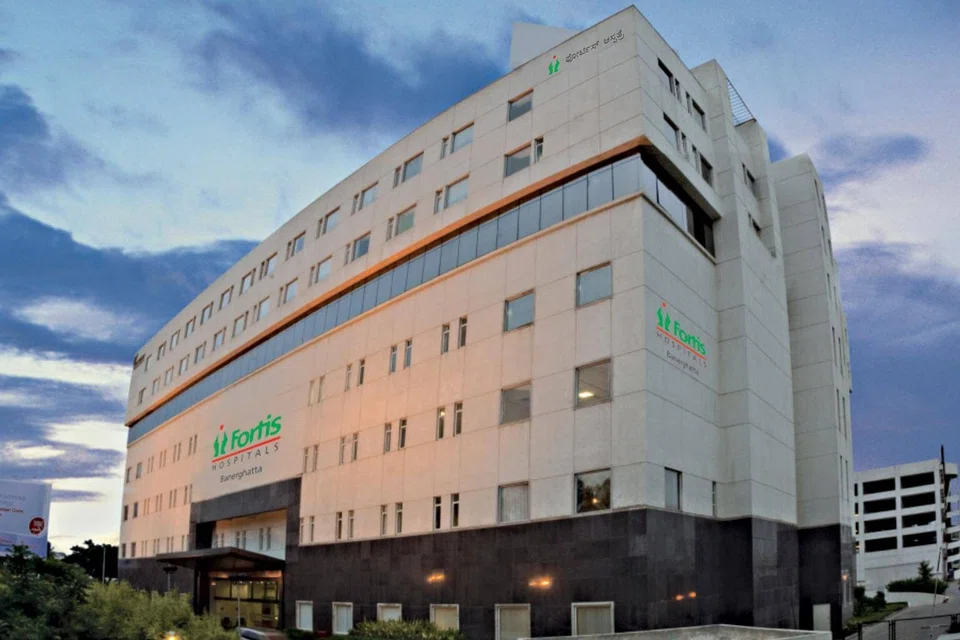
THE deepening debt and legal woes assailing India's second largest hospital chain Fortis Healthcare, probes by regulatory authorities there, and the uncertain outcome of an intensifying bidding war for its assets by potential white knights have turned up the heat on Singapore-listed RHT Health Trust (RHT).
On tenterhooks is a planned S$950 million deal that RHT's trustee-manager had formally inked in mid-February for Fortis Healthcare - the trust's sponsor - to buy all its healthcare assets in a major transaction that could unlock value and line unitholders' pockets with a meaty special distribution from the sale proceeds.
"We are concerned about the current situation as we would like the transaction to conclude in a timely fashion," said a key RHT executive when contacted by The Business Times. "We are supportive of any white knight stepping in to assist Fortis fulfill its obligations under the operating agreements to buy back RHT's assets."
The long-stop date for the proposed deal, that was first announced last November and would need unitholders' nod, is some five months away (end-September).
It involves the sale of all of RHT's Indian subsidiaries, its 49 per cent interest in Fortis Hospotel and entire asset portfolio - 12 clinical establishments (CEs), four greenfield CEs and two operating hospitals in India.
Last Friday, RHT - Singapore's first listed business trust comprising Indian healthcare assets - launched a consent solicitation exercise slated for April 30 for holders of its S$120 million notes due in July 2018 to approve the sale and extend the notes' maturity date by six months.
The trust has other worries as a result of the severe cash crunch facing its nearly 30 per cent controlling unitholder Fortis.
On April 5, RHT said that some 257 million rupees (S$5 million) remained outstanding from Fortis in respect of service fees and interest income on the compulsorily convertible debentures (CCDs) due for nine months to December 2017.
BT understands that the trustee-manager has issued several notices to "actively chase and follow up" the matter for Fortis to clear the oustanding sum. The amount may be small in the big scheme of things but no less pivotal.
"One of the key points under the master purchase agreement (on the proposed disposal) is that it is only binding if all outstanding fees are paid and Fortis is up to date on all dues," said a source with knowledge on the matter.
Is there worry that the buy-back of RHT's assets by Fortis could be jeopardised as a result of Fortis' troubles?
"I don't think we are in that situation right now," said a source close to the trust. "There are a number of parties making offers. So, it's probably too early to gauge."
Sources say that no matter who ends up with Fortis, the buyout of RHT's assets will pull through as it made commercial sense. "There's a huge value leakage as some 70 per cent of Fortis' assets are parked under the trust. So, it's a deal that any party will want to push through," said one source.
Meanwhile, Fortis is being probed for alleged financial irregularities by India's fraud watchdog and stock regulator.
The group's founders, Indian tycoons Malvinder Singh and his brothers Shivinder, have seen their stake shrink from 34 per cent to less than 1 per cent after they failed to repay loans and lost the Fortis shares that were put up as collateral.
They resigned from their posts in February and are reportedly facing allegations of siphoning cash out of their firms.
Last week, ratings agency ICRA slashed Fortis' credit rating to reflect very high risk of default, citing its stretched liquidity position that has led to delays in servicing a loan.
Its distressed situation has caught the attention of potential white knights, not least because of Fortis' strategic value as the second largest healthcare platform in India.
There are three contenders so far. They include binding offers from TPG Capital-backed Manipal Hospital, the Munjal and Burman families, and a non-binding expression of interest from Malaysia and Singapore-listed IHH Healthcare.
Sources close to the matter say one or two more bidders could surface in the coming weeks. The bidding war for troubled Fortis looks set to escalate, but one warned: "Above a certain price, it will become fool's gold".
TRENDING NOW

Why US$100 oil, 5% US yields affect Singdollar, ringgit differently vs other Asean currencies
Singapore fintechs struggle to find finance and tech talent

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

Why Tan Aik Keong of digital solutions specialist Agmo wants to make himself less indispensable

