

Frasers Centrepoint Trust H2 DPU falls 1.2% to S$0.0602
Vivienne Tay &
Raphael Lim
FRASERS Centrepoint Trust ’s (FCT) distribution per unit (DPU) for the second half declined by 1.2 per cent to S$0.0602, from S$0.06091 in the same period last year, its manager said on Wednesday (Oct 25). This came as distributions to unitholders declined 0.7 per cent year on year to S$103.1 million from S$103.8 million.
FCT retained S$1.1 million of the income available for distribution to unitholders, but also released S$3 million of distributable income retained in the first half of 2023, the manager said.
The real estate investment trust (Reit) booked gains in both gross revenue and net property income.
Gross revenue was up 1.8 per cent to S$184.1 million for the half-year period, from S$180.7 million in the year-ago period. This was mainly due to an increase in gross rent, attributed to a rise in portfolio occupancy, higher rental reversions and higher contributions from atrium leasing, as well as car park income. The gains were partially offset by the lower gross revenue from Tampines 1, which is undergoing an asset enhancement initiative.
The Reit’s property expenses also rose 3.6 per cent in the second half to S$54.5 million due to higher utilities expenses, repair and maintenance costs, and staff costs. Net property income (NPI) grew 1.1 per cent on year to S$129.6 million for the half year period, from S$128.1 million.
The Reit’s finance costs also jumped 71.3 per cent on-year in the second half to S$45.3 million
Meanwhile, for the full year ended Sep 30, 2023, DPU was 0.6 per cent lower at S$0.1215, versus S$0.12227 the previous year, and distributable income inched up 0.2 per cent to S$207.7 million. Gross revenue was 3.6 per cent higher at S$369.7 million, while NPI rose 2.7 per cent to S$265.6 million for the full year.
FCT’s retail portfolio value rose 0.6 per cent to S$8.74 billion, mainly due to higher valuations of Nex and Causeway Point. The capitalisation rates used by independent valuers remained unchanged from last year.
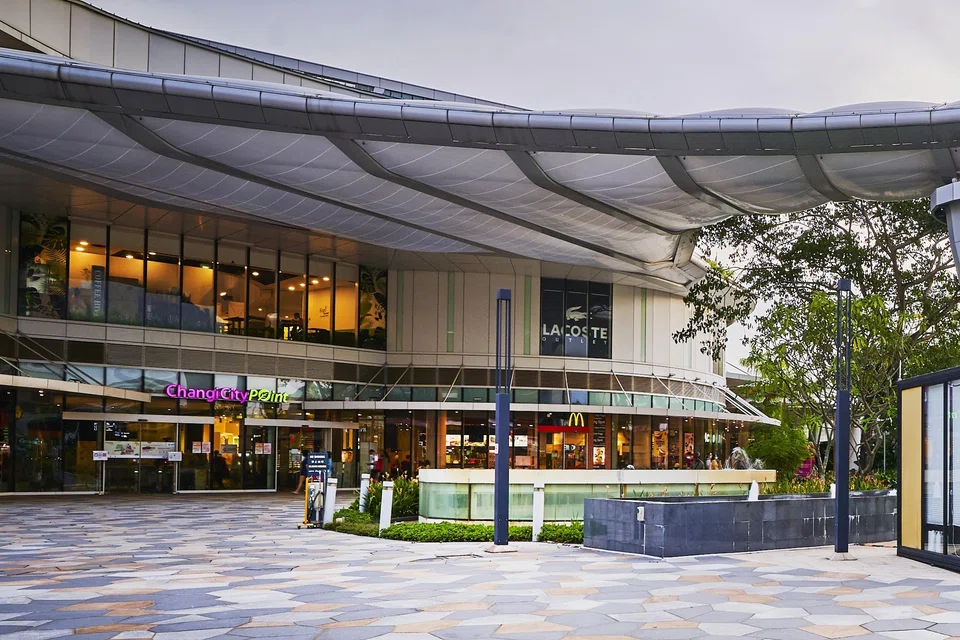
The Reit reported aggregate leverage of 39.3 per cent, but the manager noted this would be 36.1 per cent on a pro forma basis, upon completion of announced divestments of Changi City Point and its stake in Hektar Reit.
Richard Ng, chief executive of the manager, said during a press briefing that the FCT’s gearing level is “relatively healthy” especially in the current environment. While the Reit now has greater debt headroom, Ng added that FCT would be opportunistic in terms of acquisitions and assess what’s available in the market before making any decisions.
The Reit’s average cost of borrowing was 3.8 per cent in FY 2023, and the manager said in its outlook that it expects this to rise above 4 per cent. Around 63 per cent of FCT’s debt is hedged to fixed rates. The manager expects interest rate movements and rising operating expenses to remain the “key factors affecting FCT’s performance”.
Ng said that the market generally is still challenging amid geopolitical issues, higher interest rates, and inflation. But the manager remains positive about its portfolio of assets – which currently has committed occupancy of 99.7 per cent – as demand remains strong, with muted supply coming to the market.
“The large part of our trade mix are actually essential products,” Ng said. “Even in crisis, during the pandemic as we experienced, prime suburban malls continue to be resilient, because it is bread and butter, it is a basic necessity.”
Distributions will be paid out on Nov 29 after books closure on Nov 3. FCT’s units were trading at S$2.09 as at 1.28 pm on Wednesday, down 1.4 per cent.






