

With AI and human advice, DBS helps Singaporeans invest with confidence
Through digiWealth, DBS pairs carefully designed AI with dedicated wealth planning managers to support customers at every income level and life stage
FOR many Singaporeans, building financial confidence starts with knowing what to do next: save for a buffer, protect their family, prepare for retirement or begin investing. Yet, with so many products and so much information competing for their attention, making a start – and keeping at it – can often feel daunting.
DBS has set out to make that easier with digiWealth, the all-in-one wealth platform inside its digibank app. It brings together market insights, investment and insurance solutions, retirement planning tools and access to a dedicated wealth planning manager (WPM), so that customers can see their finances in one place and take the next step when they are ready.
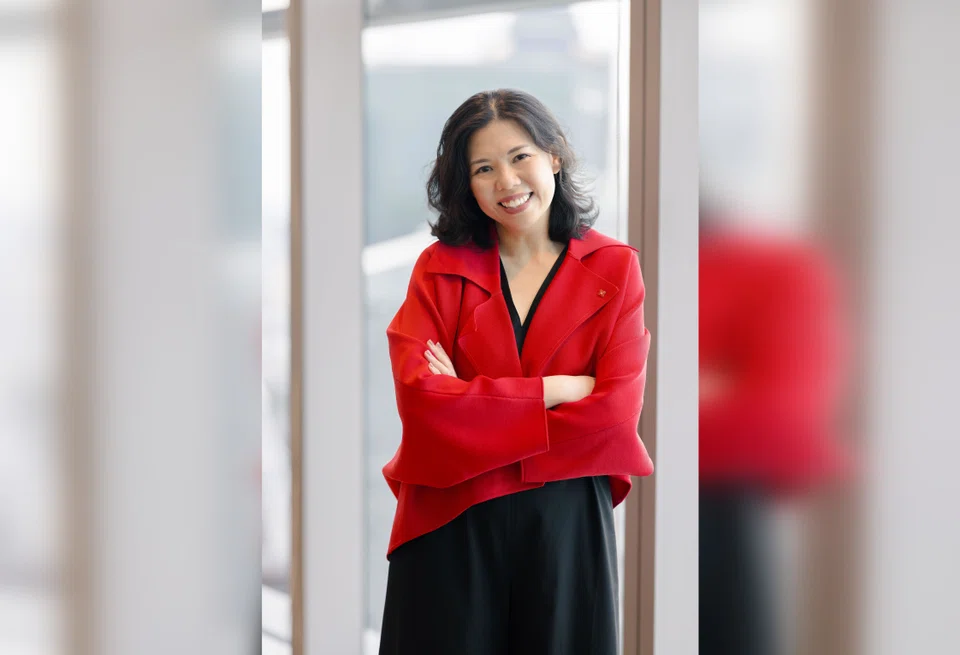
“Most people understand that starting early and investing consistently can make a difference to long-term wealth, but awareness does not always translate into action,” says Jamie Lee, head of DBS digiWealth. “digiWealth has prioritised helping customers overcome inertia by making the first step simple and structured, helping them invest with a clear purpose, then turning that first step into a sustained habit.”
The platform reflects DBS’s longstanding commitment to making holistic wealth management accessible to everyone, and to helping people across income levels and life stages build financial resilience as they work towards their life goals. More than 1.5 million users now actively manage their wealth through digiWealth.
Since mid-August, a generative artificial intelligence (GenAI) assistant has also been on hand to answer customers’ wealth-related questions.
Starting with the customer’s intent
With a growing universe of products to choose from today, it can be hard to figure out where to begin. digiWealth offers access to more than 700 funds, but customers do not have to work through them all to get started. For those seeking a clearer starting point, it highlights 17 investment solutions – the CIO Insights Funds – which were selected by experts in DBS’ chief investment office.

The journey begins with the customer instead of the product. digiWealth first asks customers to think about their investing intent and the source of funds they want to put to work, then shows them solutions relevant to those objectives.
Customers can also begin a regular savings plan (RSP) from as little as S$100 a month, with options that include DBS digiPortfolio, the bank’s range of managed portfolios designed for different investment goals.
DBS says this simpler, intent-led journey has led to more customers taking meaningful wealth-building action, with retail investment assets under management rising 32 per cent year on year as at September.
SEE ALSO
Protection is part of the same plan. digiWealth offers insurance alongside its investment solutions, so customers can close protection gaps as they build their wealth, on their own or with a human adviser’s guidance.
Learning at the right moment
To help customers make considered decisions and build better financial habits, digiWealth embeds financial literacy into the customer’s in-app journey. For instance, short contextual reminders appear in the app when they are relevant to a customer’s finances.
One reminder highlights Supplementary Retirement Scheme (SRS) funds that have been sitting idle, bringing an overlooked part of the customer’s retirement planning back into view. Others encourage customers to invest regularly through dollar-cost averaging, or to build up their emergency savings if they have yet to do so.
According to digiWealth, financial literacy content woven into the in-app journey and relevant to a customer’s context has a click-through rate of about 15 per cent. Generic financial literacy content, by comparison, averages under 1 per cent engagement. The willingness to click and learn more suggests that information tied to customers’ own needs is striking a chord.
Customers can also dismiss a reminder or set their notification preferences – keeping the prompts helpful rather than intrusive. “Being contextual should mean greater relevance to the customer, not more notifications,” Lee adds. Suppression controls limit how often prompts appear, while the bank regularly monitors dismissal rates. It also reviews customer feedback every quarter and runs regular immersion studies to find better ways to serve customers.
Answers in the customer’s own words
“What should I be doing today to prepare for retirement?”, “What types of insurance should I get first?” or “What can generate higher yield than T-bills?” – these are the kinds of questions customers can now bring to DBS digibot, the bank’s GenAI-enabled virtual assistant on digiWealth.
Asked in their own words, digibot offers a starting point for making sense of wealth-related topics. The emphasis is on understanding: making information less complex and helping customers see their options more clearly, so they can make more informed decisions. Available at any time of day, the assistant draws on a curated knowledge base of DBS content, including the bank’s financial literacy material, to offer clear, relevant answers and insights.
First launched in 2016, digibot is available to more than five million customers in Singapore. It resolved nine in 10 queries digitally in the first half of 2026.
Early take-up on digiWealth has been encouraging. In its first full month of launch, the assistant handled more than 4,500 queries, and 10 per cent of chats were followed by a transaction in the same month. DBS sees this as a sign that GenAI can support customers’ decisions by surfacing the right information when they need it.
Clear lines for AI
For DBS, AI is not an end in itself. The bank has been deliberate about where AI helps customers, where it should stop and where human advice remains essential, and those choices are built into how digibot works on digiWealth.
“Conversations with DBS digibot are meant to be educational. They help customers learn and understand, but do not provide investment advice and personalised recommendations,” says Lee. “Customers seeking such advice can speak to a WPM, who can help assess their objectives, financial situation and needs.”
That line holds when markets turn volatile. Instead of telling customers what to do with their holdings, digibot reinforces time-tested principles such as staying invested instead of trying to time the market. Customers who want advice on how to respond to market movements are directed to their WPM, who can help them weigh their goals, time horizon, liquidity needs and risk tolerance.
A human when it counts
Access to a dedicated wealth adviser, which has traditionally been reserved for wealthier clients, has since been extended to 3.8 million retail customers – or eight in 10 of DBS’ retail customer base. This is part of the bank’s years-long effort to make financial planning and wealth expertise available to many more people.
The number of customers who reached out to their WPMs proactively tripled year on year in the first quarter of 2026, while financial-planning inquiries through digiWealth rose fivefold year on year as at February, pointing to growing interest in planning ahead.
DBS describes its approach as “digital when you want, human when you need”. For everyday questions and simpler servicing needs, digital tools and AI offer quick help at the customer’s convenience. For bigger decisions or personalised advice, customers can arrange a call with their WPM through the app
The way Lee sees it, the two work best side by side.
“By having access to both, customers have the freedom to choose based on their personal context and preference, be it using digital tools to explore information and act at their convenience, or speaking to a WPM when they want personalised advice,” Lee says.
From first step to lasting habit
DBS wants that first step to become a habit that grows with the customer. “Our goal is to help customers form lasting habits, grow their wealth with confidence and build long-term financial resilience,” says Lee.
digiWealth is built to journey with customers through life. Someone in their 20s might begin with a S$100 monthly RSP, a young family may want to build emergency savings and protection first, and someone in their 50s may be focused on retirement. The DBS Retirement Portfolio follows that arc, holding more equities in an investor’s early years and gradually shifting towards bonds as retirement approaches. DBS’ WPMs advise customers as they move across these stages, from first-time investors to seniors planning for retirement and succession.
Buying protection has also become a starting point for long-term investing. Since the first quarter of 2025, a DBS partial-matching campaign has given customers who bought insurance coverage credits deposited directly into a DBS Retirement Portfolio – giving them an added reason to start building long-term wealth. More than 90 per cent have stayed invested; some have added further top-ups.
With more customers planning ahead, investing regularly and staying invested – the signs, so far, point to a positive shift in their financial habits.
What comes next
digiWealth rests on years of AI groundwork at DBS. In 2025 alone, it deployed more than 2,000 AI models across over 430 use cases; its data analytics and AI initiatives generated about S$1 billion in economic value that year. The work has earned recognition, including the Global Finance World’s Best AI Bank award in 2025 and the Euromoney Asia’s Best Digital Bank award in 2026.
“AI is not a new story for DBS, and our approach is not about chasing the latest hype,” says Lee. “It is about being intentional and applying technology purposefully to make banking simpler, more intuitive and more thoughtful.”
Agentic and voice AI capabilities are now in the pipeline for digibot. Beyond answering questions and providing guidance, the assistant will be able to handle selected banking and wealth servicing requests within the same conversation, on the customer’s instructions. These include checking card usage and transactions, tabulating card reward points, requesting fee waivers, and blocking or replacing cards.
Voice capabilities are also gradually being offered on DBS’s customer service hotlines, so customers can get everyday tasks – such as checking their card and rewards transactions – without waiting on the line. This means fewer steps to get everyday tasks done, with human support still close at hand whenever it is needed.
“While the tools continue to evolve, our purpose remains constant,” says Lee. “Wherever customers are starting from, our aim is to help them engage with their finances as their needs evolve, and work towards the life goals that matter to them.”
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services
TRENDING NOW

South-east Asia has lost Nvidia’s best salesman
‘If there’s a price to be paid, so be it’: George Yeo says Singapore must safeguard its reputation

Demand, tech capabilities position Apac and AI as Skyscanner’s next growth frontiers: CEO Bryan Batista
CapitaLand, Far East, Sing Holdings team up for S$1.8 billion bid at S$910 psf ppr for Jurong Lake District site

