

Geo Energy says it has enough funds to stay in coal mining, may acquire assets
Uma Devi
BANK funding may be turning scarce for coal companies, but Singapore-listed Geo Energy Resources said it has sufficient funds to continue in its coal mining operations. If asset prices come down, the company also has the resources to be an acquirer.
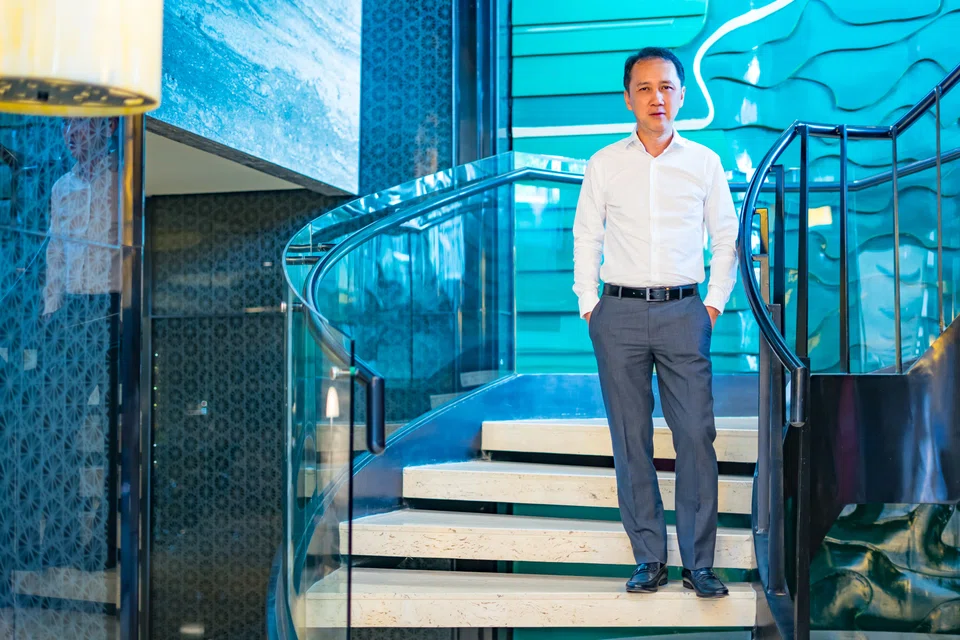
In a recent interview with The Business Times, chief executive Tung Kum Hon acknowledged that funding for the sector is “not easy” currently because banks are more cautious about funding projects in the coal space.
But Tung said Geo Energy is not in need of funding at the moment. In fact, he believes Geo Energy’s cash reserves, high liquidity and debt-free balance sheet put it in an advantageous position relative to its peers.
Tung’s comments come after competitor Golden Energy and Resources (Gear) announced its intention to restructure and exit the thermal coal industry. Gear intends to distribute to shareholders its stake in thermal coal company Golden Energy Mines.
The distribution in specie would “allow the group to reposition itself away from the energy coal industry, which is currently facing environmental, social and governance pressures, allowing the group to expand on its financing options, which would otherwise have been relatively limited if it were to be continuously exposed to the energy coal business”, Gear said in a Nov 9 statement.
Geo Energy, however, is preparing for the possibility of increasing, rather than reducing, its presence in the coal business.
Tung said Geo Energy’s financial position is healthy, with US$214.7 million in cash and bank balances as at end-September. This would come in useful for Geo Energy to make acquisitions “at the best pricing” when the valuations of coal assets come down, he said, adding that the company does not yet have any specific acquisition targets.
Even without making any acquisitions, Tung said Geo Energy’s 78 million tonnes in coal reserves are sufficient to keep the company busy for the next five to six years.
Geo Energy’s customers, meanwhile, are “international commodity traders with access to funding”, he added. And if existing customers should pull the plug on their agreements, Tung believes there are other buyers in the Indonesian coal market. For instance, he said Geo Energy could sell coal directly to power plants.
For the third quarter ended September, Geo Energy reported a 7 per cent increase in revenue – to US$164.7 million – on the back of higher average selling prices.
But margins were crimped by higher fuel costs as well as a higher ratio of wastage in the mining process. Earnings fell 21.5 per cent to US$35.7 million.
Coal prices are slated to ease gradually in the quarters ahead, but Tung remains optimistic that Geo Energy will continue to generate profits. He said that even if coal prices were to fall to US$28 per tonne, the group would still have a 20 to 30 per cent margin.
Tung said the financing pivot to renewables should not be “over-emphasised”, and that more attention should be paid to the returns on investment and technology required instead. The capital expenditure required for wind farms, for instance, can be huge.
The coal sector, while plagued with challenges, will remain viable in the near-term, he said, adding that there are opportunities for companies in this space as coal prices remain at elevated levels.
TRENDING NOW

Ex-Goldman trader builds mini pod shop in Singapore with offbeat hires

US says China to buy 10 million tonnes of coal in 2027 and 2028

Amberwood at Holland sells 23 of 70 units launched at average price of S$3,019 psf

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

