

GLP's Q1 net profit falls 24%
This is due to unrealised forex losses, lower revaluations on fund management business; core earnings are up 7%
Singapore
GLOBAL Logistic Properties (GLP) on Friday reported that its net profit for the fiscal first quarter to June 2016 fell 24.3 per cent to US$202.9 million.
This was due to US$36 million of foreign exchange losses over the yen and yuan, but it stressed that most of this was actually unrealised accounting losses resulting from marking inter-company forex loans to market.
The fund manager and developer of logistics facilities was also affected by lower revaluations (a difference of about US$47 million), mostly on its fund management business in its joint venture funds.
Revenue grew 8.6 per cent to US$206.6 million due to the completion of its development projects in China, higher rents and management fee income from the inclusion of GLP US Income Partners II, as well as the growth in development activities in Japan.
Core earnings, which adjust for non-recurring items, however, were up 7 per cent at about US$146 million.
GLP has a property portfolio of 52 million square metres of logistic facilities across China, Japan, the United States and Brazil.
Its core business is in developing and leasing modern warehouse space, but it also has a "self-funding model" - a fund management platform - that allows it to grow its asset base without being too dependent on outside capital. Capital unlocked from selling its properties to its own funds can thus be redeployed to more development projects.
OCBC Investment Research analyst Eli Lee said GLP's success in growing its fund management business has been "quite impressive". This contributed US$42 million in income in the latest quarter - up 17 per cent year-on- year (y-o-y).
"We see the group's fund management business as a valuable source of recurring income and more importantly, given the group's operating scale, expertise and reputation in its asset class, we believe there is significant scope for meaningful long-term growth for the platform ahead," he said.
There has been some concern in China over oversupply of logistic space in smaller markets. This led GLP's lease ratio in China to dip to 86 per cent in Q1, down from 87 per cent last quarter. But core earnings from its China business still grew 22 per cent, and same-property net operating income also grew 16 per cent y-o-y.
GLP said its China operations are expected to remain stable in the near term, supported by drivers such as e-commerce and the proliferation of organised retail.
The latter usually refers to chain stores, owned or franchised by a central entity, as opposed to independents and "mom-and-pop stores". Organised retail still makes up a very small portion of total retail sales in China, with much room for growth.
GLP added that the excess supply in the weaker sub-markets is also expected to be absorbed over the next 12 to 18 months.
Mr Lee of OCBC said: "Despite GLP highlighting over-supply from competitors in some Chinese markets, we like that management is taking on these challenges gamely with a disciplined approach - by focusing development starts only in markets with firm demand - and leveraging on its strategic relationships with major tenant networks.
"We remain constructive on the long term outlook for its Chinese business given the secular trends of growing domestic consumption and demand for modern logistic facilities."
He has a "buy" rating on GLP with a fair value estimate of S$2.37. The stock closed two cents lower at S$1.93 on Friday.
On the fund management side, GLP's platform has now US$12 billion of uncalled capital, which can generate additional fund management fees.
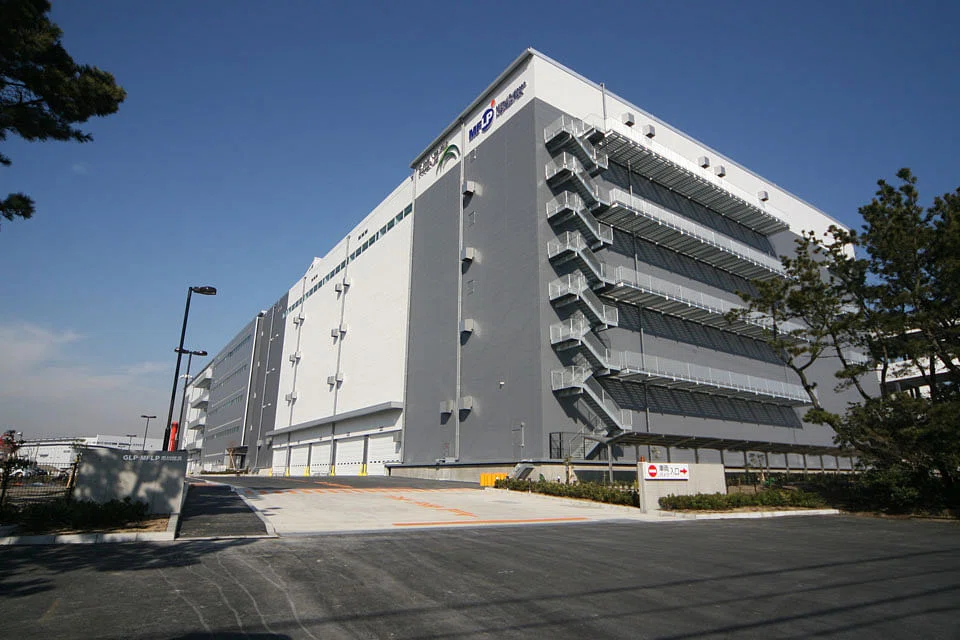
GLP has also recently announced the sale of its 50 per cent share of GLP-MFLP Ichikawa Shiohama to GLP J-Reit for about US$151 million. This crystallises US$48 million of development profit for GLP, with a 46 per cent development profit margin.
The company also revealed that including the 52 million shares it repurchased in Q1, GLP has bought back some 169 million shares (or 3.5 per cent of its outstanding shares) since Aug 4, 2015, at an average of S$2.05 per share.
In a note to clients, Tata Goeyardi, Religare's director of Asean sales, said that the share price has been trading at a range of S$1.80 to S$2, supported by such company share buybacks.
"We think the stock could likely remain in this trading band unless we see a bigger catalyst such as a divestment of China's stabilised business," he said.






