Gold rush could herald boom for mining stocks, but analysts warn it’s not all glitter
Industry watchers point out that mining operations of any metal reserves can be susceptible to weather disruptions and power outages
[SINGAPORE] Gold prices are continuing to notch new highs amid geopolitical risks and economic uncertainties. But analysts warn that investors turning to mining stocks to capitalise on the gold rush should tread with caution.
After all, all that glitters is not gold, and these mining companies could have very different growth prospects.
Among the 10 most traded resources stocks on the Singapore Exchange (SGX) this year, only two – CNMC Goldmine and Wilton Resources – are gold mining companies. Both are listed on the Catalist board.
CNMC Goldmine focuses on gold exploration, mining and processing, with its flagship Sokor Gold Project in Kelantan, Malaysia. Spanning 10 sq km, it is estimated to yield some 918,000 ounces of gold.
CNMC Goldmine generated a total return of 25.6 per cent in 2024 – broadly in line with the 26 per cent rise in gold prices in the year.
Lim & Tan Securities in February initiated coverage on the counter with a “buy” recommendation and a target price of S$0.43.
CNMC Goldmine closed at S$0.31 on Monday (Mar 10), giving it a market capitalisation of about S$121.6 million.
The counter is trading at about 9.6 times its latest earnings – compared to its peers’ average price-to-earnings of about 22 times – with a dividend yield of 2 per cent.
“We view CNMC as a laggard play where its share price does not fully reflect the upside from rising commodity prices,” said Lim & Tan Securities analyst Chan En Jie, noting that its price-to-earnings ratio, yield and growth prospect render it “an attractive stock to dive into at current levels”.
The company is also “going full steam ahead to ramp up production” at its Sokor Gold Field to capitalise on rising gold prices, Chan said.
As its flagship gold mine also contains other metals, the company has diversified into exporting lead and zinc concentrates since 2023, adding to its revenue stream.
In CNMC Goldmine’s latest financials released on Feb 24, net profit for the full year ended December 2024 was up more than 140 per cent on the year to US$9.8 million – its best performance since FY2015.
This was bolstered by higher gold prices and increased sales of lead and zinc concentrates.
Susceptible to operation disruptions
However, industry watchers pointed out that mining operations of any metal reserves can be susceptible to weather disruptions and power outages.
As the sector is asset-heavy with high capital expenditure, managing operating costs amid potential disruptions is a key to sustainable business development, they added.
SGX-listed Indonesian gold miner Wilton Resources, for example, has been weighed down by mounting operating expenses.
For the nine months ended Sep 30, 2024, Wilton Resources’ net loss widened to 46.7 billion rupiah (S$3.8 million), from 14.7 billion rupiah in the year-ago period, as operating expenses nearly trebled. The company has not yet announced its full-year results for FY2024.
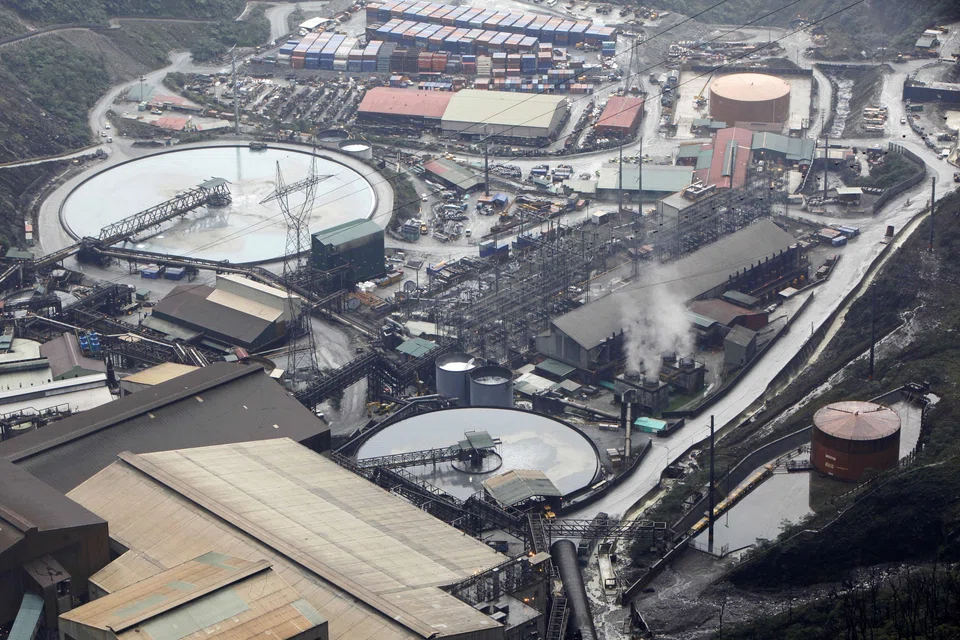
In an operational update in December, Wilton Resources said its Ciemas Gold Project has been severely affected by a power outage caused by heavy rainfall, with the La Nina event expected to last till April 2025.
The group’s gold mining project in West Java, Indonesia, spanning a total of 30.8 sq km, is estimated to contain 4.4 million ounces of gold.
Shares of Wilton Resources closed at S$0.005 on Monday, giving it a market cap of S$13.1 million. In the year to date, the counter is down about 50 per cent.
In 2024, Wilton Resources generated a total return of negative 68.2 per cent, in spite of higher gold prices.
“The (company’s) ability to control costs is also a major swing factor for stock prices,” said Steve Land, a vice-president and research analyst with Franklin Templeton’s equity group.
“Investors remain sensitive to the fact that higher costs reduce the cash generation of the business, so companies need to provide solid guidance and deliver on expectations,” added Land, who is also the lead portfolio manager of the Franklin Gold and Precious Metals Fund.
Mining for opportunities beyond Singapore
Elsewhere in Asia-Pacific, bigger players in major gold producing countries such as Australia, China and Indonesia – especially those with competent cash flow and cost management – have also been riding on the gold price surge.
Names that stood out for analysts include Hong Kong and Shanghai-listed Zijin Mining.
For FY24 ended December 2024, Zijin Mining logged a record year for profits, as net income rose 52 per cent to 32 billion yuan (S$5.9 billion) on a ramp-up in copper output and record-high gold prices.
The Chinese mining group’s market capitalisation has been roughly on a par with global commodities giant Glencore since last October.
The total return of its Shanghai counter stood at 23.6 per cent in 2024, when its Hong Kong counter achieved 14.2 per cent return.
Macquarie’s equity research team has an “outperform” call on the company, on the back of its volume growth potential, cost leadership and strong mining assets portfolio.
DBS analyst Lee Eun Young also likes Zijin Mining for its mining activity expansion. “Zijin Mining is ranked fifth in terms of copper reserves and output, and sixth and seventh for gold reserves and output globally in 2023,” noted Lee.
The research house has a target price of HK$24.50 on Zijin Mining, which closed at HK$16.14 in Hong Kong on Monday. The counter was up 13.8 per cent year to date.
Lee expects Zijin Mining, which has been expanding its copper and gold reserves via mergers and acquisitions, to grow its earnings at a compound annual growth rate (CAGR) of 24 per cent between 2023 and 2026.
He noted that the company’s earnings had grown at a CAGR of 26 per cent in the past 10 years.
Analysts added that Australian giants such as Newcrest Mining, Northern Star Resources and Evolution Mining, which have operations beyond Australia, also present buying opportunities.
However, despite the gold rally, analysts warned that investors should not rush headlong into mining stocks.
“Retail investors should look at enhancing their portfolio with exposure to the mining sector via mutual funds managed by experienced professionals who use a research-driven approach to identify high-quality companies,” said Franklin’s Land.