

Golden Energy shares have trebled this year, but potential buyout hints they are still undervalued
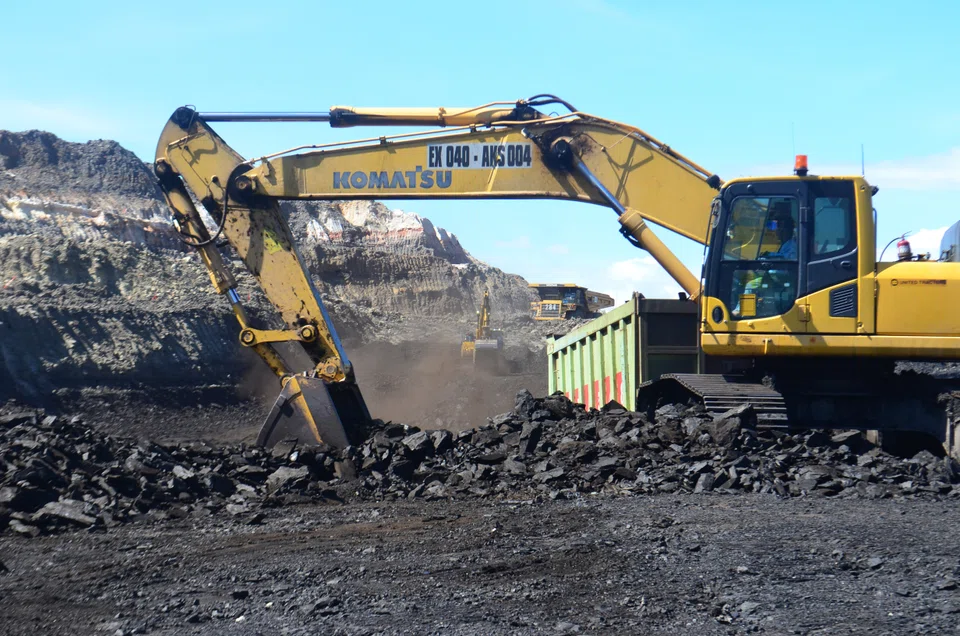
FIVE months since a key Australian subsidiary of Golden Energy and Resources (Gear) completed what it deemed a “transformational” acquisition of metallurgical coal assets Down Under, the Singapore-listed miner may be set for another deal – as the target of the Widjaja family of Indonesia’s Sinar Mas empire.
On Monday (Oct 10), Gear, which owns one of Indonesia’s largest coal miners – Golden Energy Mines – revealed that it was in talks with certain shareholders, including Indra Widjaja, on a “possible acquisition” of the company. No concrete outcome or definitive agreement has emerged from the discussions.
One factor that may have prompted this latest consideration, say observers, is that Gear is undervalued. On Monday, Gear’s stock hit a high of S$0.935 on the back of the news. It closed at S$0.905, up nearly 8 per cent from last Friday’s finish. It was hovering at the same level on Tuesday.
Joey Choy, a remisier at Phillip Securities, said more upside could await. “Technically, from the chart, it broke the key S$0.85 resistance on Monday with more buying momentum returned. Target can be revised higher to S$1, where some profit taking could set in,” he said.
Based on Jitta, an investing-solution website that provides the fair price of a stock, the intrinsic value of Gear’s stock is at about S$2. The site says Gear is trading below the “Jitta line”, meaning the counter is undervalued.
Widjaja and two of his siblings are Gear’s controlling shareholders, with a 77.5 per cent stake as at Mar 15, 2022. The public float of some 22.5 per cent, based on current market capitalisation of S$2.4 billion, is worth some S$540 million.
Gear’s consolidated earnings before interest, taxes, depreciation, and amortisation stood at US$503.3 million for FY2021. But one observer noted that the company may now be more leveraged, following its Australian subsidiary Stanmore Resources’ 80 per cent buyout of BHP Mitsui Coal (now called Stanmore SMC) from BHP Minerals for US$1.2 billion cash.
As at end-June 2022, the group’s total debt stood at US$1.6 billion. This included a US$625 million loan to fund the SMC acquisition.
“With interest rates on the rise, there may be a need for Gear to free up or restructure part of the debt,” said another observer.
The SMC acquisition was completed in May. A week ago, Gear announced that Stanmore had scooped up the remaining 20 per cent stake in SMC. The latter owns metallurgical coal assets – an essential input in steel production – in Queensland, Australia.
Gear’s shares have trebled this year, as investors zeroed in on energy and coal plays amid the Russia-Ukraine war that has sent commodity prices up amid the tightest market conditions.
Since August, the European Union (EU) has banned imports of Russian coal as part of a sanctions package. This has, in turn, pushed coal prices higher.
“The longer the Russian sanctions remain, the longer the supply in the market will remain constricted,” said Phillip’s Choy, adding: “However, nobody can predict how long the sanctions are going to remain in place.”
As European wholesale gas prices hit the roof amid an unprecedented energy crunch, a so-called gas-to-coal switch is taking place and creating more demand for “dirty fuel” – another factor that has led to elevated coal prices. But downside headwinds are also gathering quickly, chiefly recession fears, which could hurt demand for coal.
Dividends have been elusive for Gear shareholders over the last two years, despite the company reporting record FY2021 earnings and revenue.
For the first half ended June 2022, the company earned a net profit of US$279 million – up 859 per cent from a year ago – as revenue trebled to US$2.4 billion.
Higher average selling prices for energy and metallurgical coal plus the first two months’ contribution by SMC sweetened the company’s report card. And given SMC’s cash flows are set to be fully reflected in the coming period, Gear’s prospects for the second half look rosier.
TRENDING NOW

Ex-Goldman trader builds mini pod shop in Singapore with offbeat hires

US says China to buy 10 million tonnes of coal in 2027 and 2028

Amberwood at Holland sells 23 of 70 units launched at average price of S$3,019 psf

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

