

Grab's share price slide a reminder of risks in any de-SPAC
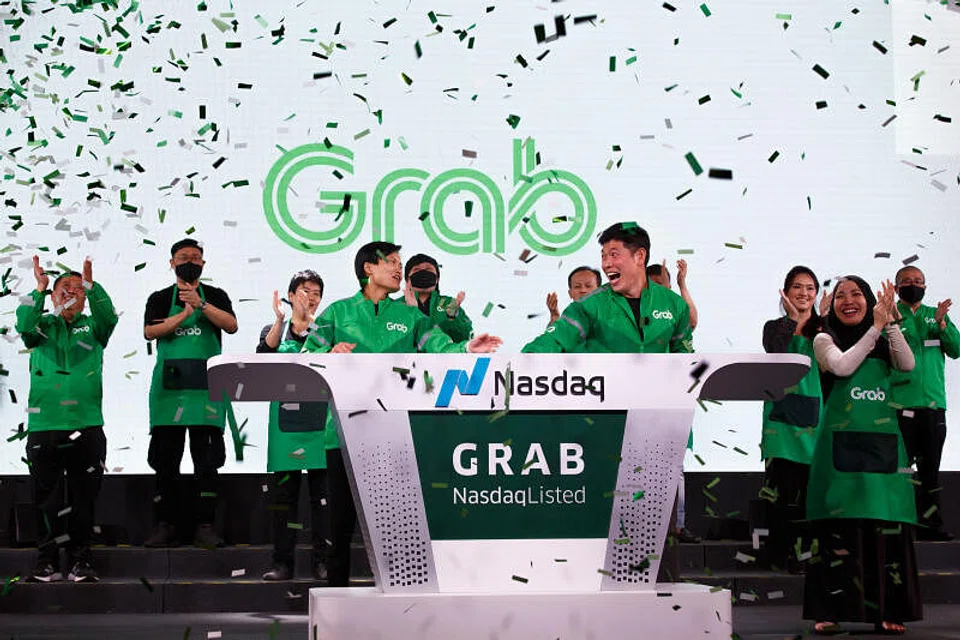
SOUTH-EAST Asia ride hailing and delivery services provider Grab made its trading debut on the Nasdaq last week via a merger with Altimeter Growth Corp, the largest special purpose acquisition company (SPAC) transaction to date.
The much-anticipated listing of one of the most valuable regional startups was met with initial exuberance from investors as trading began, but the shares closed at US$8.75 on the first day of trading, down 20.5 per cent from the US$11.01 closing price a day earlier when it was trading as Altimeter.
The SPAC had closed as high as US$17.06 just 3 weeks before the merger with Grab, and the counter had never gone below the crucial US$10 threshold since its initial public offering (IPO).
It would, obviously, be premature to judge the performance of a stock based simply on its first few days of trading. But it would also be useful for investors to note that the trend of SPACs falling post-business combination is not unusual.
With the first SPACs coming to the Singapore market, it is a timely reminder for investors to familiarise themselves with the nature of these blank-cheque companies, and consider whether the risks post-business combination - also known as a de-SPAC - suits their investment profile and objectives.
Recap
To recap, SPACs are shell companies that are listed for the purpose of acquiring a private company and taking the latter public in the process - similar to a reverse takeover.
They typically list in the US at a price of US$10 per unit - comprising a share and part of a warrant. Most of the IPO proceeds are placed in a trust while an acquisition is being sought.
SPAC sponsors have a fixed timeline to seek an appropriate target company to merge with. As compensation, sponsors would usually receive 20 per cent of the SPAC shares for a nominal sum, known as the promote.
Investors can then vote on whether the business combination should proceed, and they also have the right to redeem their pro-rata share of the trust if deals are not to their liking. Those who do not redeem will become shareholders in the combined entity.
According to data from website Spac Track as at Monday (Dec 6), around three-quarters of the over 170 completed SPACs in 2021 are currently trading below their US$10 IPO price, with the average share price down 13.3 per cent.
A European Corporate Governance Institute (ECGI) working paper by Michael Klausner, Michael Ohlrogge and Emily Ruan last month - which studied 47 SPACs that merged between January 2019 and June 2020 - found that the median return 1 year after merger was negative 19.3 per cent, even though the mean return was positive at 19.1 per cent.
When considering the SPACs' excess performance against benchmark returns of the Nasdaq Composite and Russell 2000, mean and median returns were both negative.
Some of the reasons cited for the poor performance include the dilutive structure of SPACs and weak incentives of sponsors and management.
Alignment of interest
In the case of Grab, the business combination appeared to tick many of the right boxes.
The target company is a large well-known business with significant regional presence and opportunities to tap growing market segments.
Altimeter's sponsor also was not relying on its founder promote alone for returns. Funds managed by its affiliates had committed some US$750 million to the PIPE (private investment in public equity), demonstrating skin in the game. And it also had long-term alignment of interest, with a 3-year lock-up for the promote shares.
The transaction included a large PIPE of US$4 billion - far larger than the SPAC's US$500 million IPO proceeds - with large institutional funds participating.
The ECGI paper noted that a large PIPE in relation to a SPAC's IPO can dramatically reduce costs as a percentage of net cash SPACs deliver, and it cited Altimeter's SPAC as an "encouraging example".
Investors had also seemed relatively comfortable with the transaction, and Altimeter's share price also spiked higher in the month prior to the business combination, with a volume-weighted average price of US$13.23 in November. Unsurprisingly, there were almost no redemptions.
By contrast, it is worth noting that there are other SPACs where nearly all of the capital invested at IPO was redeemed. A recent example is 890 5th Avenue Partners, which announced the closing of its business combination with media company BuzzFeed last week.
Investors voted in favour of the transaction but acted differently with their wallets. Capital redemptions left the SPAC with just US$16 million in trust proceeds, down from US$288 million when the merger was announced.
Valuations
Even with the positive attributes leading to Grab's de-SPAC transaction, the counter still fell sharply after trading began. This may partly be due to valuation.
When the proposed merger was first announced in April, analysts and market watchers had questioned Grab's US$39.6 billion equity valuation. They noted that Grab is still unprofitable, with several large competitors in the region. For the third quarter ended September, revenue fell 9 per cent year on year to US$157 million, while net loss widened 59 per cent to US$988 million.
SPACs have been lauded by market participants for providing certainty on valuation and execution for high-growth companies wanting to list, but these valuations are akin to private deals. They are untested against the force of the full market, even though a PIPE round may have given some validation.
Investors should also note that there is an element of downside protection before the de-SPAC, as there is the option to redeem capital from the trust, setting a notional price floor.
The lifting of any downside protection could weigh on the shares subsequently, and a Wall Street Journal report has also suggested that there had been strong short-selling interest.
Regular employees or other existing shareholders who are not subject to any lock-up may have also been sellers on opening day, in view of the fresh liquidity for their shares.
This column is not suggesting that Grab's share price trends in its opening few trading days would be reflective of its future prospects. The valuation of any new economy player is subject to many considerations including its latest plans and the current market conditions.
If much of the current decline is indeed due to Grab shares being shorted, things could also reverse down the road if sentiments improve and the shorts get squeezed.
Think of the risks
What is more important for investors, however, is to understand the nature of SPACs and how the risk changes significantly during its life cycle. A relatively low-risk and stable investment in the first part of a SPAC's life can have a totally different risk profile the moment the combined entity starts trading.
Alignment of interest from sponsors, and structuring that result in minimum dilution are arguably a prerequisite if you wish to hold through any SPAC business combination. But beyond that, fundamentals are also critical.
Investors must assess how comfortable they are with buying a stock at a certain valuation, and consider whether the broader market is likely to affirm or punish such valuations once the notional price floor is removed.
As the first Singapore SPACs approach, local investors should look at the lessons overseas and consider the various factors at play when considering the risks and opportunities.
For investors who are less certain on the prospects of a target company, or are uncomfortable with the valuations, a lower risk strategy would be to sell the SPAC shares, or redeem them, and retain the initial capital. Those who bought the units at IPO can still retain their warrants and these can provide an upside if the SPAC eventually outperforms.
Of course, too many redemptions may result in failed SPACs. As an investor, however, this may still be better than holding through a de-SPAC only to see your investment plunge shortly after.
TRENDING NOW

Green fuels, autonomous ships: How Singapore is future-proofing its shipping industry

US trade chief to consider trade deal tariff caps in excess capacity probe

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Deal between tycoon friends sparks scrutiny of Philippine power sector

