

Higher operating costs are a stone in the shoe – even for the rich eyeing family offices
These ultra-high-net-worth investors are turning to banks which offer alternative ways of managing their wealth
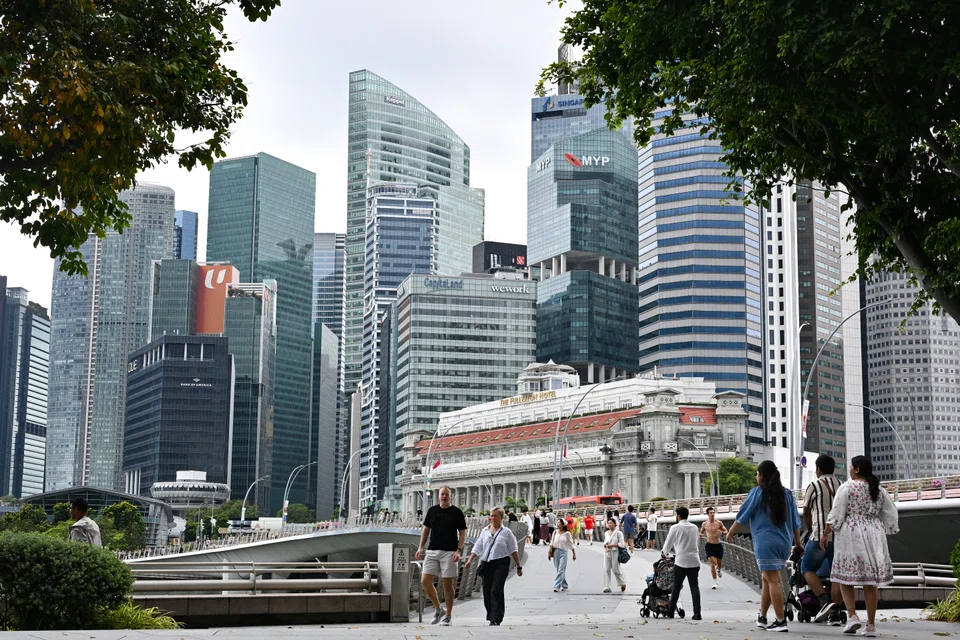
[SINGAPORE] The compliance costs incurred when setting up single-family offices (SFOs) in Singapore are nudging the ultra-rich towards considering the more cost-effective alternatives offered by private banks.
Those that choose to go with these banks’ services are essentially getting the banks to manage their wealth. The payoff is that these ultra-high-net-worth individuals (UHNWIs) enjoy the tax perks of setting up SFOs without having to do so.
Observers say, however, that although having the option of another route is a positive thing for these ultra-rich families, the downsides are the possible lack of customisation that comes with having the financial and personal affairs of the one family managed by a dedicated private organisation. The potential conflicts of interest are another downside.
Also, although the initial set-up by a bank may be faster and less costly, there would still be recurring platform fees going forward.
Market players tell The Business Times that the costs of establishing and running SFOs in Singapore have risen since the authorities started tightening regulations in 2023, following a high-profile money-laundering case that involved S$3 billion in assets.
These tighter rules include mandating that SFOs have a bank account with a financial institution regulated in Singapore. The Monetary Authority of Singapore (MAS) also introduced broader due-diligence checks on SFOs applying for tax incentives.
Ben Charoenwong, an associate professor of finance at Insead, said: “MAS’ new framework requires mandatory banking relationships for anti-money laundering/know-your-customer compliance, adding another layer of costs. These include both financial and non-financial costs, like the additional associated delays in opening bank accounts.”
In the aftermath of the money-laundering case, the processing time for applications for MAS’ tax incentive scheme reportedly stretched beyond three months, as financial institutions stepped up their onboarding procedures.
In a framework to be rolled out, MAS laid out criteria for SFOs seeking licensing exemptions; it also introduced new notification and reporting requirements. SFOs looking to apply for tax incentives would also have to deal with requirements for fund size, spending and staffing.
Faster set-up, lower costs
Private-banking products that enable UHNWIs to enjoy tax exemptions available to SFOs “offer wealthy families a cost-effective alternative to establishing their own SFOs by providing access to banking expertise and tax advantages aligned with MAS’ incentives”, said Kenneth Goh, associate professor of strategy and entrepreneurship (education) at the Singapore Management University (SMU).
The faster set-up and lower costs afforded by such products could become that “intermediate step” that a UHNWI takes on the road to eventually setting up an SFO, he added.
Staffing is another challenge for SFOs in Singapore. SFOs looking to apply for tax incentives must recruit a minimum of two professionals, at least one of whom must be from outside the owner’s family. (See *Amendment note)
Even so, market players say the fierce competition for talent means there aren’t enough investment professionals to meet the demand from family offices in Singapore. Prof Charoenwong said the “acute” talent challenge for SFOs is sharpened by the inability or the refusal to pay competitive salaries.
The professionals they recruit from private banks are typically relationship managers, instead of investment managers. “This creates hidden costs as families must hire consultants for actual investment expertise, portfolio construction and risk management,” he said.
Another sticking point is the slow rate of technology adoption among some SFOs, “specifically in Singapore”, said Silvio Struebi, partner and head of banking for the Asia-Pacific at consultancy Simon-Kucher.
“Often, sponsors or (the) family office manager combine fragmented solutions and outsource piecemeal, which may appear cost-efficient at first glance, but creates significantly higher risks and higher costs in terms of integration further down the road.”
SFO alternatives
Bank of Singapore (BOS) was the latest to offer its services to the ultra-rich. On Aug 18, it launched a new option for those with a net worth of at least US$250 million as an alternative to setting up SFOs.
Called the Family Office Catalyst, BOS’ solution requires an investment vehicle with at least US$20 million in assets under management (AUM).
In 2023, DBS Private Bank launched the DBS Multi-Family Office (MFO) Foundry VCC. The service was lauded as the world’s first bank-backed multifamily office solution that leverages Singapore’s variable capital company (VCC) structure.
A corporate structure designed to house investment funds for a wide range of assets, VCCs are a popular vehicle among some family offices. They allow for segregated funds to be created, where assets can be pooled for private investments; individual sub-funds can also be managed on behalf of each client.
Since its launch, DBS Private Bank has onboarded more than 25 clients, said Lee Woon Shiu, group head of wealth planning, family office and insurance solutions.
“I’ve personally spoken to many of them, who value the convenience and institutional credibility of our DBS MFO VCC. They describe it as a ‘plug-and-play proposition’ that allows them to move quickly without compromising governance or long-term planning.”
To appeal to families that are not seeking to relocate immediately to Singapore but would like to consolidate their assets in the city-state, DBS is keeping the entry point “accessible” – at S$15 million.
UOB Private Bank also offers SFOs, MFOs and VCC structures, on top of a variety of solutions for its UHNW clients who qualify for tax exemptions for their investments managed in Singapore, said Angela Koh, its head of wealth planning and family office advisory services.
Outsourcing chief investment officer
UHNWIs with at least 250 million Swiss francs (S$401 million) in bankable assets can tap the outsourced chief investment officer solutions and discretionary management at Julius Baer.
Prof Charoenwong said private banks “are motivated to offer these structures because they make clients sticky and less likely to take their funds elsewhere, representing more opportunities for revenue and product distribution”.
Private banks are launching these products also because they are “feeling the heat” from MFOs, said Traveen Gulrajani, founder and chief investment officer at Plutus Partners, an SFO with US$280 million in AUM. If SFOs have their papers in order and know how to negotiate with their service vendors, they can keep a lid on costs, he added.
However, experts do warn that UHNWIs relying on such banking services instead of setting up their SFOs will face several drawbacks.
Limited customisation is one. Within predetermined investment philosophies, potential conflicts of interest could favour the bank’s products over the family’s needs. Banks’ services could also be less culturally sensitive in legacy planning than dedicated SFOs.
“Long-term platform fees may eventually exceed SFO costs, and families face a reputational risk if their bank encounters compliance issues,” said Prof Goh, who is also academic director of the Business Families Institute at SMU.
Operating on an open-architecture basis such as at Julius Baer “helps reduce potential conflicts of interest and maximises flexibility”, said Christos Anagnostopoulos, head of family office solutions/advisory for Asia at the Swiss private bank. This means that clients can access external managers, providers, strategies and structures globally.
Another way for ultra-rich families to manage their risk is for them to spread their wealth across several institutions, “so no single bank has the full picture”, he said. “Considering risk, this strategy is wise, as defaults can occur even among reputable institutions like global private banks.”
Ultimately, UHNWIs and their families need to assess whether the savings in cost and time spent from using such banking services outweigh the drawbacks.
*Amendment note: The article has been updated to clarify that the number of employees that SFOs hire depends on the tax incentive scheme, instead of the amount of designated investments as stated in a previous version.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

US says China to buy 10 million tonnes of coal in 2027 and 2028

Tokyo reverses baby bust with AI matchmaking and generous subsidies

