Higher palm oil prices lift revenues of locally listed planters and refiners
Smaller, pure-play stocks - such as Bumitama Agri and Mewah International - post better top and bottom lines than large ones
Singapore
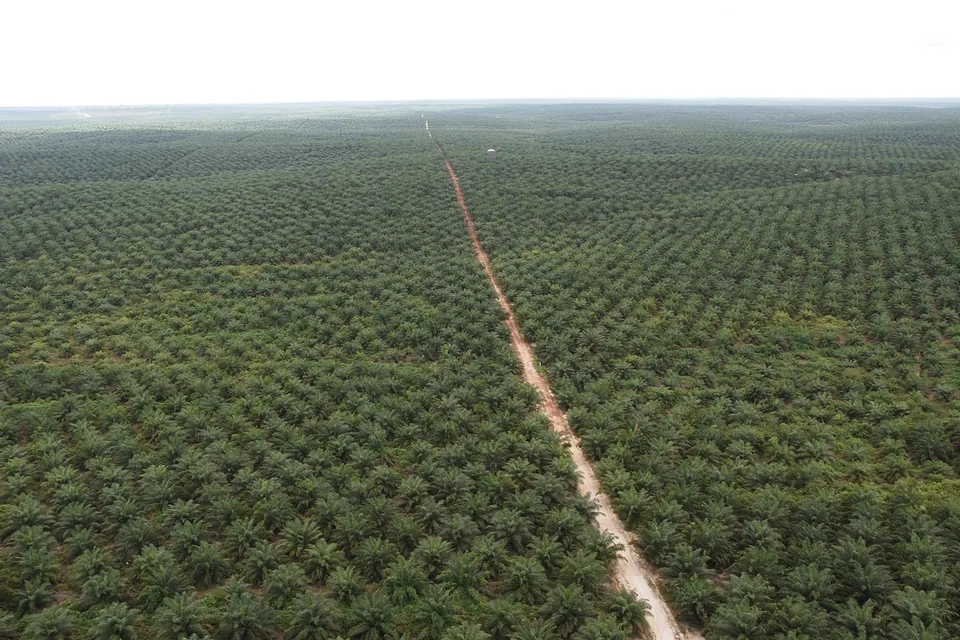
THE recent spike in crude palm oil (CPO) prices has helped lift the top and bottom lines of CPO plays listed on the Singapore bourse. The effects, however, have not been universal. It is the smaller, pure-play counters - such as Bumitama Agri and Mewah International - that have come out tops.
Their share price performances, however, have not necessarily matched their improved financial performances - suggesting some upside for investors. Nirgunan Tiruchelvam, head of consumer sector equity research at Tellimer, said there is "tremendous diversity and divergence" in the average selling prices of each palm oil company as each firm adopts its own "hedge strategy".
The divergence is then reflected in the company's financial results, he explained. Other possibilities include different production levels across companies due to sizes of plantations or amounts of fertilisers used, he added.
Amid a supply crunch and strong demand from importing countries such as India and China, CPO prices have been on a steady upward trajectory for several months. From a low of RM2,163 (S$710) per tonne on May 4, 2020, CPO futures climbed steadily to finish last year at RM3,365. In 2021, prices rallied further to hit their highest level since 2011.
Thanks to the higher prices, all the CPO planters and refiners saw an increase in their revenues last year.
The higher CPO prices also helped Indofood Agri Resources and Kencana Agri return to the black for FY2020 ended December 2020. Indofood reported a profit of 19.9 billion rupiah (S$1.84 million), against a loss of 411.4 billion rupiah in FY2019. Over the same period, Kencana reported a profit of US$4.0 million, against a loss of US$12.8 million.
Global Palm Resources, meanwhile, saw its losses narrow from 38.51 billion rupiah in FY2019 to 7.68 billion rupiah at the end of FY2020.
The biggest gainers in terms of profit increases were Mewah International and Bumitama Agri.
Mewah's profits for FY2020 ended December were US$86.5 million, versus a profit of US$11.6 million in FY2019. Bumitama Agri posted a 64.1 per cent increase in net profit in FY2020 to 1.13 trillion rupiah.
Other companies, however, were not as lucky. One reason for the rise in prices last year was poor weather conditions.
Indonesian CPO players were also affected by increases in export levies.
First Resources was among those hurt by the export levies. It also faced challenges in terms of production volumes and yields which more than offset any benefits from higher CPO prices. The company posted a more modest 11.8 per cent increase in net profit for FY2020 to US$99.7 million.
Typically, oil palm plantations record better productivity in wetter weather. The drier weather in 2020 meant fewer fresh fruit bunches (FFBs) could be harvested, which in turn caused declines in production volumes.
In FY2020, First Resources' CPO yield declined to 3.8 tonnes per hectare from 3.9 tonnes per hectare in the year before. The volume of harvested FFBs fell 2.6 per cent over the same period.
At least one analyst suggested caution following the release of First Resources' financial results. RHB downgraded its call on the stock from "buy" to "neutral" and lowered its target price as it warned that the company's more aggressive forward sales could have a "detrimental" effect on its earnings potential in 2021, with lower realised crude palm oil prices and higher applicable export levies.
"Aggressive forward sales have a double-whammy effect on earnings as the recognised average selling price is lower in a rising market and the export levy applicable is higher, as it is based on the rate applicable upon delivery," said RHB in its report.
First Resources was, however, the exception. In general, the smaller players appear to have performed better than the large ones. Golden Agri-Resources, for instance, reported a lower profit for the year, while Wilmar International's profit rose only moderately.
Golden Agri's net profit of US$31.8 million for FY2020 was 83.6 per cent lower than the year-ago period. Apart from a net loss of US$156.9 million in H1 FY2020 ended June, the company's palm oil product output also declined 5 per cent in the year.
The company's bottom line was negatively impacted by weaker volumes at its downstream business, due to lower availability of palm oil feedstock and supply chain disruptions caused by Covid-19.
Wilmar's profit rose 18.6 per cent to US$1.53 billion for FY2020, from US$1.29 billion in the year-ago period. As a diversified commodities play, Wilmar's exposure to CPO prices would have been significantly lower than that of some of its peers.
Looking ahead, RHB analysts are expecting CPO prices to stay "buoyant" for the first quarter this year due to the low output season, but warned that prices should moderate from the later part of the second quarter as productivity improves.