

Hong Leong Asia expects to benefit from ramp-up in HDB building activity in H2
The short to medium-term outlook for the company’s building materials segment remains robust
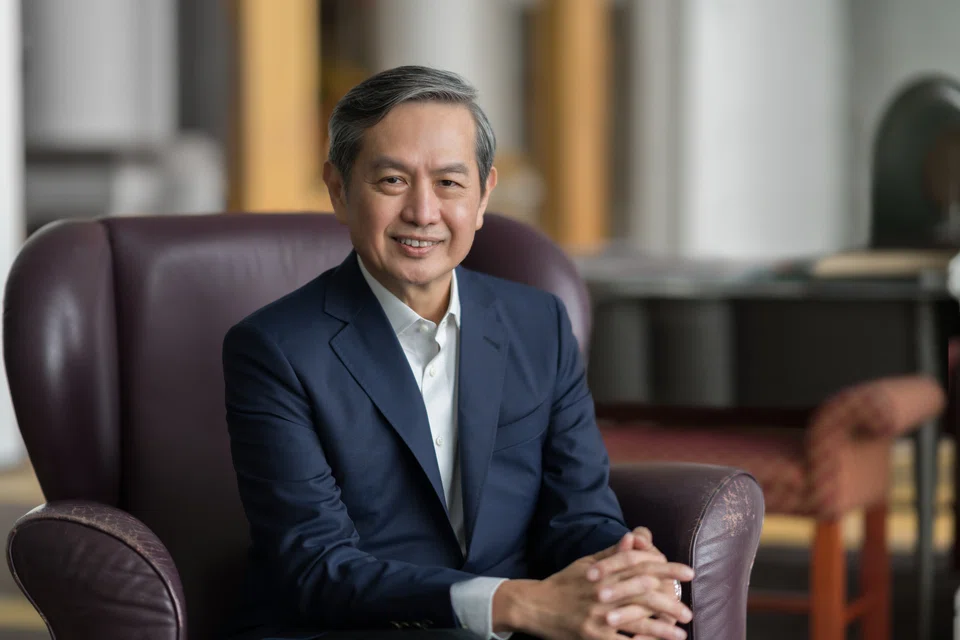
HONG Leong Asia saw a decline in revenue from its building materials segment in Singapore for the first half of this year. But the industrial conglomerate believes it will benefit from a ramp-up in public housing building activity in H2.
Revenue for building materials recognised in Singapore declined 4.4 per cent year on year (yoy) to S$195.3 million for the six months ended June, as the company’s prefabrication business was affected by “slow project offtake” in the industry.
At an earnings briefing on Wednesday (Aug 14), chief executive Stephen Ho said that because of the increase in Housing and Development Board launches in the last two years, external consultants engaged by HDB have not been able to submit the drawings for flats on time.
“Therefore, the approval process also could not be done on time, so there’s that knock-on effect all the way down to the contractor level, and for us as a building materials supplier,” he said.
Ho added that as the issues are being resolved, the company should see more normal levels of prefabrication offtake from H2 this year.
As demand increases, he is also confident that the company will be able to ramp up production to meet orders.
For instance, he said that the company could extend manufacturing at the its integrated construction and prefabrication hub in Punggol Barat Lane to 24 hours a day. He did not reveal the site’s utilisation rate.
Chief investment officer Patrick Yau said that the short to medium-term outlook for the company’s building materials segment remains robust as more HDB flats continue to be launched, with the launch for the next batch of flats in October this year.
As for the company’s powertrain solutions segment, Ho noted that while the industry moved 2.2 per cent more medium and heavy-duty engines, the company was able to grow its overall engine unit sales by 16.3 per cent. Revenue for the segment for the half year grew 9.3 per cent yoy to S$1.9 billion, while profit after tax grew 28.8 per cent to S$61.9 million for the same period.
He added that the company’s powertrain solutions unit, China Yuchai International, is one of the top five engine manufacturers and is likely a leader in the marine and genset space.
Furthermore, the company announced on Tuesday that MTU Yuchai Power Company, its 50:50 joint venture with Rolls-Royce’s power systems division, will move into a second phase of cooperation.
Under this phase, MTU Yuchai Power will extend the production and localisation of the MTU Series 4000 for both the power generation as well as oil and gas segments.
Ho estimates that while the company selling a couple of thousands of such generators to data centres and the oil and gas segments would be considered “high volume”, the average selling point of such generators will also be high.
He added that the Chinese government’s 300 billion yuan (S$55.2 billion) stimulus programme should be a net positive for the company’s powertrain segment, although the impact may be more indirect.
In July this year, China’s National Development and Reform Commission allocated 300 billion yuan in ultra-long treasury bonds to support a programme of equipment upgrades and consumer goods trade-ins, to spur economic recovery.
Ho said that while there may not be an immediate strong uplift in terms of asset renewal, the powertrain industry should benefit from an improvement in business confidence and consumer demand that could come from the stimulus package.
On Tuesday, the company posted a 60.1 per cent yoy rise in net profit from continuing operations to S$49.4 million for H1 of FY2024, as revenue climbed 8.5 per cent to S$2.3 billion.
The company also declared an interim dividend of S$0.01 per share, which will be paid out on Sep 10. This is the first time the company has paid out an interim dividend since 2015.
For FY2023, the company paid out a final dividend of S$0.02 per share.
Ho said that while the company does not have a dividend policy, its profitability has trended upwards.
“If this trend continues into the second half, we should be able to maintain or... increase our dividends,” he said.
Shares of Hong Leong Asia closed 0.7 per cent or S$0.005 higher at S$0.71 on Wednesday.
TRENDING NOW

‘We don’t want to stay as we are’: CEO Patrick Ng builds a more resilient Huationg

URA to review guidelines on floor space to give developers more design flexibility: Chee Hong Tat

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

32 companies, 6 individuals bag accolades at Singapore Corporate Awards 2026

