

Hospitality S-Reits still have room to grow as Chinese travellers return
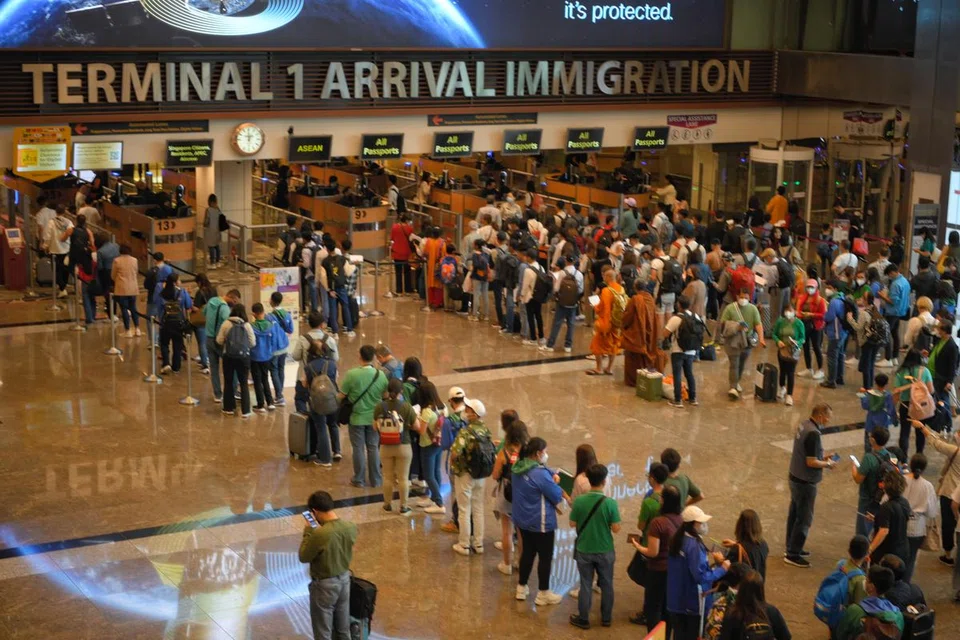
HOSPITALITY real estate investment trusts (Reits) rebounded strongly in 2022, with their distributions per unit (DPU) improving more than their peers as global travel restrictions eased.
While most of these counters are still trading below their pre-pandemic levels, analysts who spoke to The Business Times believe the return of Chinese travellers may help provide the boost needed for further growth.
For the full year ended December 2022, Singapore-listed real estate investment trusts (S-Reits) in the hospitality sector saw the strongest DPU improvement among the S-Reit cohort, with the median DPU rising 31.6 per cent.
The higher DPU came amid improvements in operating performance as borders reopened and travel resumed. Revenue per available room (RevPar) in 2022 still lagged 2019 levels for the full year, but stronger performance started to come through in the fourth quarter.
For example, the RevPar of Far East Hospitality Trust’s (FEHT) hotels segment steadily improved from S$59 in Q1 2022 to S$128 in Q4 2022 – this was around 90 per cent of RevPar for the same period in 2019.
FEHT’s serviced residences segment also saw revenue per available unit (RevPau) rise to S$209 in Q4 2022, which was around 15 per cent higher than 2019 levels.
Meanwhile, CapitaLand Ascott Trust had RevPau of S$120 in 2022, around 79 per cent of 2019’s levels. Its performance has been improving, with RevPau in Q4 2022 reaching S$155, in line with Q4 2019 pre-pandemic levels.
CDL Hospitality Trusts also reported that 13 out of its 17 hotels had achieved RevPar exceeding pre-pandemic levels by Q4 2022.
DBS analysts Geraldine Wong, Tabitha Foo and Derek Tan said in a note this month that 2022 results for the hospitality S-Reits “were inspiring, despite China not being back in the travel game”.
“Most of our hospitality S-Reits have seen portfolio RevPar recover to at least 90 per cent of pre-pandemic levels in Q4 2022, with leisure-focused hospitality S-Reits, such as CDL Hospitality Trusts, benefitting from the generosity of leisure travellers,” the analysts said.
Chinese travellers would be the “long-awaited last piece of the travel puzzle”, they added, noting that such travellers account for around 30 per cent to 35 per cent of Asia’s inbound market share.
“Forward leading indicators show that Chinese travel demand recovery will be fast, wide, and furious, albeit from a low recovery base,” they said.
“S-Reit hoteliers are well positioned to welcome the first flock of Chinese travellers post-reopening, as they have a combined 77 per cent exposure within the top 10 destination markets for Chinese travellers, kicking off the next leg of growth.”
Similarly, Maybank analyst Krishna Guha is positive on the sector, due to the expected rebound in visitor arrivals from China.
He noted that Chinese travellers had accounted for around 20 per cent of international travellers before the pandemic, and probably a larger percentage of tourism spending.
“Once there is visibility of demand normalisation, we expect investors to be constructive and re-rate the sub-sector,” he said.
Guha expects RevPar to climb back to pre-pandemic levels by 2025 as international visitor arrivals recover. Maybank has “buy” ratings on CapitaLand Ascott Trust, CDL Hospitality Trusts, FEHT and Frasers Hospitality Trust .
DBS also has “buy” ratings on all five hospitality S-Reits. Its picks within the sector are CapitaLand Ascott Trust and CDL Hospitality Trusts “to ride on global recovery and sustenance of high RevPar”.
The research house predicts that hospitality S-Reits will continue to see growth in the double-digit range on a year-on-year basis, which would “more than compensate for the higher interest-rate expenses this year and in 2024”.
The DBS analysts also noted that most of the hospitality S-Reits are currently trading below book value, with price-to-book ratios of around 0.7 to 0.9.
“We anticipate that stronger cash flows in 2023 will continue to support capital values for 2023, while the sector could re-rate to trade above its historical mean of 0.9 times, and closer to its book values,” they added.
Not everyone is optimistic about the sector, though.
RHB analyst Vijay Natarajan said hospitality sector Reit valuations are “not cheap” with the sector already trading close to its five-year average price-to-book ratio of 0.9 times.
“This indicates that optimism from a post-pandemic surge has been priced in. With increasing inflationary pressures and recessionary risks, we believe there is a possibility of some of the hospitality demand slowing down post the initial surge from the lockdown,” he said.
While there has been optimism over the return of Chinese visitors, Natarajan noted the pick-up has been slower than anticipated.
“We expect hospitality stocks to trade more range-bound in the near term, with risks tilted towards the downside,” he added.
“Business travel post-Covid has been slow to recover unlike leisure travel which has seen a sharp pent-up demand. So we believe stabilising and brightening of economic outlook along with stronger return of business travel are the likely key catalysts for the sector.”

