

Hot stock: Genting climbs as much as 11.8% after Q3 results beat expectations
Vivienne Tay
SHARES of Genting Singapore jumped as much as 11.8 per cent in heavy trading on Tuesday morning (Nov 14), after its third-quarter results released on Friday beat analyst expectations.
Analysts have raised their target prices on the integrated resort operator, with DBS Group Research upgrading its recommendation on Genting Singapore to “buy” from “hold”.
The counter climbed to a three-month high of S$0.95 at 10.32 am. By 1.10 pm, the group’s shares were the second-most traded by volume with 99.6 million shares changing hands. Genting Singapore was up 10.6 per cent or S$0.09 to S$0.94 by then.
On Friday, the group posted a net profit of S$216.3 million for the third quarter ended September, up 59 per cent from S$135.8 million in the corresponding year-ago period. This came as revenue rose 33 per cent, with both gaming and non-gaming revenue recording gains.
In a report released on Tuesday, DBS Group Research upgraded Genting Singapore to “buy” from “hold” and raised its target price to S$1.05 from S$1.
The research team noted that Genting Singapore’s share price declined by 15 per cent to 20 per cent since its last downgrade to “hold” and it now finds the group’s risk-to-reward profile attractive, despite potential concerns over its longer-term return on capital.
DBS’ upgrade comes as the group plans to invest around S$6.8 billion, from internal resources, to develop Resorts World Sentosa (RWS) further as a tourism destination.
“Although Genting has the financial capability to support this investment through its strong net cash position and robust cash flow generation, we believe this could negatively impact the company’s capacity for capital distribution to shareholders,” it said in a report.
Furthermore, the company has yet to alleviate concerns over the return on investment on these projects, which are expected to be “relatively modest” compared to historical returns on capital, DBS said.
However, it believes that any risks from the substantial rise in projected capital expenditure have been adequately priced into Genting Singapore’s share price.
DBS’ new target price implies a potential upside of 11.7 per cent from the counter’s trading price at 1.10 pm on Tuesday.
It noted that Genting Singapore is still trading at one standard deviation below its five-year pre-pandemic average, despite its solid medium-term earnings outlook.
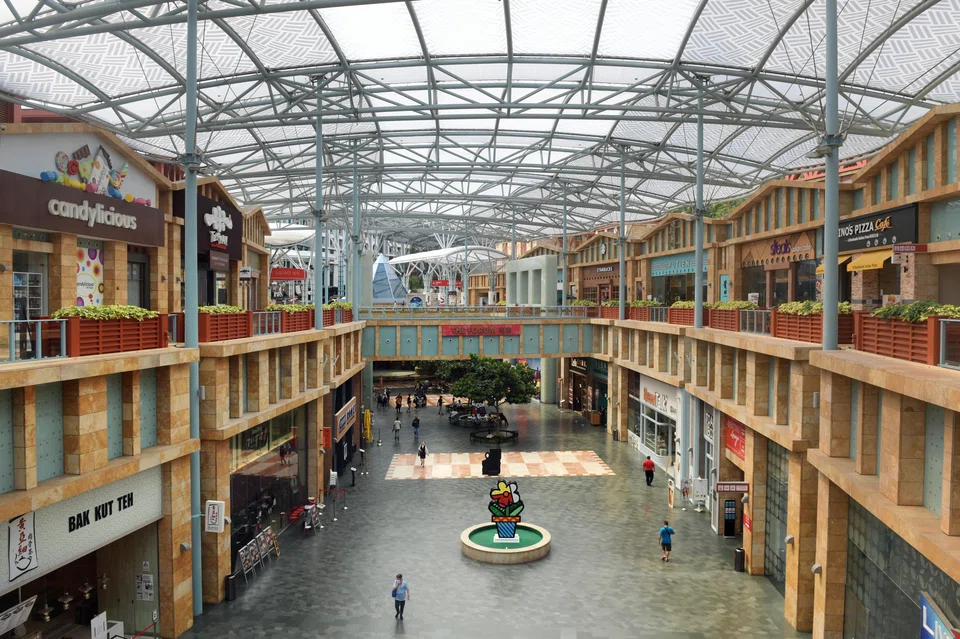
The group is renovating its Forum shopping area in RWS and expects to launch new attractions such as Minion Land and the Oceanarium in early-2025.
DBS has raised its earnings before interest, taxes, depreciation and amortisation (Ebitda) forecast for FY2023 by 12.6 per cent to account for a stronger-than-anticipated recovery in the group’s gaming segment and improved cost control. Its FY2024 estimate, meanwhile, is up 2.4 per cent.
Similarly, CGS-CIMB has upped its FY2023 adjusted Ebitda estimates by 7 per cent on stronger revenue momentum for Genting Singapore. However, it lowered its FY2024 to FY2025 estimates by 0.6 per cent to 2.8 per cent after adjusting for reduced tourist arrivals.
The research team reiterated its “add” recommendation on the counter and unchanged target price of S$1.30, implying a 38.3 per cent upside.
In a separate report, Maybank Singapore raised its target on Genting Singapore to S$1.16 from S$1.12, implying a potential 23.4 per cent upside. It maintained its “buy” call on the counter and also raised its core earnings per share estimates for FY2023 to FY2025 on higher VIP volumes.
The group’s core net profit for the third quarter and nine-month period beat its expectations, as did Q3 VIP volume, which was 55 per cent higher than anticipated.
Based on its records, it estimates that Q3 VIP volume was at its highest since Q2 2015 and now assumes an average quarterly VIP volume of S$10 billion from S$7.3 billion previously.






