

Hot stock: Genting Singapore rises 6.2% amid heavy trading on strong earnings
The group benefits from the relaxation of visa regulations between China and Singapore.
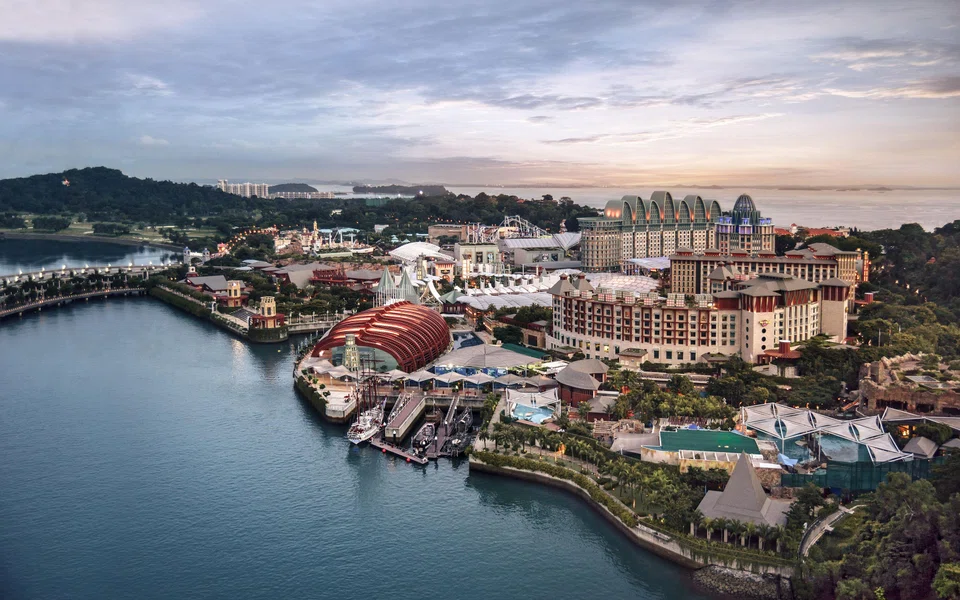
SHARES of Genting Singapore rose as much as 6.2 per cent in early trading as the top traded counter on the Singapore Exchange after the Resorts World Sentosa (RWS) operator on Friday (May 10) posted a Q1 net profit that nearly doubled its year-ago performance.
As at 9.12 am on Monday, its counter was up up S$0.055 to S$0.94 with 32 million shares changing hands. It pulled back to S$0.93 as at 9.25 am, remaining as the most heavily traded counter on the local bourse.
After market closed on Friday, Genting Singapore reported S$247.4 million net profit for the first quarter ended March, up 91.5 per cent from the year-ago period, on the back of 61.9 per cent rise in revenue.
Its gaming segment revenue rose 69.5 per cent to S$576 million, while non-gaming segment revenue climbed 44.2 per cent to S$208.3 million, The group benefitted from the increased tourism spending during the Chinese New Year festive season, as well as from the relaxation of visa regulations between China and Singapore.
Analysts are positive that Genting Singapore will continue to ride on Singapore’s tourism boom, and have maintained their “buy” calls for the group, though they are mixed on its earnings forecasts.
DBS Group Research has raised its FY2024 and FY2025 adjusted earnings before interest, taxes, depreciation, and amortisation (Ebitda) forecasts by 4.3 and 3 per cent, respectively, to factor in the resort operator’s strong Q1 performance and optimism in Singapore’s tourist arrivals and spending. The research house maintained its “buy” call and target price of S$1.15.
“Genting Singapore’s share price has been trending sideways since its Q4 FY2023 results, and we believe that its solid forward earnings momentum is not adequately reflected in its share price, presenting a solid buying opportunity,” said the research house on Monday.
Similarly, CGS International Securities has raised its adjusted Ebitda estimates for FY2024 to FY2026 – up 2.2 to 5.7 per cent while maintaining an “add” call and a target of S$1.30, which is pegged to 9.2 times the five-year historical mean of enterprise value (EV) to Ebitda. This is due to a slight decline in the valuation multiple to 9.2 times from 9.4 times, after recent de-rating of the stock, said CGS analyst Tay Wee Kuang.
Tay also highlighted the counter’s attractive valuation. Its closing price of S$0.885, before Q1 results were release, traded at 5.6 times the forward EV to Ebitda, which is more than one standard deviation below its five-year historical average.
Meanwhile, UOB Kay Hian analyst Jack Goh remains “upbeat” on Genting Singapore’s prospects, given its mega entertainment events in the pipeline and a sustained trend of higher spending per capita in RWS amid the tourism surge. He maintained a “buy” call with a price target of S$1.25.
Maybank analyst Yin Shao Yang also kept a “buy” call, but trimmed core net profit estimates by 7 to 8 per cent to account for higher staff costs and slightly higher reinvestment rates, lowering his price target to S$1.10 from S$1.16.
“Adjusted for normal VIP win rate, we expect Q2 FY2024 to be seasonally slower, but Q3 and Q4 to be seasonally stronger,” added Yin.
TRENDING NOW

Motoring tycoon Peter Kwee is back in court: Here are his previous legal battles

Demand, tech capabilities position Apac and AI as Skyscanner’s next growth frontiers: CEO Bryan Batista

Beyond the greenback, Vietnam’s big borrowers turn to Asian-currency bonds

Nvidia’s outlook cut to stable by Moody’s on governance concerns

