

Hot stock: Marco Polo Marine up as much as 6.8% after Maybank initiates coverage with ‘buy’ call
Benicia Tan &
Yong Jun Yuan
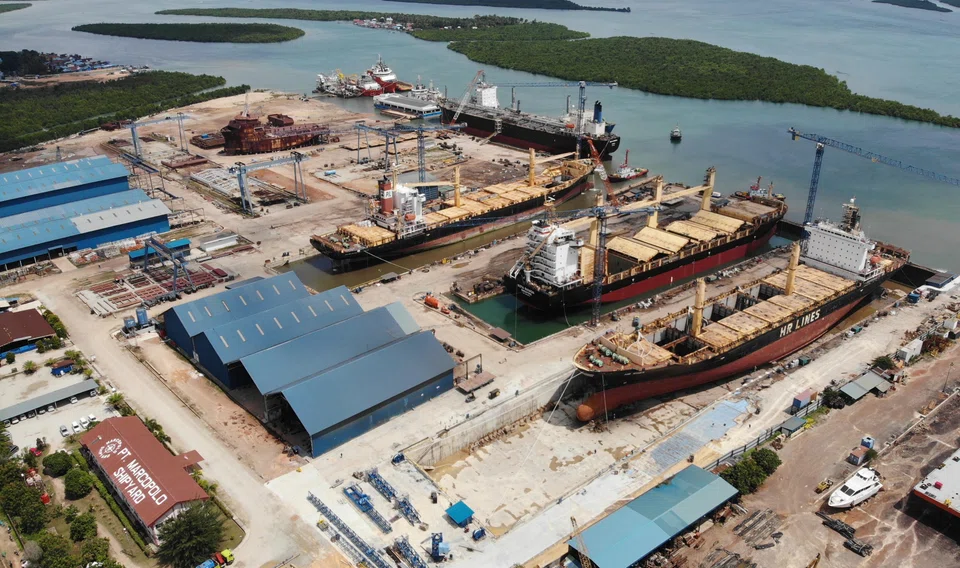
SHARES of Marco Polo Marine rose on Thursday (Mar 21) morning after Maybank Securities initiated coverage on the stock with a “buy” call on Wednesday.
As at 9.23 am, the shipyard and marine logistics company had risen 6.8 per cent or S$0.004 to S$0.063 after 17.1 million of its shares were transacted, which was more than twice the counter’s average volume of about 8.5 million.
The counter later closed S$0.003 higher at S$0.062, after 37.3 million shares worth S$2.3 million changed hands.
No married deals took place in early trade, according to ShareInvestor data.
Two high-value trades of above S$150,000 each were made, with the first taking place at the pre-open at S$0.061 apiece for 4.5 million Marco Polo Marine shares. Another transaction of the same price was recorded at 9.19 am for 9.4 million securities.
After markets closed, the company announced that its Taiwanese subsidiary, PKR Offshore, has secured the Asia-Pacific Crew Transfer Vessel framework agreement with wind turbine manufacturer Siemens Gamesa.
The agreement will last from 2024 to 2026, with an option to extend till 2030, to support Siemens Gamesa’s offshore wind projects in Taiwan and Korea.
The company said that the agreement will contribute positively to the revenue and profits of the group but will not be material to its results and performance in the current financial year ending Sep 30, 2024.
The company’s share price activity comes after Maybank on Wednesday initiated coverage on its stock with a “buy” call and target price of S$0.09.
Analyst Jarick Seet said that he expects the company to benefit from the surge in demand and charter rates due to competition for vessels from the oil and gas, and renewable energy sectors.
Seet noted that rising charter rates over the past three to four years have benefitted Marco Polo Marine’s gross and net margins “greatly”. He projected the group’s charter revenue to grow 25 per cent year on year for FY2024 and FY2025.
Marco Polo Marine’s framework agreement for a new commissioning service operation vessel with wind farm operator Vestas is also expected to boost profits by about 20 per cent from FY2025 to FY2026, said Seet.
In all, the company’s net profit after tax is forecast to grow by a compound annual growth rate of 26.5 per cent from FY2023 to FY2026. This could in turn translate to higher dividends to be paid out by the company, added the analyst. “We believe that while management is conserving cash for expansion of its fleet, it will continue to reward shareholders with higher dividends if the company continues to perform well.”
Seet viewed Marco Polo Marine as “undervalued, especially considering the exciting growth prospects ahead”.
The stock currently trades at a 6.9 times price-to-earnings (PE) ratio based on the brokerage’s FY2024 estimates, which is a discount compared to its peers that are trading at 15 to 25 times PE ratio on average.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Stocks to watch: HPL, Aims Apac Reit, Zico, Advanced Systems Automation, ComfortDelGro

‘How many will survive?’: Bubble fears arise as China’s humanoid robotics face reality check
Smaller board lots can’t fix a market run by three banks

