Hot stock: Samudera Shipping up 27% after declaring high FY21 special dividend
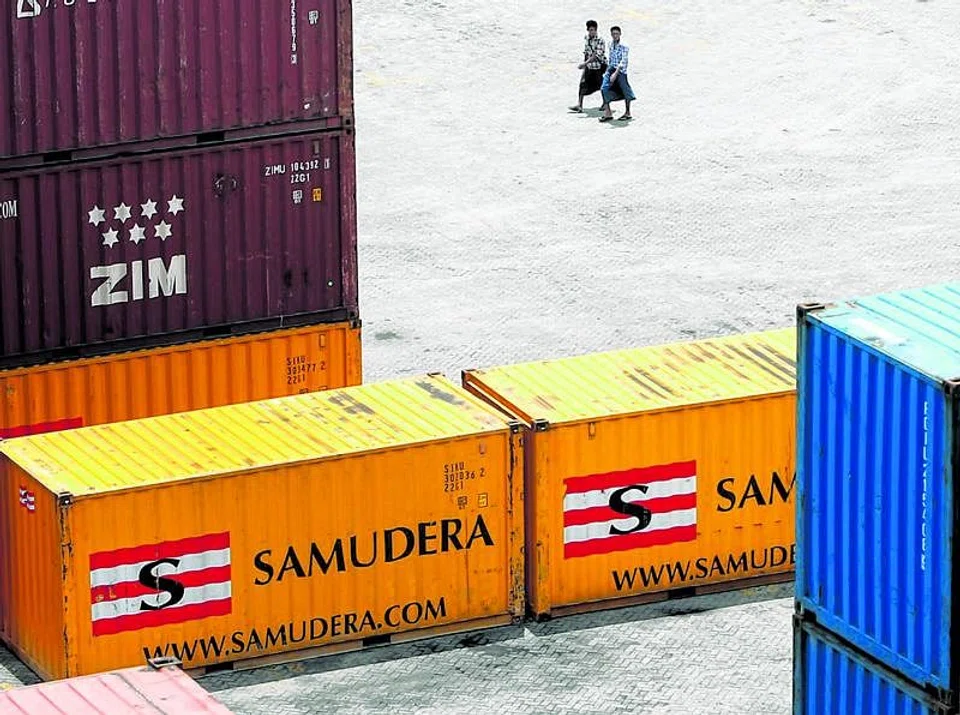
SHARES of Samudera Shipping Line S56 shot up to an all-time high in on Friday (Feb 25) after the shipping company declared a special dividend of S$0.1275 per share in its results for the financial year ended Dec 31, 2021.
As at 4.54 pm, the counter climbed as much as 27 per cent to hit S$0.73, after some 16.3 million shares were traded.
No married deals were recorded, according to ShareInvestor data.
The group on Thursday posted a net profit of US$128.6 million for FY2021, from US$7.2 million the year before, due to better performance from its container shipping segment as a result of higher freight rates.
The board proposed a special dividend of S$0.1275 a share, higher than the S$0.003 special dividend declared the previous year. A final dividend of S$0.0075 a share cent was also proposed, unchanged from the corresponding period the year before.
Shares of Samudera eventually ended at S$0.72, up 25.2 per cent or S$0.145, on Friday.
Following the earnings results, Peggy Mak, head of research at SAC Capital, told The Business Times that Samudera's top line growth of 51.5 per cent was broadly in line, given that container shipping foresight rates were up an average of 81 per cent in Asia.
Regarding its dividend payout, she said while it might improve return on equity, it implies the company has no intention to acquire new assets for growth.
This may be due to its charter-in model, which helps to keep Samudera an asset-light capital structure while limiting the bandwidth for the company to grow revenue and margins, and at the same time subjecting it to the vagaries of the shipping market, she said.
Mak is also of the view that FY2021 is "the peak in revenue and earnings", as the brokerage expects freight rates to decline in FY2022 as the supply chain bottleneck eases.
"The manufacturing purchasing manager's index in the Asean region is also in the expansionary mode, hence giving rise to a more diverse supply chain," Mak said, adding that she expects deliveries of newly built vessels to alleviate the regional shortage in shipping slots.
Highlighting that Samudera has been disposing of ageing vessels, she said as the proportion of Samudera's charter-in vessels rises, its margins will fall in FY22 with higher cost of chartering-in when these charter-in contracts are renewed.
She also said that Samudera's progressive divestment of its Indonesian-flagged vessels may make operations more costly in the region, which may be a challenge for the Indonesia-based company's future revenue as its Indonesian trades had accounted for 28 per cent of its topline.
Meanwhile, Mak believes it is unlikely for the Russia-Ukraine crisis to have a direct impact on Samudera as its vessels ply the Indonesia, South-east Asia, Middle East and Indian sub-continent routes, although rising oil prices will raise bunker prices and add to its operating costs.
READ MORE:
- Samudera Shipping riding the Covid-19 tide
- Brokers' take: Lim & Tan initiates coverage on Samudera at 'buy' with S$0.49 target
- Samudera spies opportunities for growth in Indonesia