

Hot stock: Singapore Airlines breaks 12-day winning streak, falls 1.8% to S$7.77
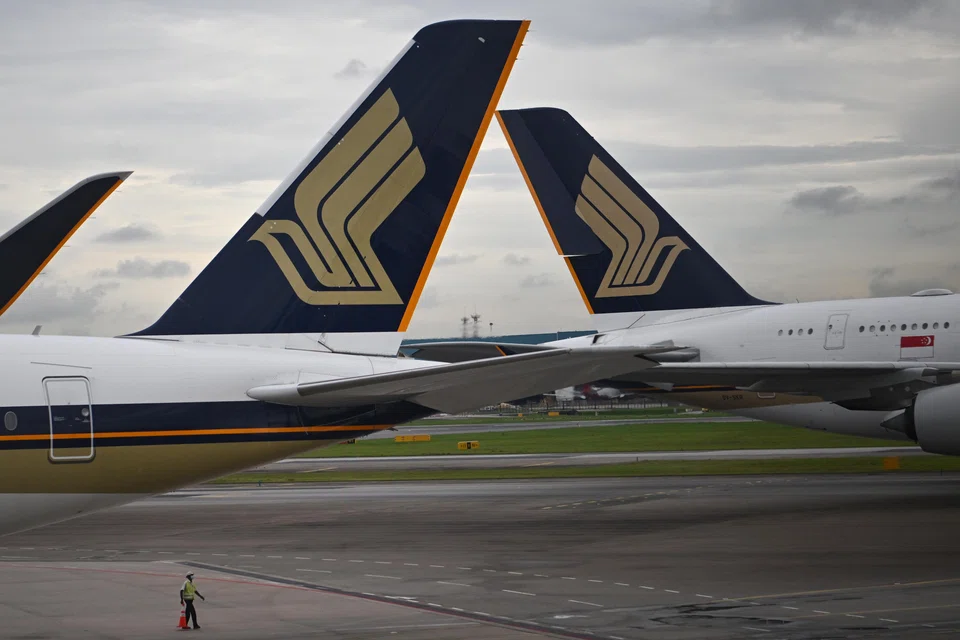
SHARES in Singapore Airlines (SIA) closed 1.8 per cent down at S$7.77 on Friday (Jun 16), ending its 12-day winning streak.
About 41 million shares changed hands. No married deals were recorded, data platform ShareInvestor indicated.
By contrast, the Straits Times Index was up 0.5 per cent to 3,260.03 points, led by gains in large-cap companies including Thai Beverage, Genting Singapore and Sats.
This comes as the airline on Friday refuted a media report saying it may raise its stake in Air India to create a bigger full-service national carrier for India.
Reuters reported that SIA’s statement is in response to a report by Indian newspaper Mint, which said the carrier had expressed its desire to gradually raise its stake in the Indian airline to about 40 per cent.
“The Mint story dated Jun 16, 2023, is incorrect. There (is) no change in SIA’s position from the November 2022 announcement,” SIA said.
Meanwhile, recovery in air travel appears to have served Singapore’s national carrier well; it reported on Thursday that, together with its budget carrier Scoot, it served 2.8 million passengers in May – a year-on-year increase of 65.8 per cent.
SIA attributed this to a strong demand for air travel, noting that passenger traffic and load factors were “robust” across all route regions.
The airline’s share price closed higher for 12 consecutive days from May 29. Analysts from Morgan Stanley believe such gains could signify that the positives have been priced in.
They downgraded SIA from “overweight” to “even-weight” in a report on Friday, with a revised target price of S$7.30, noting that the counter had risen 43 per cent year to date and 34 per cent on the month.
“Although we argued for re-rating as part of our prior overweight thesis, this looks played out, and we move to even-weight,” said the analysts.
They also switched their valuation framework from price-to-book ratio to enterprise value against earnings before interest, taxes, depreciation, and amortisation, on the belief that this would better capture its profitability outlook post-pandemic.
However, further upside for the stock could be driven by favourable flows, earnings upgrades, and/or valuation re-rating, said the analysts.
Assuming cargo yields stabilise at current levels and costs remain well-controlled, SIA’s earnings could grow 15 per cent in FY2024, they added.
In such a scenario, the stock could continue to re-rate, giving rise to a “bull case” of S$9.30, they said. Morgan Stanley has forecast SIA’s FY2024 net profit at S$1.9 billion.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Quarter of Singtel special discounted shares sold ahead of CPF Board transfer

Why Tan Aik Keong of digital solutions specialist Agmo wants to make himself less indispensable

Asia needs new energy security architecture

