

Hot stock: Yangzijiang Shipbuilding nears 7-month high after contract win
Chong Xin Wei
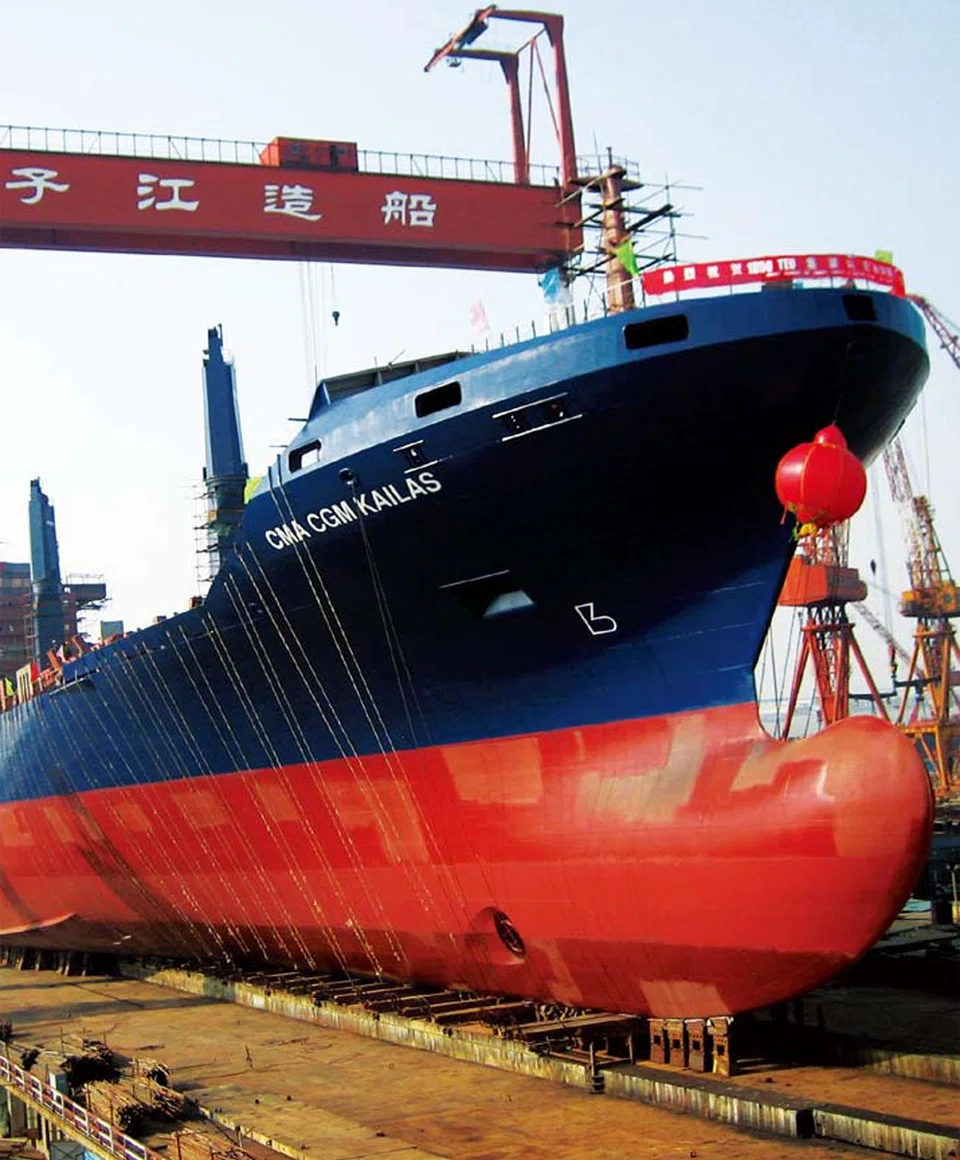
SHARES of Yangzijiang Shipbuilding hit a near seven-month high in early trading on Tuesday (Jun 27), after the group said that it obtained a contract to build six 9,000 twenty-foot equivalent unit methanol dual-fuel container ships.
The shipbuilder’s counter rose as much as 8.1 per cent or S$0.11 to S$1.46 as at 4pm on Tuesday. The last time the counter closed near this level was on Nov 30, 2022.
Shares of Yangzijiang later closed up 7.4 per cent or S$0.10 at S$1.45, with 77.6 million shares changing hands. There were no married deals according to ShareInvestor data.
On Monday, the group said that it bagged new orders for 69 vessels worth about US$5.6 billion in the year to date, exceeding its US$3 billion target for 2023.
Analysts from DBS Group Research and Citi were positive on the group’s second quarter contract wins of 46 vessels totalling US$4.4 billion, including its latest order win from Maersk.
DBS said that the group’s Q2 order wins were “mind-blowing”, as the market expected contracting activities to slow down from last year amid “hefty order backlog”.
It expects the group’s year-to-date wins, which are almost twice its order guidance, to rejuvenate its muted share price performance and low valuation.
The all-time high order book could also provide four years of revenue visibility.
Yangzijiang’s order book value stands at US$14.6 billion for 180 vessels.
“We surmise that the likelihood of them expanding current capacity and expediting delivery is increasing with the huge order intakes in Q2,” DBS said. This could prompt the shipbuilder’s yard to become more efficient and productive, it added.
Separately, Citi believes that the near-term outlook remains favourable for Yangzijiang and expects further order wins to drive share price re-rating.
Citi added that the recent year-to-date depreciation of the yuan could pose upside risk to the shipbuilder’s performance in the first half of 2023. This comes amid the group’s positive earnings sensitivity to the US dollar appreciation.
Additionally, research house CLSA said that Yangzijiang’s order win from French shipping giant CMA CGM, estimated to be worth up to US$3 billion, could position the group as a leader in dual-fuel ultra large container vessels.
DBS, Citi and CLSA have a “buy” call on the counter, which traded at S$1.44 as at 1.32pm on Tuesday.
DBS’ and CLSA’s target prices stand at S$1.70, implying a potential upside of 18.1 per cent. Meanwhile, Citi has a target price of S$1.56, implying a potential upside of 8.3 per cent.
TRENDING NOW

From legacy to launch: Francis Yeoh and Yeoh Pei Xien on family unity and YTL’s next‑gen ventures
Things to know about DBS’ incoming chairman Anthony Lim
Wealthy Indonesians snap up government bonds as yields near 8%: OCBC
From local AI partnerships to global opportunities: How MNCs help Singapore firms scale

