

How war and Fed fund rates may impact your Singapore stock portfolio
Periods of heightened market risk are typically created by shifts in expectations, which investors need to consider and price in
EQUITY market research tells us that wars tend not to have lasting effects on stocks. The same goes for major geopolitical shocks. Initial overshoots correct themselves quickly, and investors should aim to sit tight.
This is generally good advice, provided you have a generally diversified portfolio.
A study by LPL Research of 21 geopolitical events – ranging from Pearl Harbor to 9/11 – found that the S&P 500 index on average fell by 1.2 per cent on the first day of the event. It took an average of 22 days from then for the market to hit rock bottom, with an average loss of 5 per cent. This loss was recovered in 47 days.
Another study, by the CFA Institute, showed large-cap US stocks have returned an average of 11.4 per cent in the periods leading up to and during four major wars. This is slightly better than the average return of 10 per cent for large-cap US stocks from 1926 to 2013. Small-cap stocks returned 13.8 per cent during wartime versus an average of 11.6 per cent.
CFA Institute’s findings also showed that both large-cap and small-cap stocks managed their wartime outperformance with less volatility.
Examining only the averages, however, puts investors at risk of missing the trees for the forest. Yes, this is not how the proverb goes, but not all investors possess the good habit of buying forests.
US dollar strength
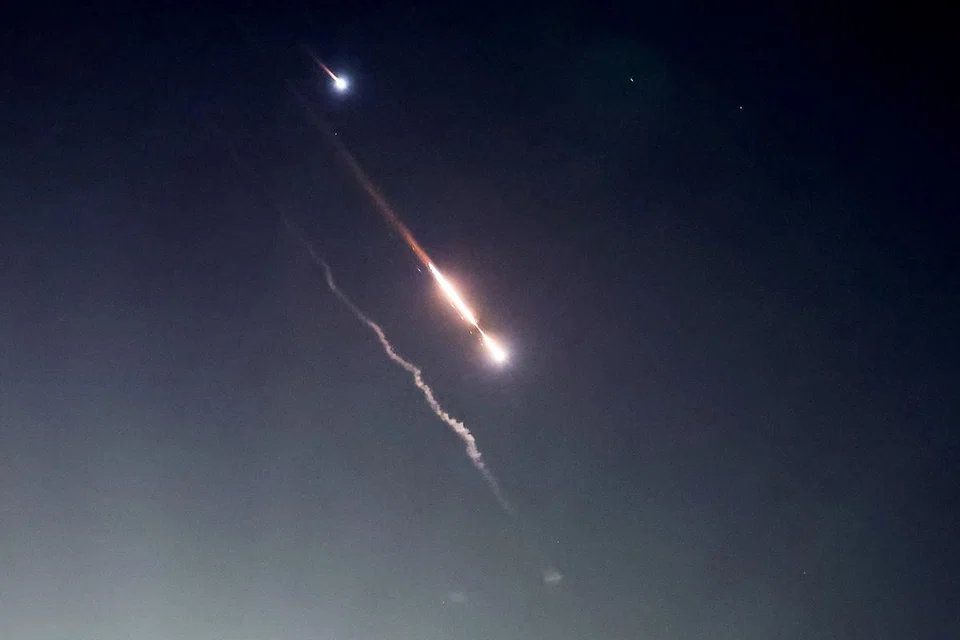
This past week, markets have been negatively affected by two events. One is the prospect of war in the Middle East, after Iran launched an aerial attack on Israel. The other is the near certainty that the United States Federal Reserve will not cut the Federal funds rate in the first half of this year.
Fed chair Jerome Powell confirmed market expectations at an event in Washington on Tuesday (Apr 16). “Given the strength of the labour market and progress on inflation so far, it is appropriate to allow restrictive policy further time to work, and let the data and the evolving outlook guide us,” Powell said. The Fed lacks confidence that inflation is sufficiently under control for it to raise rates, he added. “The recent data have clearly not given us greater confidence, and instead indicate that it is likely to take longer than expected to achieve that confidence.”
Powell’s comments did not immediately spur the US dollar to greater heights, perhaps because the sentiment was already priced in. In fact, the US Dollar Index fell during Asian trading hours on Wednesday.
Market analysts are nevertheless confident that the US dollar will remain resilient, possibly even extending an upwards trajectory that began at the start of this year.
Sim Moh Siong, currency strategist at the Bank of Singapore, said in a note on Wednesday that expectations of reduced Fed action have taken the US dollar to new highs.
From here, he believes the US dollar has less room to rise but also limited room to fall. A “shallower Fed rate cutting cycle could limit the scope for a weaker US dollar” in the second half of this year, he added.
Factor in Middle East uncertainties, and the prospects for the US dollar improve. War and geopolitical conflict tend to lead to inflation, which could force the Fed to delay action even further. In risk-off situations, investors also tend to flock to safe havens. These include gold, which is priced in US dollars, and US Treasury bonds.
Singdollar weakness
The Singapore dollar has declined 3.2 per cent against the US dollar this year. Continued Singdollar weakness would on average be negative for Singapore stocks. A Bloomberg scenario analysis showed a 5 per cent weakening in the Singdollar versus the US dollar is associated with a 5.9 per cent fall in the Straits Times Index (STI). For the broader Singapore market, the fall is even steeper – at 7.6 per cent.
US dollar strength is not negative for all stocks, of course. Traditionally, US dollar beneficiaries within the STI have included conglomerate ST Engineering and tech manufacturer Venture Corp , both of which collect some of their revenues in US dollar. Flag carrier Singapore Airlines (SIA), meanwhile, would face higher costs as jet fuel is priced in US dollars.
Should investors prepare their portfolios by selling SIA and buying ST Engineering, then? The latter has the added benefit of being a supplier to the military and defence industries. Yet, ST Engineering now trades at 20.9 times’ historical earnings – close to its long-term average of 19.8 times. SIA is trading at 11.1 times – far below its long-term average of 21 times.
The point of this is not to suggest that investors take a short-term and opportunistic approach to building or shaping their portfolios.
Periods of heightened market risk are typically created by shifts in expectations, which investors need to consider and price in. Portfolios should be stress tested, and rebalanced in accordance with risk appetites or investment horizons. This means looking at the forest but also checking all the trees.






