

HSBC Singapore sets its sights on SME segment
It aims to expand its share of the market to 15 per cent from the current 10 per cent by 2021. BY VIVIEN SHIAO
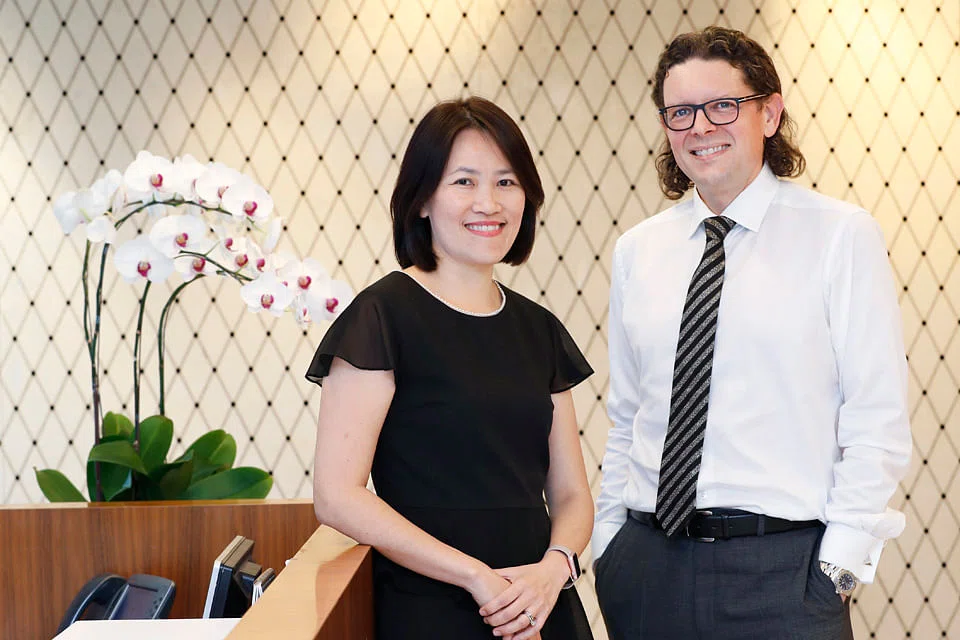
HSBC Singapore is no longer taking the back seat when it comes to the small and medium-sized enterprise (SME) banking segment here, with plans to raise its share in its target SME market from the current 10 per cent to 15 per cent by 2021.
As part of its global strategy, the Hong Kong-listed bank is scaling up its SME business in Singapore to become a key area of focus, in a move to capitalise on growth opportunities in the Asean region.
HSBC - which has been present in Singapore since 1877 - classifies SME clients as those with a turnover of US$5-US$100 million. To drive growth in SME lending, the bank increased its headcount in business banking by 30 last year. The SME banking segment comes under its business banking unit.
Alan Turner, managing director and head of commercial banking in HSBC, explained that the SME segment in HSBC Singapore received "renewed vigour" on the back of the group's announcement in 2018 that identified Singapore as one of its eight "scale markets", or markets where group investment will be channelled to support growth.
Financial capital
The reasons for this are manifold. "At a high level, we see Singapore as a de facto financial capital for Asean, as well as an attractive destination for our customers around the world," he said.
"With the heritage we have in Singapore and the attractiveness of Asia compared to other economies around the world, it is a very obvious destination on which to focus HSBC's growth."
Even so, competition in the SME lending space in Singapore is stiff. But HSBC country head of business banking Ng Li Lian said that the bank has some "unique" advantages, including having a dedicated relationship manager for each SME client.
"This means that they know the clients well as they are not served by a call centre," she said. "SME business owners tell us that the ability of our relationship managers to talk to them in-depth about their plans and give them advice is valuable to them."
Mr Turner added: "We do not participate in any form of self-serve business when providing banking services."
He also pointed out that HSBC's global network makes a difference for local SMEs intending to internationalise - the group's 54 commercial banks around the world cover 90 per cent of the world's trade flows.
Pioneer programme
As part of its plans to grow its SME business, the bank launched its Pioneer programme in August 2018 to target fast-growing SMEs with a minimum topline growth of 15 per cent, especially those with aspirations to internationalise.
Mr Turner explained that the 12-month programme gives the SME leaders access to skills, capabilities and knowledge to grow their business.
These leaders are offered conversations with different teams in HSBC, for example, with the alternative finance team on how to raise capital other than through debt, or with the trade and cash management team to review working capital processes.
"We have taken what is the best we can do for an MNC and distilled it into a programme that could help a small business owner to understand and engage with their business," he said.
Instead of an actual incubator where startups are housed in their premises, he described it as more of an "HSBC-filled adrenaline shot" to push businesses to the next level.
Since the programme was piloted, Mr Turner said that the bank saw a 30 per cent improvement in the fulfilment of the SMEs' key performance indicators that they set out for themselves, which could be in terms of revenue, units of sales or capacity building.
The ongoing initiative, which used to be reserved for existing clients, is now being extended to companies which may be new to the bank. There are now 51 companies participating in the programme today.
Even as HSBC Singapore looks to SME banking as an avenue of growth, it is also cognisant of the risks involved.
When oil prices dived a few years earlier, many small oil and gas firms went belly-up, resulting in many local banks having to write off loans.
But Mr Turner said that the bank emerged relatively unscathed. He explained: "If your strategy for SMEs is not fully considered and fully-baked, then your exposure to particular events, such as cyclical ones, can be very pronounced."
He added that the bank has a risk appetite for clients irrespective of size, but the most important thing for them is whether the form of finance can "best satisfy the underlying need".
"Our proposition is not just about the provision of capital, but capital in the context of advice and assistance on whatever forms of capital other than debt capital might be available," he said.
"We actually think SMEs are a highly attractive segment if you engage with them correctly - in a number of markets in the world, SMEs are the jewels in the crown of what we do."
TRENDING NOW

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Income Insurance appoints former Manulife Singapore top man as new CEO

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

