

iFast mulls more banking licences in the EU, Singapore amid global push
The company’s banking business is a key part of its three-year plan, which includes reaching a target of assets under administration of S$100 billion by 2028 to 2030
WHEN iFast bought a bank in the UK in 2022, it had ambitions to build a “truly global business model” that serves customers from around the world from a few key locations.
Two years later, the digital bank has narrowed its losses and is expected to turn profitable in the fourth quarter of its 2024 financial year.
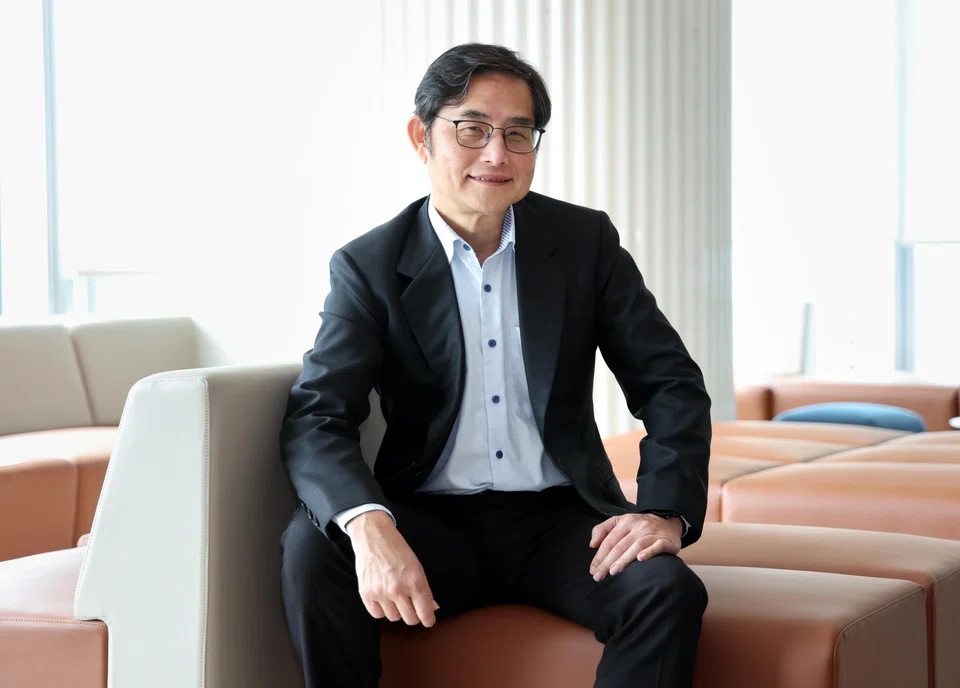
And iFast chief executive Lim Chung Chun expects more opportunities for the company to apply for licences at “a couple more locations” to boost its global model.
For starters, he has set his sights on the European Union (EU) and Singapore.
“We don’t need to go to get a licence in too many countries, since the strength of the business model is being able to have customers from around the world by operating from just one or a few locations,” Lim said in an interview with The Business Times.
“Having said that, there are probably still one or two other locations that we will be looking into more closely for the opportunities, so that we can tap into this global opportunity better,” he added.
Lim noted that the EU is a big market and has close proximity to the UK. He said: “Our initial success and progress that we have seen in the UK is telling us that the opportunity is real.”
Meanwhile, Singapore is home base for the wealth management player. While it had unsuccessfully applied for digital banking licences in the Republic back in 2021, Lim hopes it can take “a more active approach” in trying for a licence again over the next few years.
iFast’s banking business – known as iFast Global Bank (iGB) – is a key part of its three-year plan, which includes reaching a target of assets under administration (AUA) of S$100 billion by 2028 to 2030.
Group AUA rose 23.6 per cent year on year to reach S$23.6 billion as at the third quarter of 2024. This was amid a 53.4 per cent rise in net profit to S$64 million in Q3, as revenue rose 49.7 per cent to S$99.1 million.
Untapped potential
Banking is an area that Lim sees “very substantial untapped potential”. Even though it is the oldest segment in the financial sector, he noted opportunities, particularly in wealth management for retail and mass affluent clients.
He noted that today’s banks do not need to be constrained by geography when acquiring clients due to global connectivity – a trend largely seen in the high-net-worth space, such as with global private banks.
Yet, similar offerings are not yet available for retail or the mass affluent market segment, Lim said.
“There is a very substantial demand from people around the world to have a bank account outside their home countries, but most banks are not catering for them, or not actively trying to tend to that segment.”
The CEO noted that for offshore investing, one of the first things customers do is to open a bank account, yet the process remains difficult outside one’s home country.
“By having a bank within the ecosystem where they can open a bank account, this accelerates our ability to directly address this group of customers from various countries,” he said.
This should also bring synergistic benefits to iFast’s main profit driver – its wealth management platform.
For example, “quite a lot of clients” who started banking with iFast through the UK-based bank have already transferred funds to Singapore, where they invest through its platform.
As at Sep 30, 2024, iGB’s deposits stood at S$805.6 million, up from S$358.6 million as at Dec 31, 2023.
Currently, 70 per cent of deposits come from non-UK residents from over 90 countries, with a number of Asian countries contributing to the bulk of the non-UK deposits.
This synergy and integration is something that Lim expects to be a growing trend that can accelerate the growth of its investment platform as well.
Meanwhile, iFast has “pretty clear advantages” compared to traditional banks, such as its faster speed in technology innovations and lower costs, Lim said.
In fact, the company’s operating costs are even lower than that of the digital banks awarded licences in Singapore, he said.
Lim views the banking space as less competitive than the investment space, mainly because more players get created in the latter than the former each year.
Three-year plan
Another target of its three-year plan was to accelerate the growth of its Hong Kong business as it delivers on its ePension services.
Lim noted that the ePension business is currently in its ramping up phase. The division is also preparing to launch its in-house digital pension solution platform in the first quarter of 2025, which will help contribute to its overall AUA target.
A key thing is to ensure that iFast can run the business efficiently, he said.
“We want to continue to deliver the service very well in the years ahead, so that the project hopefully will last much longer, well beyond (the current contract of) seven years.”
Lim expects the platform business will continue to grow at a good pace in the longer term, even though it still sees fluctuations in the short term due to changes in market conditions.
Commenting on iFast’s share price, Lim noted that the company is more focused on its plans to grow revenue and profitability.
Shares of iFast had fluctuated over the years – it surged 180 per cent in 2021 amid a spike in market trading activity, but lost 30.5 per cent the following year. Shares rebounded 40.6 per cent in 2023 before slipping 9.7 per cent in 2024.
In the year to date, the counter has dipped 1.5 per cent to close at S$7.31 on Friday (Jan 10).
“More importantly are the overall fundamentals – the actual growth in revenue and profitability,” Lim said.
“That’s why, in the last two to three years, we have been talking about our plans because there were some new strategies that we wanted to articulate better.”






