

Iron ore rush turns two SGX plays red hot
Shares of Fortress Minerals, Southern Alliance Mining have jumped 25% and 61%, respectively, this year
Singapore
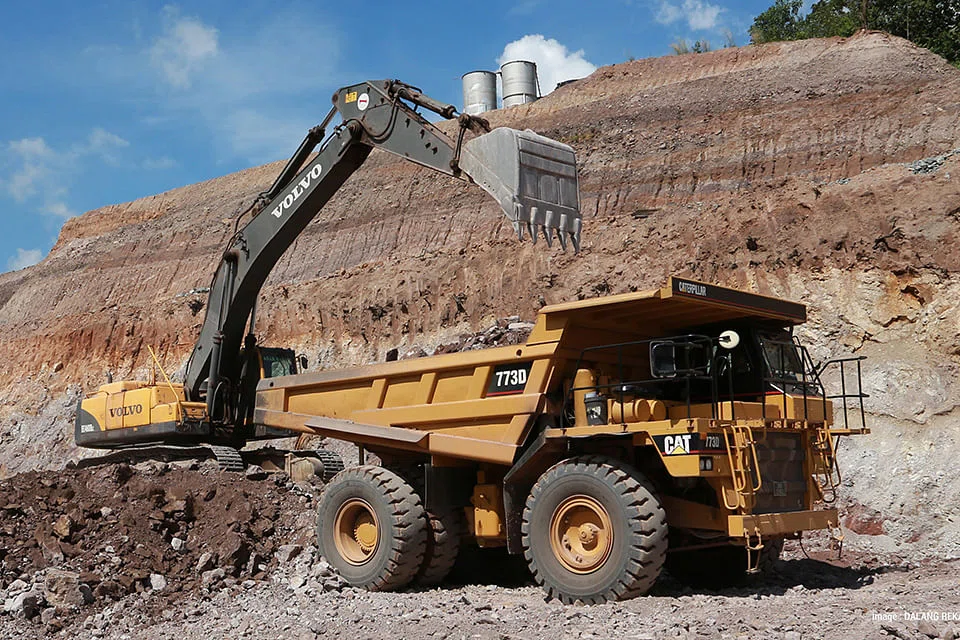
TWO iron ore plays on the Singapore Exchange, both Malaysian-based, have been quite the rage as steel mills make good money and inventories shrink on higher demand. As prices of the sought-after reddish metal trended higher, so have the shares of those that mine and sell it.
Catalist-listed Fortress Minerals, for instance, enjoyed record sales volume in the nine months to November last year (the company has a February year-end). Its net profit for Q3 FY2021 was nearly double that for FY2020, and the counter has gained 25 per cent this year to close at 37.5 Singapore cents on April 6.
The shares of its sector peer Southern Alliance Mining (SAM), which has a mine in Johor, Malaysia and is also listed on Catalist, have surged 61.1 per cent to 58 Singapore cents over the same period.
Despite lower sales volume across all products in the first half of FY2021, SAM's revenue improved by nearly 8 per cent to RM152 million (S$50 million), thanks to an increase in the average realised selling price of iron ore concentrate. Net profit over the period jumped 47 per cent year on year to RM51 million.
Global prices for the ferrous commodity have risen 8 per cent this year led by a booming recovery in China, which is the world's main buyer of iron ore, and tight supplies. SGX's market strategist Geoff Howie said this is a continuation of a robust rally, with prices having soared 80 per cent in the second half of 2020 from end-June levels. In March this year, prices hit their highest levels in almost a decade.
Quite naturally, both companies expect to fully capitalise on the industrial metal's boom.
Fortress Minerals expanded its Bukit Besi mine's processing plant in Terengganu, Malaysia in FY2019 and now produces an average of 40,000 wet metric tonnes (WMT) a month of iron ore at an 80 per cent utilisation rate. The company plans to crank up production and iron ore deliveries, said its executive director and chief executive Ivan Chee Yew Fei.
Capacity utilisation should be boosted by a 400,000 WMT offtake agreement inked last September. And even if iron ore prices taper in 2021 as supply balances out demand, an analyst at Phillip Capital said the company's revenue should still rise thanks to this agreement.
SAM, meanwhile, has been doing more drilling at its Chaah Mine in Malaysia's southern state while expanding its product portfolio.
Apart from iron ore concentrate and pipe coating materials, it has also started selling tailings, or waste from the iron ore concentrate process.
"The main driver of the decision to sell tailings is the high market price. The high price has brought in buyers, particularly those whose business models comprise upgrading low grade ore (including tailing) by mixing it with higher-grade ore for onward sales," SAM's chief executive Pek Kok Sam told The Business Times.
"As tailings are not the group's main product, any sale arising from tailings will be a bonus. The demand for tailings will be there as long as the iron ore price remains high," he added.
Both companies have also said they may look into doing some mergers and acquisitions.
"Our in-house team of geologists have evaluated some interesting opportunities in iron ore and other minerals both in Malaysia and the region," said Fortress Minerals' Mr Chee, adding that Fortress Minerals was constantly seeking opportunities to acquire or enter into a joint venture for new mining assets, not just in Malaysia but also the region.
In February, Fortress Minerals got its shareholders' go-ahead for its first acquisition - a US$30 million buyout of a Malaysian iron ore and copper producer, which it hopes will power its regional game.
According to Mr Chee, who owns 50.25 per cent of Fortress Minerals, the newly acquired Mengapur project can commence quickly as the company already has some of the necessary plants and machinery. This will result in cost savings and drive volumes, given the "major" operational overlap with the Bukit Besi mine.
As for SAM, Mr Pek said the firm is in different stages of talks with "a few parties for the collaboration and possible acquisition of new mining rights at various locations".
"We have a healthy balance sheet and proven track records that give us some mileage and advantages when we approach the mining landowners for mining leases. I am optimistic that we will be able to conclude some meaningful deals," he added.
As at end-January, SAM had cash and bank balances of RM190.1 million and borrowings of RM5.8 million.
Both chiefs are sanguine about the outlook for iron ore.
"Prices, especially of our high-grade iron ore concentrate, have been performing relatively strongly over the past months or so primarily due to the strong demand from Chinese steel mills. Market sources expect higher grade demand to increase further if steel margins continue to strengthen," said Mr Chee.
Mr Pek said demand in Malaysia is also expected to remain robust. Since 2018, when Malaysia reversed its position as an iron ore and concentrate exporter, demand has greatly exceeded supply. With an anticipated recovery of the oil and gas sector post-pandemic, he is hopeful that demand for pipe coating materials will rebound soon.
SAM's market capitalisation stands at around S$280 million versus Fortress Minerals' S$190 million.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Quarter of Singtel special discounted shares sold ahead of CPF Board transfer

Why Tan Aik Keong of digital solutions specialist Agmo wants to make himself less indispensable

Asia needs new energy security architecture

