

Is white-knight offer Hyflux's last, best hope?
JUST two days after Hyflux Group's judicial managers filed an application to wind up the crisis-hit company, Utico CEO Richard Menezes made a surprise rescue bid for it. Still, with the proposal short on details and clarity at the moment, those involved need to proceed with caution - and perhaps ask which is truly the last, best hope for Hyflux's wearied stakeholders, after all this time.
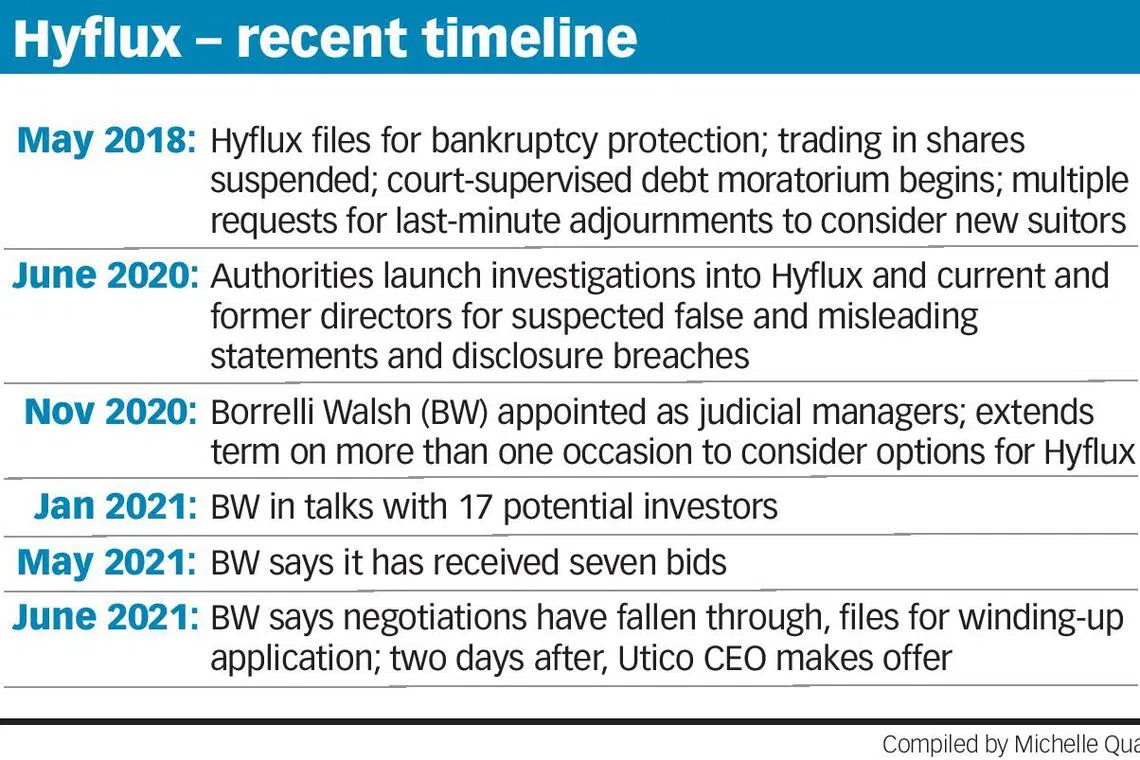
To recap: Hyflux's judicial managers Borrelli Walsh (BW) said in a bourse filing on June 4 that they had filed an application with the court to wind up the water treatment company.
This was after having been granted an extension for their terms of office until July 14 to determine whether a potential restructuring of the group was possible.
Hyflux had been placed under judicial management in November, when there were three offers on the table, from US-based Strategic Growth Investments (SGI), Middle Eastern utility firm Utico, and Pison.
By January, BW said they were in talks with 17 potential investors, which had included SGI, Spain-based FCC Aqualia and Utico.
In May, BW said they had received seven bids: one bid for an investment in the entire group; and six bids for specific assets of the group, which can be facilitated through a winding-up of the group.
But on June 4, BW said negotiations with the investor for an investment in the entire Hyflux Group were unsuccessful, and that "a restructuring is not possible". They added that "the continuation of the judicial management of the company is no longer necessary" and that the remaining value of Hyflux would be "best realised in a liquidation".
But then, a surprise seemingly 11th-hour rescue bid emerged: Mr Menezes told The Business Times on June 6 that he has reached out to BW with a deal, though he declined to share the exact details.
But he did say that unsecured senior creditors would receive five cents on the dollar, while retail investors in Hyflux's preference shares and perpetual securities (PnP) would receive four cents.
He said he has agreed to place S$50 million of his personal shares in Utico in escrow to guarantee the deal, and that this would be followed by S$50 million in cash once an agreement has been signed.
He said that he had told BW to "save the company and make it equitable" and that "liquidation should be the last option".
BW declined to comment on this when they were contacted by BT.
Until we hear otherwise, Mr Menezes's offer would appear to be Hyflux's last stab at the possibility of getting restructured and becoming equitable, but is it Hyflux's best hope? The question would be most pertinent to Hyflux's PnP holders, whose fortunes differ the most, depending on whether the company is liquidated or rescued.
In a liquidation, Hyflux's PnP holders rank below all other creditors of the company in terms of distributions, but above holders of its ordinary shares; and the expectation is that PnP holders would potentially receive a lot less if Hyflux were wound up than if it were to be rescued.
But there are other considerations at stake.
One, it is unclear if Mr Menezes's offer is too late. The Utico CEO himself said: "The judicial managers might not accept my offer as they announced investor talks failed".
Before making their winding-up application, BW had gone through several rounds of negotiations with numerous bidders and very likely believed that they had exhausted all the credible options before them.
Two, it's not exactly clear what Mr Menezes's offer entails - for example, would Hyflux's creditors and PnP holders receive Utico shares, cash or a combination of both? And when? Are there conditions that need to be fulfilled before the various aspects of the offer are realised?
Without further clarity, it is difficult to determine if this proposal would offer Hyflux a realistic chance at being restructured and be more appealing to the company's various stakeholders than a liquidation at this point.
Some would argue that, despite the distinct possibility of Hyflux's PnP holders receiving a smaller distribution from a liquidation than from a rescue deal, given the long-drawn out debt-restructuring efforts that Hyflux has been through, even a tiny amount - coupled with the knowledge that this would be the end of the saga - would be preferable to a further extension of the less-than-hopeful journey it has been so far.
A couple of PnP holders BT spoke to said that they have more or less written off their not-inconsequential investments in Hyflux, and have not been holding out for a distribution; any amount, one said, would be a "bonus" in the current situation.
Hyflux's shares have been suspended from trading since May 2018, and its debt-restructuring efforts have gone on for just as long - and it has been a journey fraught with controversy along the way.
It also remains unclear just how much cash the company holds; Bloomberg had in March cited sources saying that Hyflux had S$18.4 million in cash, as of Jan 31 - but BW declined to comment on this. The one thing that's for sure is that this is an amount that will continue to decrease as judicial management and restructuring efforts go on.
And so, while it's understandable that some would cheer the news of a fresh white knight for the company, at a time when all hope seems to have been lost, a lot more information about this new rescue offer is needed before one can decide which option is truly Hyflux's last, best hope.






