

Keppel, Sembmarine begin talks on merger of O&M operations
Market watchers are unsurprised by the development, and believe this could lead to a re-rating of Keppel's shares
Singapore
BN4 and S51 (Sembmarine) will kick off talks that could see a merger of their offshore and marine (O&M) operations and leave both companies in stronger positions.
The two companies on Thursday signed a non-binding memorandum of understanding (MOU) to enter into exclusive talks with the aim of merging Keppel O&M and Sembmarine.
Discussions and due diligence are expected to take several months, but the envisioned plan is for a combined entity that will be owned by both Sembmarine's shareholders and Keppel's shareholders.
In exchange for its O&M assets, Keppel would receive a combination of cash and shares in the combined entity. These shares would then be distributed to Keppel's shareholders.
Keppel and the combined entity will also establish a 50-50 joint venture so that Keppel can continue to tap Keppel O&M's capabilities for projects.
Both Keppel and Sembmarine also announced transactions that would strengthen their balance sheets.
Sembmarine intends to raise S$1.5 billion via a 3-for-2 rights issue. It will issue up to 18.83 billion new shares at S$0.08 per share - a 35.7 per cent discount to the theoretical ex-rights price and a 58.1 per cent discount to the counter's close at S$0.191 on June 23, before a trading halt was called.
Temasek Holdings will subscribe for its 42.6 per cent pro-rata entitlement and apply for excess rights shares such that it subscribes for up to 67 per cent of the rights issue. DBS will underwrite the remaining 33 per cent.
Temasek will also provide support to Keppel by procuring investors to buy 80 per cent of an asset company that will hold Keppel O&M's completed and uncompleted rigs as well as associated receivables. Keppel will hold up to 20 per cent of this asset company.
Keppel will receive consideration for these assets in the form of credit notes, and its economic exposure to these assets will be reduced over time as the rigs or the asset company are sold or securitised. Keppel will also no longer have to fund the completion of these rigs, and will be able to deconsolidate associated debt.
The sale of the rigs and the merger of Keppel O&M will be inter-conditional transactions, Keppel said.
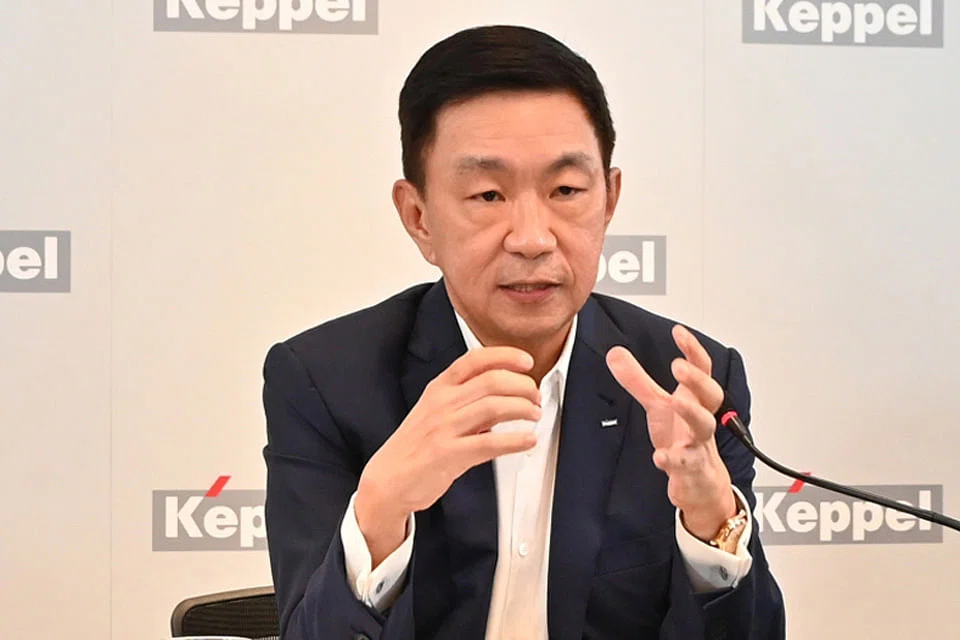
Commenting on the deals, Keppel's chief executive Loh Chin Hua said on a call on Thursday night that the O&M industry has been plagued by "very challenging conditions" over the past six years.
These include a plunge in oil prices last year, as well as a global transition away from oil to cleaner and greener forms of energy.
A large number of yards in China and Korea have also been pursuing consolidation in bid to "achieve scale", he added.
Meanwhile, Sembmarine chairman Mohd Hassan Marican said in a separate call on Thursday that the combination would allow the new entity to capitalise on growing opportunities in areas such as clean energy and renewables.
Given the scale of operations post-merger, Keppel O&M and Sembmarine could potentially see redundancies. But Mr Loh stressed that it is still too early to address the scale of this issue. Both Keppel and Sembmarine said that they intend to work with the respective unions should the need arise.
Mr Loh said that while there is "serious intent" among the relevant parties to complete the transaction, there are still a number of details to work out and this could take "a few months". He was, however, optimistic that a definitive agreement will be reached by the end of the year, most likely some time in the fourth quarter.
Market watchers cheered the announcement of the potential merger.
"This development is a positive for both Keppel and Sembmarine shareholders," said Phillip Securities analyst Terence Chua. "The merged entity will be able to benefit from both revenue and cost synergies, which will improve its odds of competing in this downturn and to ride the eventual recovery."
Mr Chua added that the resolution on Keppel's O&M unit would also remove a "major overhang" on the stock, which he believes will result in a positive re-rating of the counter.
Justin Tang, head of research for Asia at United First Partners, said that the combination was unsurprising. A merger, he added, has for some time been a question of "when and not if". "A combination of Keppel and Sembmarine had been contemplated in various shapes and forms as long ago as 2001."
Given the overlaps in the businesses of both companies and their relatively low levels of activity today, a combination would result in higher efficiency and better utilisation of resources such as labour and yard facilities.
These, said Mr Tang, would lead to economies of scale and better pricing from vendors, which would then translate into more competitive pricing for the company's clients. He also estimated that the overlaps in the likes of professional services costs and rationalisation of labour could result in cost synergies of at least S$300 million.
But Mr Tang sounded a slightly less-enthusiastic tone in comments on the Sembmarine rights issue. "That the rights are priced so low suggests that investors are not coming near this unless there is a huge discount," he said. "This is a clear sign that while Sembmarine is no longer in the intensive care unit like it was last year, it has not been given the all-clear from the doctors."
Shareholders contemplating the impact of this deal on their investments will also need to be cautious of the risks that still remain for the O&M industry.
Morningstar senior equity analyst Lee Chok Wai warned that consolidation would not necessarily bring success: "If the industry does not recover but instead starts shrinking while competition remains intense, even a merger does not promise survival."
READ MORE:
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

DBS wants to be ‘Asian bank for Asians’ rather than global bank: CEO Tan Su Shan

Ex-Goldman trader builds mini pod shop in Singapore with offbeat hires

Asean’s challenge is to become resilient against global geopolitics: former Indonesia trade minister

