

KKR sees more Asian companies tapping private credit markets
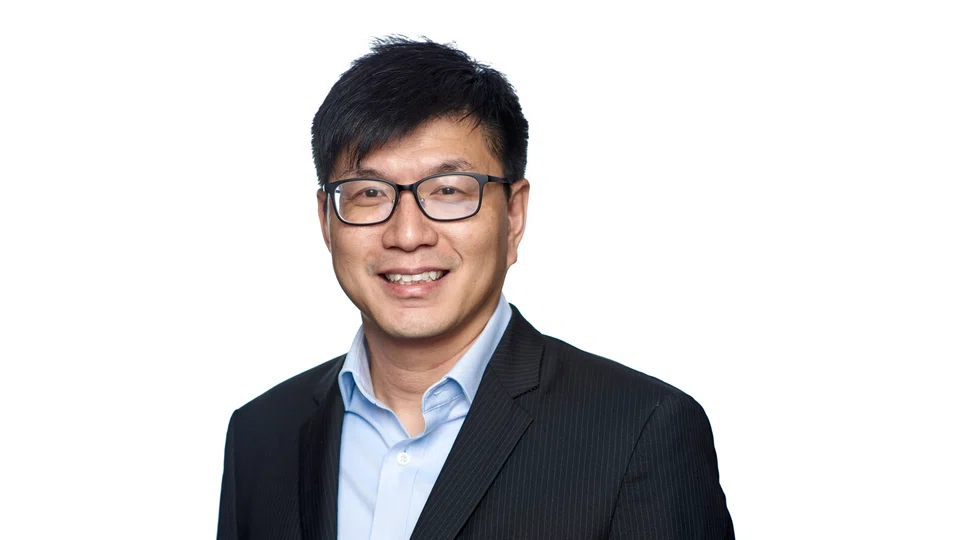
INVESTMENT group KKR sees growing demand among Asian companies for alternatives to traditional funding sources such as bank lending and equity fundraising.
According to SJ Lim, KKR’s managing director and head of South-east Asia credit, about 80 to 85 per cent of credit in Asia is provided by banks. That is much higher than the ratios of 33 per cent and 50 per cent seen in the United States and Europe, respectively.
“Often times, these companies are underserved by traditional lenders simply because banks are large, so they need to manage their flow when they work on policy manuals and frameworks, and they have a traditional way of doing things that may not always fit the situation,” he said.
In some cases, Lim added, private market credit can better meet the needs of companies.
Some companies may fail to receive bank lending because entrepreneurs decline to put up personal guarantees. Others could be cash businesses without the assets needed for collateral. Entrepreneurs who are wary of dilution or who have certain valuations in mind would also steer away from equity fundraising.
Lim offered the example of waste management company 800 Super, which was previously listed on the Singapore Exchange.
The company had approached KKR in 2018 to look for an equity partner, but KKR instead offered subordinated capital.
Lim noted that roping in KKR as an equity partner would have resulted in dilution for the Lee family, which controlled about 77.6 per cent of the company then. As a waste manager, 800 Super also had a “rock solid” business but limited growth potential.
With the backing of KKR, the family offered S$0.90 per share in cash in May 2019 to privatise 800 Super — valuing it at S$161 million. The offer price was at a 17.6 per cent premium to the company’s weighted average price per share over the 12 months prior. The company was delisted in August 2019.
KKR’s deal with the Lee family involved 800 Super issuing fixed rate bonds and convertible preference shares for subscription by KKR’s funds, including KKR’s Private Credit Opportunities II fund. KKR also received a board seat in the company.
“They are still working with KKR; it’s just that we slotted them into the right fit-for-purpose capital pool within the office,” Lim said.
There appears to be strong demand among investors, too, for private credit investment opportunities.
KKR last month announced the final close of its US$1.1 billion KKR Asia Credit Opportunities Fund (ACOF), which is focused on performing privately originated credit investments in Asia-Pacific.
The fund offers credit to companies that are performing well – hence the term performing, Lim said – and targets returns in the mid-teens, as it is meant to be a lower-risk strategy with downside protection.
Of the funds raised, more than half came from Asia, more than 20 per cent came from the Americas and close to 20 per cent came from Europe, the Middle East and Africa.
The current environment of heightened uncertainty and rising interest rates also creates more opportunities for a fund such as this, Lim said.
“In this current market, (we’re seeing) an even stronger pipeline because there’s more dislocation around; but we’ll be very cautious,” he said.
“We still want to add risk, we still think Asia is still structurally very sound… and certainly there are pockets in South-east Asia where the economies are looking very strong as well.”






