Kore manager sees silver lining in ‘minor’ Big Tech layoffs even as H2 DPU falls 12.6%
THE manager of Keppel Pacific Oak US Reit (Kore) said large-scale layoffs amid a tech sector slowdown are not a major concern for its portfolio – and might even be viewed as “somewhat positive” for the US office-focused real estate investment trust (Reit).
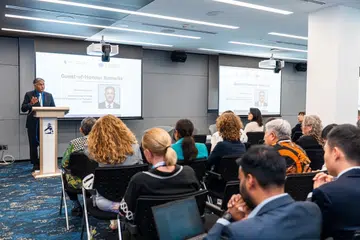
“When you look at the layoffs for these companies in Bellevue and Redmond and compare that to what their hiring has been over the last several years, you will find that it has been just a fraction of what their hiring had been,” said David Snyder, chief executive of the Reit manager, at a briefing on Wednesday (Feb 1) following its FY2022 results announcement.
“These are very minor corrections that have been made,” he added.
For example, Snyder pointed out that Amazon had 840,000 employees in March 2020, compared with 1.54 million employees in September 2022 – after the retrenchments. “Following the layoffs, they’ll still have 82 per cent more employees than three years ago,” he said.
“As odd as it sounds, we view these hiring freezes and very minor layoffs to be somewhat positive in terms of being able to get employees back to offices. Overall, for us in that market, we think that will be a plus… to get our actual physical occupancy back to where it used to be,” Snyder added.
For the second half ended Dec 31, 2022, Kore posted a distribution per unit (DPU) of US$0.0278, down 12.6 per cent from a DPU of US$0.0318 a year earlier.
Kore’s manager said the drop of 12.6 per cent was because it had elected to receive 100 per cent of its base fee for Q1 2022 in the form of units, and 100 per cent of its base fee from Q2 2022 onwards in cash.
On a like-for-like basis, assuming Q2 to Q4 2021 base fees were paid in cash rather than in units, the adjusted DPU of US$0.0278 would have been 2.8 per cent lower year on year, as compared with the adjusted DPU of US$0.0286 the year before.
Distributable income dropped 10.6 per cent year on year to US$29 million, from US$32.5 million.
Gross revenue was up 1.4 per cent to US$73.9 million for the half-year period, from US$72.9 million a year earlier.
However, net property income (NPI) fell 2 per cent to US$41.3 million for the half year, from US$42.1 million, on a 5.9 per cent increase in property expenses.
The distribution of US$0.0278 per unit for the period Jul 1 to Dec 31, 2022 will be paid out on Mar 30, after books closure on Feb 9.
For the full year, gross revenue was up 4.8 per cent to US$148 million. NPI was 1.9 per cent higher at US$84.3 million, while distributable income was down 2.9 per cent to US$60.6 million. Meanwhile, full-year DPU slipped 8.5 per cent to US$0.058.
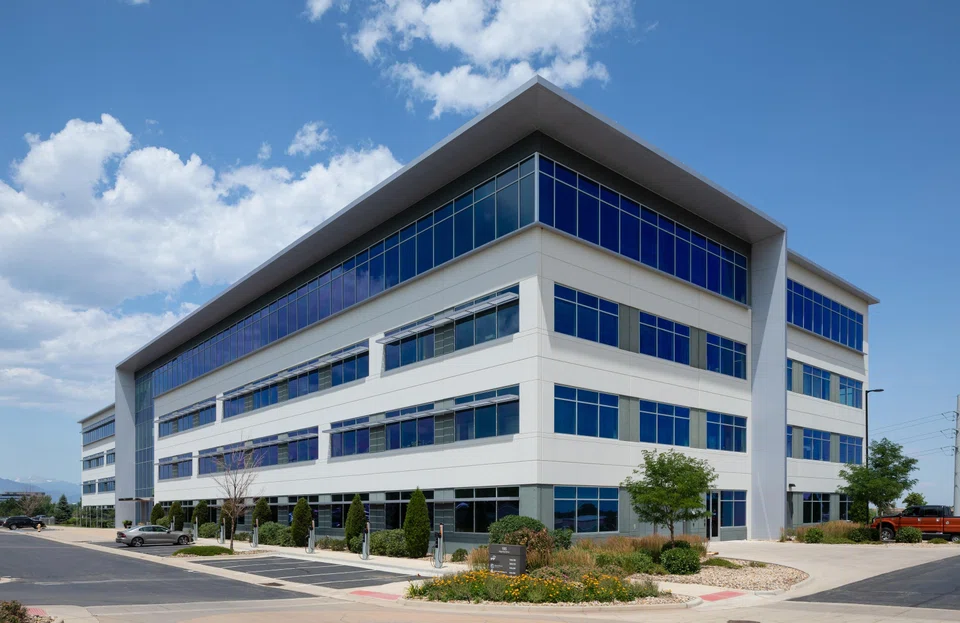
Kore’s portfolio committed occupancy increased to 92.6 per cent as at Dec 31, 2022, with 13.5 per cent of leases by cash rental income (CRI) expiring in 2023. In Q4 2022, approximately 106,495 square feet of office space was committed, equivalent to 2.2 per cent of total net lettable area.
Rental reversion remained positive at 3.8 per cent in FY2022, driven mainly by strong rents in the technology hubs of Seattle – Bellevue/Redmond, noted Kore’s manager.
About 49 per cent of Kore’s tenants operate in the growing and defensive sectors of technology, advertising, media and information; medical and healthcare. Its manager added that Seattle – Bellevue/Redmond, which constitutes 42.7 per cent of Kore’s portfolio NPI, experienced continued positive leasing momentum in H2 2022.
The weighted average lease expiry by CRI for Kore’s portfolio and top 10 tenants was 3.5 years and 4.6 years, respectively. According to the manager, tenant concentration risk, which is considered “a key unique value proposition” of Kore, remains low with the top 10 tenants accounting for only 24.3 per cent of CRI.
As at Dec 31, 2022, Kore’s all-in average cost of debt was 3.2 per cent, with aggregate leverage and interest coverage ratio at 38.2 per cent and four times respectively. The weighted average term to maturity of Kore’s debt was 3.6 years. Its manager noted that Kore has no long-term debt refinancing requirements until the fourth quarter of 2024, as loans due in November 2023 and January 2024 were refinanced back in September 2022.
Despite concerns about the US office market over inflation and recessionary fears, and the softening of the market’s office fundamentals, Kore’s manager said it “remains focused on optimising its portfolio performance, leveraging its well-located assets in key growth markets in the US, as well as exposure to the defensive sectors of technology and healthcare”.
Units of Kore closed at US$0.545 on Wednesday, up US$0.01 or 1.9 per cent, before the results release.