

KrisFlyer, KrisShop big part of SIA's growth story
Anita Gabriel
Singapore
SINGAPORE Airlines (SIA) appears to be making waves in the non-core airline business with its KrisFlyer (KF) loyalty programme notching up a handsome revenue of S$700 million in fiscal 2019 - up 18 per cent from a year ago - with a membership base of four million and counting.
This is a "very significant" growth as it comes from a big base, said SIA chief executive Goh Choon Phong at a results briefing for the media and analysts on Wednesday.
Over 70 per cent of KrisFlyer's revenue was generated from over 200 partners.
According to an SIA spokesman, KrisFlyer earns revenue from selling miles to external partners. Members are then rewarded with these miles when they purchase goods and services from these partners.
"We currently have over 200 partners where our members are able to earn KF miles or exchange partner's loyalty points to KF miles. The accumulated miles are used to redeem product and services across the SIA Group, including Scoot, KrisShop and KrisPay," the spokesman said.
The double-digit growth by KrisFlyer is part of SIA's efforts to grow its "new business segment" to drive fresh revenue streams by leveraging on the airline's brand and customer base. The other parts to this growing pie includes SIA's travel retail brand KrisShop, digital wallet KrisPay as well as pilot training centres.
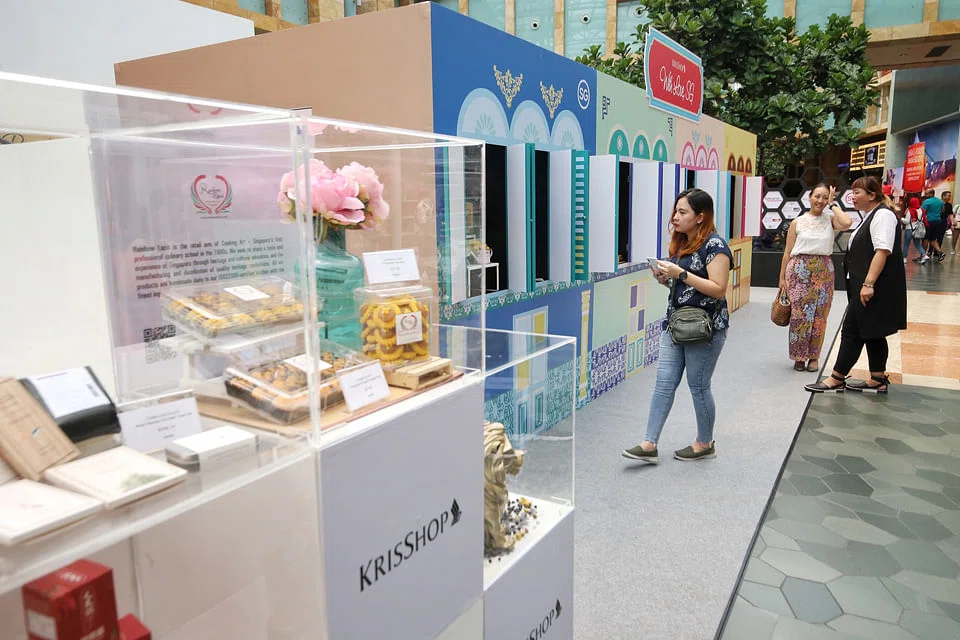
While KrisFlyer's topline is so far growing at a similar clip in the current fiscal 2020, KrisShop is doing better, albeit from a smaller base. KrisShop is no longer merely an inflight duty-free reseller; it has morphed into an omni-channel e-commerce player and is expected to see a 30 per cent year-on-year jump in revenue to S$60 million, according to Mr Goh.
Meanwhile, SIA's Airbus Asia Training Centre at Seletar Aerospace Park, which opened in 2016 and has over 50 airline clients, is also profitable, he added.
This is the first time the airline has disclosed the performance of these various segments that are part of the carrier's three-year transformation programme which aims to raise the bar on SIA's customer experience and operational efficiency plus fuel higher revenue.
SIA reported on Tuesday a 68 per cent jump in second quarter net profit to S$94 million from a year earlier, aided by better showing by associates and joint ventures on the back of a 4 per cent uptick in revenue to S$4.2 billion as passenger traffic grew across the airlines in the group.
On the operational level, higher expenditure mostly due to non-fuel costs such as higher staff costs and capacity injection dragged operating profits lower by 8.6 per cent to S$213 million for the three months to Sept 30.
The latest showing by the parent airline, with a passenger carriage growth of 8.2 per cent and RASK (revenue per available seat-kilometre) that came in 1.2 per cent higher, appears to have won over DBS Group Research analyst Paul Yong, who is positive that the group's transformation programme is paying off and will help sustain earnings recovery.
However, he expects the recovery to be more modest due to weaker performances at SIA's cargo operations, and subsidiaries Scoot and Silkair. As a result, the house has lowered its FY20 and FY21 estimates by some 15 per cent and 7 per cent, respectively.
SIA shares on Tuesday eased 25 cents, or 2.65 per cent, to S$9.18.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

If AI has a one-in-five chance of destroying us, what do we do with the remaining four?

