Lippo's troubles spell credit risks for Reits, but OUE could benefit
S&P keeping its long-term B- rating and negative outlook on the stock; Meikarta could be 'too big to fail', it says
Singapore
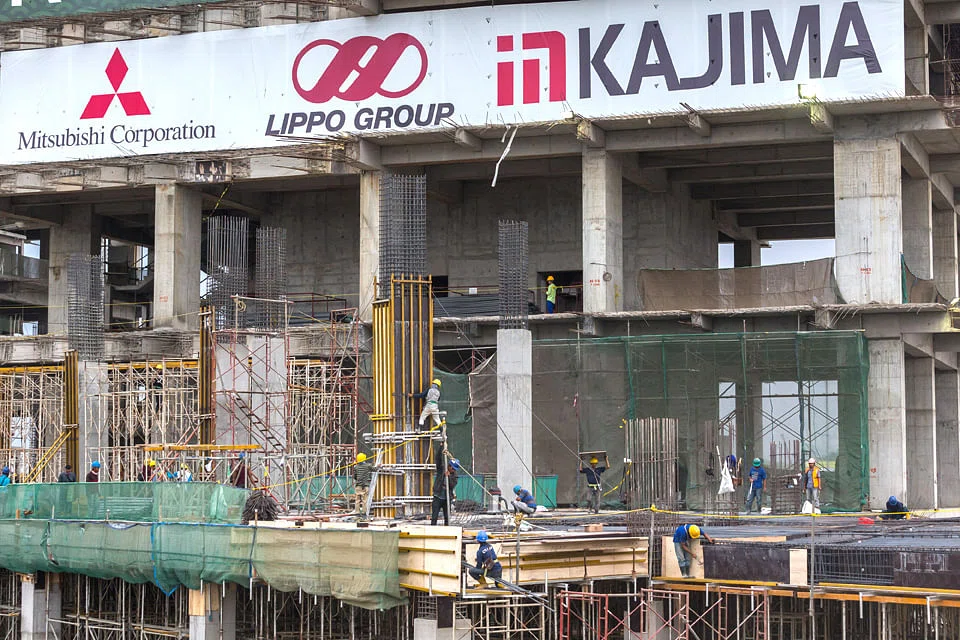
THE Indonesian authorities' probe into alleged bribery linked to the Lippo Group's US$21 billion Meikarta property project near Jakarta is unlikely to have a significant impact on Riady-linked counters listed in Singapore, analysts say.
This is largely because of how the group's Indonesia and Singapore businesses have been, for the most part, divided between the two brothers, James and Stephen Riady.
James Riady, the group's deputy chairman and the one implicated in the alleged bribery case, controls property developer Lippo Karawaci.
His brother Stephen Riady, a Hong Kong national, controls OUE, the business of which is mainly in Singapore and outside Indonesia. Stephen Riady also controls OUE-related companies such as OUE Hospitality Trust (OUEHT), OUE Commercial Reit (OUECT) and OUE Lippo Healthcare (OUELH).
Within the local listed universe, Stephen Riady also has significant interests in Healthway Medical Corporation, GSH Corporation and TIH Limited. He further owns minority interests in the Indonesian operations, and has business interests in Hong Kong under separately listed companies there.
Lippo, on the other hand, controls Lippo Malls Indonesia Retail Trust (LMIRT) and First Reit. First Reit is pending the completed sale of its manager and a 10.6 per cent stake in the Reit to OUE and OUELH.
The Business Times understands that the "decoupling" of Lippo Karawaci and OUE was a deliberate move by the brothers' father Mochtar Riady, founder and chairman of the Lippo Group, to minimise family conflict and to ringfence contagion in case either side is hit by an adverse event.
Asked about the impact of the probe on the Singapore counters, Moody's senior analyst Jacintha Poh said: "We should look at (the alleged bribery) more in isolation and not try to draw links to other entities under them... There is also quite a distant linkage between Lippo Karawaci and OUE; the only link is that they are owned by the same family. There is little or no cross ownership."
Still, shares of OUE, OUEHT and OUELH have fallen 5.5 per cent, 4.3 per cent and 2.9 per cent respectively since the news broke. Share prices of OUECT and LMIRT have been flat; that of First Reit has risen 3.4 per cent.
On Thursday, S&P Global Ratings issued a report saying that Lippo Karawaci's decision to deconsolidate its flagship Meikarta project from its accounts will weaken the Indonesian developer's business position in the long run because it is the group's largest property development.
Lippo executives were arrested on charges of bribing officials to get permits for the mega-project on Oct 15. S&P believes the deconsolidation will result in Meikarta leveraging up independently - although obtaining funding in the near term may be a challenge until bribery allegations are resolved.
That said, S&P is not changing its long-term B- rating and negative outlook on the stock because this does not alter Lippo's liquidity at the holding company level. Also, given its size and reputation risk to the entire group, S&P believes this project could be "too big to fail" and expects Lippo to support it when necessary.
S&P added that Lippo Karawaci's cash outflows for the 12 months ending June 2019 include interest expenses of about 1 trillion rupiah (S$90.8 million) and construction costs and rental expenses of about 1.1 trillion rupiah.
"We believe Lippo will also need to maintain cash of 800 billion rupiah at the holding company, in line with its loan covenant. Hence the recent sale of its stake in First Reit...will be complete in November 2018, and will shore up liquidity at the holding company by S$202 million."
If any impact is to be felt by Lippo-related companies here, analysts say First Reit and LMIRT may face credit risks, given their reliance on related parties as rental-contributing tenants. Meanwhile, OUE could benefit from Lippo Karawaci's asset sales at attractive valuations.
Phillip Capital analyst Tara Wong said Lippo Karawaci contributed about 83 per cent of First Reit's gross rental income in FY17. Most of First Reit's properties are master leased to Lippo Karawaci, though the properties are used by its subsidiary Siloam International Hospitals for its day-to-day healthcare operations.
She is hopeful that Lippo Karawaci's cash proceeds from selling its stake in First Reit and the manager "could have a positive spillover effect into rentals owed" to the Reit. In a September report, she said although Lippo Karawaci has been paying up more slowly than usual, it has so far not defaulted on its rental payments.
Therefore, the concern is that if the Meikarta project cannot be completed on schedule because of the investigations, the Reit's counterparty credit risk could be affected. Already, credit analysts have voiced concerns over the sustainability of the Meikarta project, in terms of its sales as well as its funding concerns.
Moody's has said that the alleged bribery case could cause reputational damage that will hurt both investor and consumer confidence. It could also drive up the yield-to-maturity on the company's outstanding US dollar bonds, which means that Lippo Karawaci would have to pay more interest when it refinances its debt due over the next 12 to 18 months.
As for LMIRT, OCBC had in May and August this year flagged credit risks for the Reit, as a third of its revenue is contributed by Lippo-related entities, which could create a problem if they pull out because of Lippo Karawaci's liquidity problems.
On the brighter side for Singapore investors, Lippo Karawaci's liquidity concerns could lead to more asset sales on the cheap to OUE.
One example is the proposed sale of the manager of First Reit at a valuation of about 9.6 times audited profit after tax for FY17. Reit managers generally do not disclose their financials, but this price was "a steal" compared to the sale of the manager of Viva Industrial Trust to ESR-Reit at 12 to 15 times, said one analyst.
To be sure, Lippo Karawaci is just one of the many businesses under the Lippo Group, which also include department stores, e-payments and healthcare - and which happen to be doing better.
Amid the probe, stock prices of Lippo Cikarang and Lippo Karawaci soared on Wednesday after both companies reported increases in their first-half earnings.
Lippo Cikarang, which owns a 49.99 per cent in the holding company of the Meikarta project, finished 12 per cent higher; shares of Lippo Karawaci rose as much as 6 per cent intra-day,and then finished 2.7 per cent higher.