Manulife US Reit blames price fall on fund sell-off, private bank margin calls
Singapore
THE manager for Manulife US Real Estate Investment Trust blames the Reit's "horrific" price drop, which "wiped out four years of work", on mass selling by index funds and exchange traded funds, margin calls from private banks, and funds redemption and switching to other counters amid rising volatility due to the US Covid-19 situation.
Year to date, Manulife US Reit units are down 30 per cent, in line with the FTSE ST Reit Index but steeper than the 27 per cent retreat by the Straits Times Index. In the US, Reits are down about 40 per cent.
On Monday, Manulife US Reit had nearly halved over the past two weeks. In a teleconference call with media and analysts on Tuesday, its management team tried to inspire confidence in the Reit by affirming that its leases are secure despite tenants working from home temporarily and some tenants downsizing. The Reit is nowhere near breaking any financial covenants either.
Robert Wong, chief financial officer of the Reit manager, said that in terms of key financial covenants with the banks, the Reit has sufficient buffer to weather the turbulences. For illustration's sake, Ebitda has to drop by more than 50 per cent and valuation has to fall by 16 per cent, before the respective interest coverage ratio and gearing cap of 45 per cent becomes an issue.
He added that the Reit's key relationships with banks remain supportive, providing opportunities on financing options in the low interest rate environment, although no acquisition is likely in the near term.
The Reit has eight prime, freehold and trophy or class A quality office properties in California, Atlanta, New Jersey and the Washington, DC metro area.
In response to the Covid-19 pandemic, New Jersey and California states have been locked down, and state governors in Washington DC and Virginia have urged people to stay home as much as possible. Atlanta has not been officially shut down but "the writing is on the wall and should be happening any time now", said portfolio manager Quazi Sadruzzaman.
He added that Manulife US Reit's properties come with no break clause. "Our tenants are required to fulfil their lease obligations; there is no way around it."
He said no tenant has asked for rent relief yet, except for its F&B tenants which make up about one per cent of its portfolio. The manager is looking at their requests on a case by case basis.
There are also no tenants in arrears currently. Any tenant that is 60 days behind their rent payments may be considered to be in default, but Mr Sadruzzaman said the manager will work closely to help them navigate through their difficulties. In the event of a default, the Reit may draw down on the tenants' security deposits.
As at March 13, the portfolio has an occupancy of 96.4 per cent and weighted average lease expiry of 5.7 years. The Reit's portfolio also has low lease expiries in FY2020 and FY2021.
Jill Smith, CEO of the Reit manager, said that the sponsor is limited in its ability to buy back units to bolster prices, given the regulation which disallows any unitholder from holding more than a 9.8 per cent stake in the Reit. The sponsor already owns 8.6 per cent of the Reit. Hence, it is opting instead to allow directors to buy units - and they have done so in the past week - and to agree to have their fees paid in units.
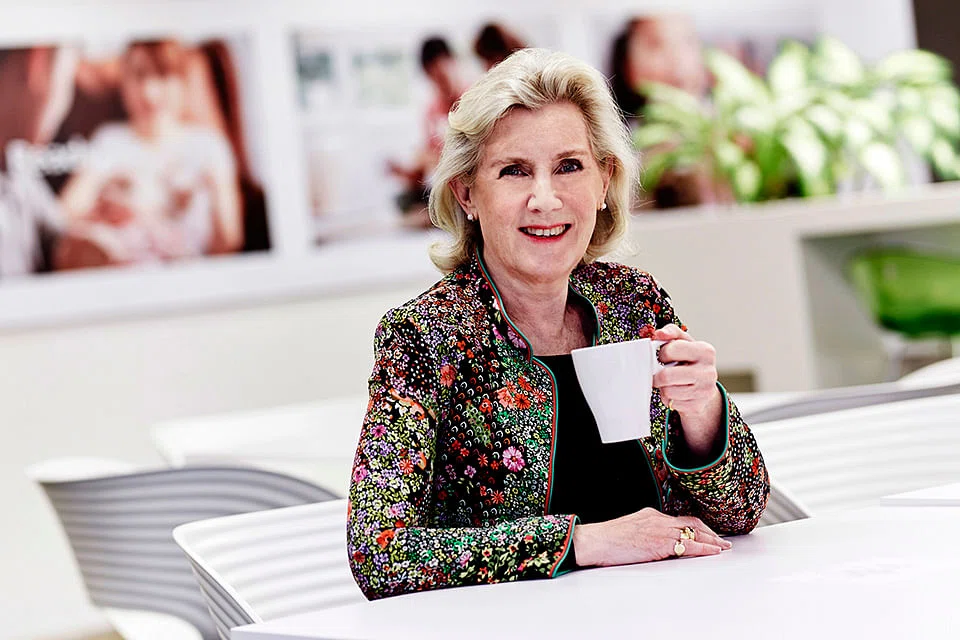
Ms Smith confessed to being worried about the length of time that Covid-19 will take to work through the US. Compared to the global financial crisis, "this is taking place in a very compressed and rather shocking timeline" and will be a "race" for the US to "lock itself down" and "flatten the Covid-19 case curve". Only then can the situation improve and the economy bounce back.
Meanwhile, chief investment officer Jennifer Schillaci expects leasing prospects to be slow in the short term, as most industries will be hitting a pause button and tenants will prefer to take a wait-and-see attitude until there is more clarity.
"The GFC was an 18-month recession, it was a deep recession with (a) long recovery (period). But this is expected to be short-term, front-loaded pain with a sharp rebound. The (Covid-19) event here is being calculated in months rather than years."
She added that the fact that the situation is improving in China also brings optimism that the pandemic in the US could bounce back faster than the GFC.
Meanwhile, in response to queries about whether the drop in unit price will cause the Reit to exit the FTSE EPRA Nareit Global Developed Index that it had just joined late last year, management said this is not likely as its market cap criteria is also based on how the basket of 80 or so stocks is performing, and the Reit's performance has been in line with other constituents. It is also holding up well in terms of trading liquidity.
Most analysts are maintaining their confidence in the Reit. RHB analyst Vijay Natarajan said: "Looking at the balance sheet, the gearing is also modest at 37.7 per cent, with a reasonably spread out debt maturity profile."
DBS analyst Rachel Tan said: "After prices almost halved from their peak, valuations are looking very attractive and possibly have priced in some impact from the recession. However, prices may still be volatile as they tend to trade in tandem with the US market or sentiment on the US economy."