

Manulife US Reit’s manager ‘surprised’ by deep decline in valuations; breach of covenants may affect H1 distribution
Raphael Lim &
Vivienne Tay
THE manager of Manulife US Real Estate Investment Trust (Reit) said it was “surprised” by the sharp decline in portfolio valuations that caused a breach of loan covenants, potentially affecting distributions.
“We were surprised at how deeply they had come down,” said Tripp Gantt, chief executive of the manager at a briefing on Tuesday (Jul 18), after it announced that the Reit’s real estate portfolio valuation had declined by 14.6 per cent to US$1.6 billion as at June 30, 2023.
“The different indices that we were looking at, the different information sources we were looking at to kind of gauge where we were in terms of valuations were mixed, but none of them pointed to where our valuation declines would be at mid-year,” he added.
The decline in valuations was due to several factors including higher discount rates and terminal capitalisation rates, as well as continued weakening of occupancy performance across the US office market. The Reit is expected to report a loss in the first half of 2023. Manulife US Reit’s aggregate leverage has risen to 57 per cent following the new set of valuations, passing the 50 per cent limit set by the Monetary Authority of Singapore (MAS).
The manager noted there is no gearing limit breach as the circumstances that led to the exceeding of the limit were beyond the manager’s control.
The Reit, however, has breached a financial covenant in some of its financing documents relating to the ratio of unencumbered debt to unencumbered assets.
Its existing loans contain a financial covenant stating that the Reit must at all times ensure its ratio of consolidated total unencumbered debt to consolidated total unencumbered assets was no more than 60:100. With the updated valuations, this ratio has changed to 60.2:100.
“One of the impacts … is a potential impact to our distributions for the first half of 2023. It’s unclear to us at the moment whether we’ll be able to make those distributions,” Gantt said, adding that the manager is addressing this with its legal and accounting team.
If distributions cannot be declared, there may be an impact on the structure of the Reit, which would result in additional taxes being required to be paid. The manager is also seeking advice from a US tax adviser.
The breach of the financial covenant would also result in a cross default of the Reit’s interest rate swaps, potentially resulting in higher interest rates for its loans and affecting the interest coverage ratio.
The manager is in discussions with its lenders to seek their waiver for the breach, and is working on potential solutions. Gantt said: “Since we are close – we’re at 60.2 per cent – our objective is to try to get that down below 60 per cent in the short term.”
Over the mid-to-long term, Manulife US Reit would continue to look at ways to raise proceeds to pay down debt.
“We’re continuing to work with the sponsor on some sponsor support – the Phipps transaction – or a potential alternative that would bring in proceeds,” he said.
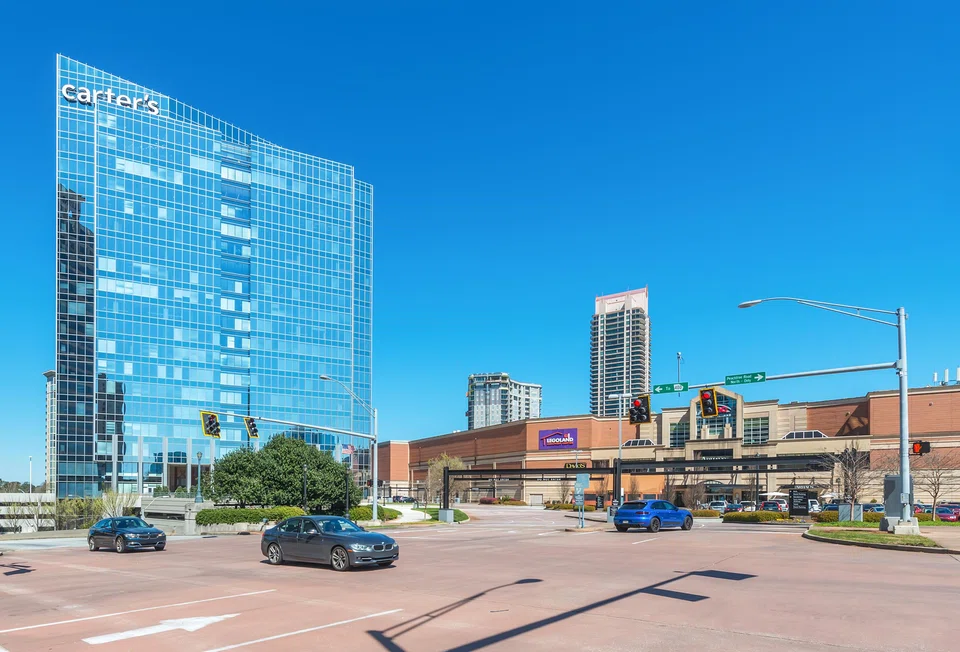
Manulife US Reit said in May that it entered into a letter of intent to sell Phipps Tower in Atlanta, Georgia, to an affiliate of its sponsor. Discussions for this are still ongoing but the Reit’s aggregate leverage would still remain above 50 per cent even if all proceeds from the sale are used to repay loans.
The manager and sponsor are also “actively exploring a potential alternative method which may work to address Manulife US Reit’s mid- and long-term liquidity needs”. Gantt noted that property sales are one possibility. Another alternative could be some form of lending, in order to pay down debt.
Besides sponsor support, Manulife US Reit is also exploring the disposal of assets, and it may seek a “disposition mandate” from unitholders. This would allow the Reit the flexibility to dispose of certain assets as long as certain conditions are met. The manager said it is still in the midst of drafting the disposition mandate and would provide more details when ready.
Darren Chan, research analyst at Phillip Securities, said the mandate would be helpful to speed up the process, as buyers are less willing to wait for an extraordinary general meeting to proceed with a purchase.
He added that equity fund raising at the current price is “highly unlikely” for Manulife US Reit.
“The US office market remains challenging with slower leasing volumes and higher vacancies,” Chan said. “As a result, the other US office Reits might face valuation declines as well, but we think to a lesser extent due to the location of the properties.”
In terms of why the manager decided to take on a fresh valuation of assets at this point in time, Gantt said that they “took the initiative” to do this once they had indications that valuations were going to be down to an extent greater than they thought.
“Obviously we’re facing the music earlier than we might have had to otherwise,” he said. “But I think that both the regulators and the banks appreciate that we are being very open, and the conversations today have been consultative and cooperative, and we are going to continue that and find a solution here together.”
Manulife US Reit units closed at US$0.169 on Monday, before a trading halt was called on Tuesday.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB likely to benefit more

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

From Haidilao to Oriental Kopi: How some of Asia’s favourite F&B players are faring in 2026

Floods compound Philippine growth woes from public-works scandal

