

Manulife US Reit gearing a whisker shy of 50% regulatory limit after asset valuation decline
THE real estate valuation of Manulife US Real Estate Investment Trust (Manulife US Reit)‘s portfolio has fallen by 10.9 per cent to US$1.9 billion, from US$2.2 billion as at end-2021.
This was attributed to higher discount rates and capitalisation rates for certain properties. The manager said this was reflective of risks posed by a volatile macroeconomic environment as well as idiosyncratic risks at the property level, such as higher vacancy or weak submarket fundamentals.
The decline in valuation was also due to continued weakening of occupational performance in submarkets where the properties are located, said the manager on Friday (Dec 30).
It explained that a slowdown in demand and leasing activity had led to rising concession package assumptions to attract new or retain tenants, which resulted in higher leasing costs.
“(The decline in valuations) was largely due to the challenging market dynamics in our submarkets,” Tripp Gantt, chief executive officer of the manager of Manulife US Reit, said at a briefing following the announcement.
For example, Gantt pointed out that at the Reit’s Figueroa building, terminal cap rates used in the appraisal increased by 100 basis points (bps) while discount rates used in the discounted cash flow analysis rose by 150 bps.
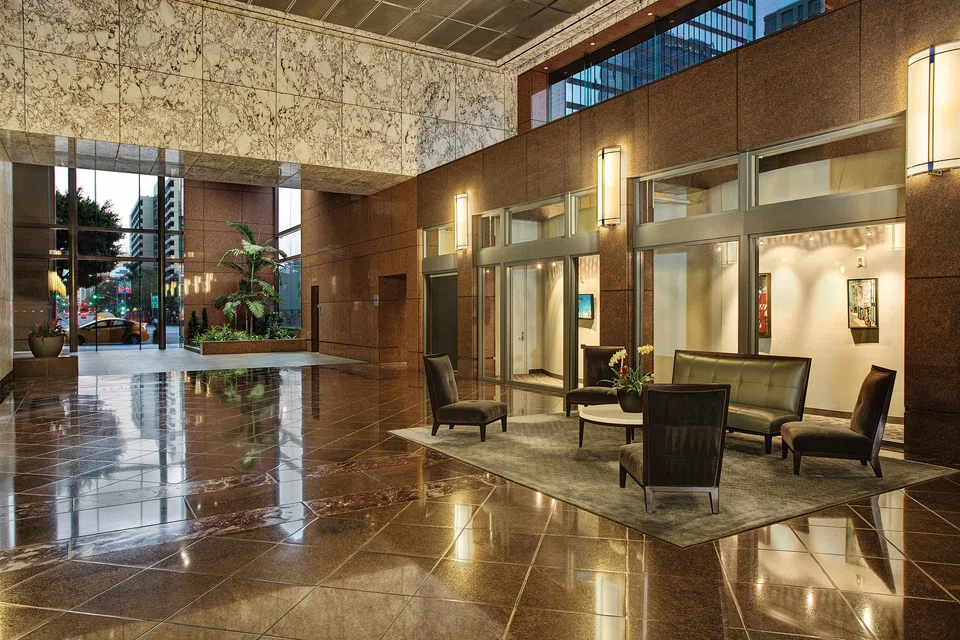
Figueroa saw the largest decline in valuation compared with the rest of the properties in the Reit’s portfolio, down 33.1 per cent to US$211 million as at end-2022, compared with US$315.2 million the year before. The Grade A office building in Los Angeles made up 44 per cent of the portfolio valuation decline for the period.
According to the manager, Figueroa’s valuation plunge was largely due to a shift in occupancy plans of two of its largest tenants, Quinn Emanuel and TCW Group. The former has executed a renewal and downsize, while the latter plans to vacate at the end of its lease term by end-December 2023.
The lower portfolio asset valuation brings Manulife US Reit’s aggregate leverage to 49 per cent – just slightly under the 50 per cent limit for Singapore Reits imposed by the Monetary Authority of Singapore, if the Reit has a minimum adjusted interest coverage ratio of 2.5 times.
Manulife US Reit’s projected interest coverage ratio as at end-December will be about 3.1 times.
Net asset value is projected to fall by US$237.4 million, or US$0.13 per unit.
In its bourse filing, the manager assured that financial covenants in respect of the Reit’s existing loans are not expected to be breached, despite the decline in valuation.
The Reit manager added that it is exploring options to reduce the aggregate leverage.
“We are absolutely prioritising dispositions right now,” Gantt said. “We’ve actually been actively looking at this for quite some time. We’re in that process now and our intent is to execute a disposition as soon as possible.”
However, he added that transaction markets are likely to thaw out only when interest rates start stabilising.
“It’s a difficult time to be selling properties in the US right now,” Gantt said. “The markets are frozen right now because banks aren’t lending – they’re waiting to see where things settle out – and borrowers obviously need that money and that debt to execute transactions.”
The Reit manager added that it would need to raise US$170 million to pay down debt, in order to bring its aggregate leverage down to 45 per cent.
Units of Manulife US Reit ended 3.2 per cent or US$0.01 lower at US$0.30 on Friday.






