Mapletree Logistics Trust posts Q2 DPU up 5.7% to S$0.02173; manager eyes 'substantial' acquisitions
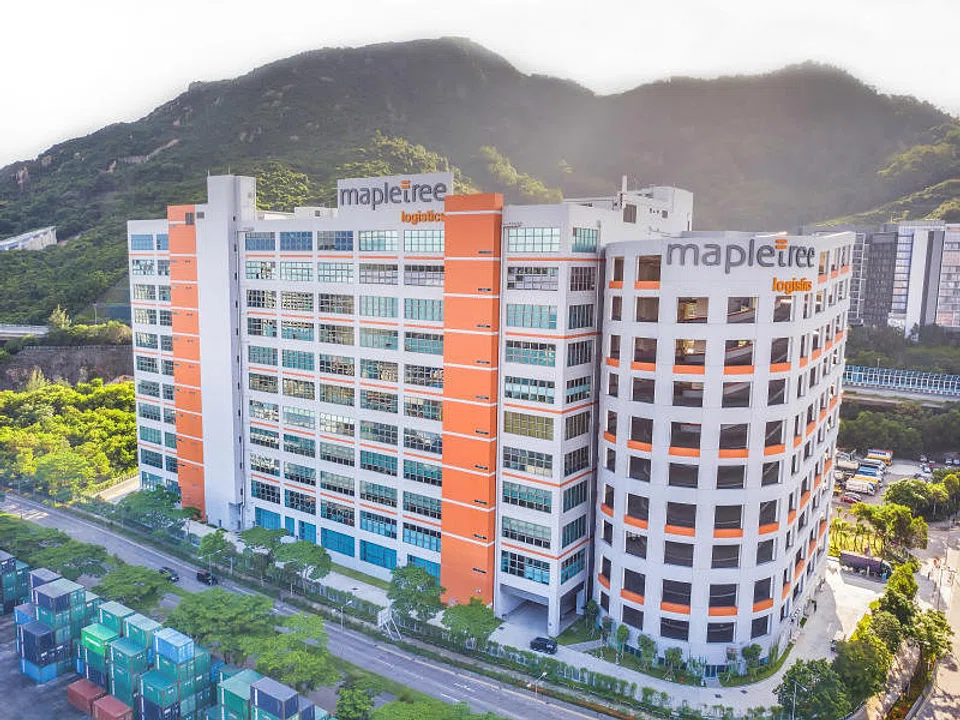
THE manager of Mapletree Logistics Trust (MLT) M44U on Monday said total acquisition value for the FY21/22 ended March 2022 is expected to be "substantial" as the real estate investment trust (Reit) seeks to continue to fuel its growth.
"Last year, we did acquisitions of about S$1.6 billion. This year, hopefully, we can still do something around that range," said Ng Kiat, chief executive officer of the manager, at a briefing following the release of its Q2 results after market close on Monday.
Apart from assets in China, Vietnam and Malaysia from its sponsor's pipeline, Ng said the Reit is also looking to acquire properties in Japan, Australia and Korea.
"We are expecting a fairly large deal coming up from Japan," Ng said. "We are in the process of hopefully closing a deal soon, over the next one month or so. That should be quite a nice property with a sizable gross floor area (GFA)."
Ng added that this Japan property acquisition is "larger than expected" and is expected to be "a good addition" to the MLT portfolio.
"In line with our strategy to strengthen our regional footprint, we have recently announced the proposed acquisitions of three modern logistics assets in Australia, Malaysia and South Korea. We will continue to focus on building up a quality portfolio and scaling up our network presence to capture opportunities in the logistics market," she said.
At the same time, the manager said MLT is also looking to divest some of its smaller logistics properties with poorer specifications in the later part of this year or in the early part of next year.
MLT's financial performance for the second quarter to September had been boosted by contributions from accretive acquisitions completed in FY20/21, higher revenue from existing properties and higher occupancy from a logistics park.
Mapletree Logistics Trust Management, MLT's manager, reported on Oct 25 that the trust's distributable income rose 19.2 per cent year-on-year to S$93.4 million in Q2.
Its distribution per unit (DPU) grew 5.7 per cent to 2.173 Singapore cents - payable on Dec 14 - despite having an enlarged unit base due to the equity fund raising completed in Q3 last year.
Gross revenue was S$165.1 million, after an increase of 25.2 per cent year-on-year. Net property income, reported MLT's manager, was 21.5 per cent higher at S$144.4 million.
It added that 91 per cent of leases that were due for expiry have been renewed or replaced, while the weighted average lease expiry for its portfolio of 163 properties is approximately 3.7 years with portfolio occupancy at 97.8 per cent.
It has achieved a rental reversion of approximately 2.4 per cent on average, contributed by renewal or replacement leases from across almost all of its markets.
Its weighted average borrowing cost was unchanged at 2.2 per cent per annum, with the aggregate leverage standing at 38.2 per cent as at end-September. MLT's manager said available credit facilities on hand showed that the trust has more than sufficient liquidity to meet its maturing debt obligations in this financial year FY 2022.
MLT has a debt maturity profile with an average debt duration of 3.6 years, while about 76 per cent of its total debt has been hedged into fixed rates, and about the same proportion of income stream for the next 12 months has been hedged into Singapore dollar.
MTL's half-year financial results showed the trust has improved 19.2 per cent in its distributable income to S$186.1 million from S$156.1 million a year ago.
Gross revenue also jumped by about 24.4 per cent to S$328.8 million from S$264.2 million, while net property income rose 21.4 per cent to S$288.6 million from S$237.7 million.
Units of the trust closed S$0.01 or 0.5 per cent higher at S$1.99 on Oct 25, before the financial results were released.
READ MORE
- Mapletree Logistics Trust to acquire facility in South Korea for 135b won
- Mapletree Logistics Trust unit enters new agreement to acquire logistics facility in Malaysia
- Mapletree Logistics Trust to buy cold-storage facility in Melbourne for A$42.8m