Mapletree Logistics Trust's latest acquisitions, equity raising could sow doubt among investors
Meagre 2.2 per cent DPU accretion from proposed 17-asset acquisition likely to be diluted by placement and preferential offering
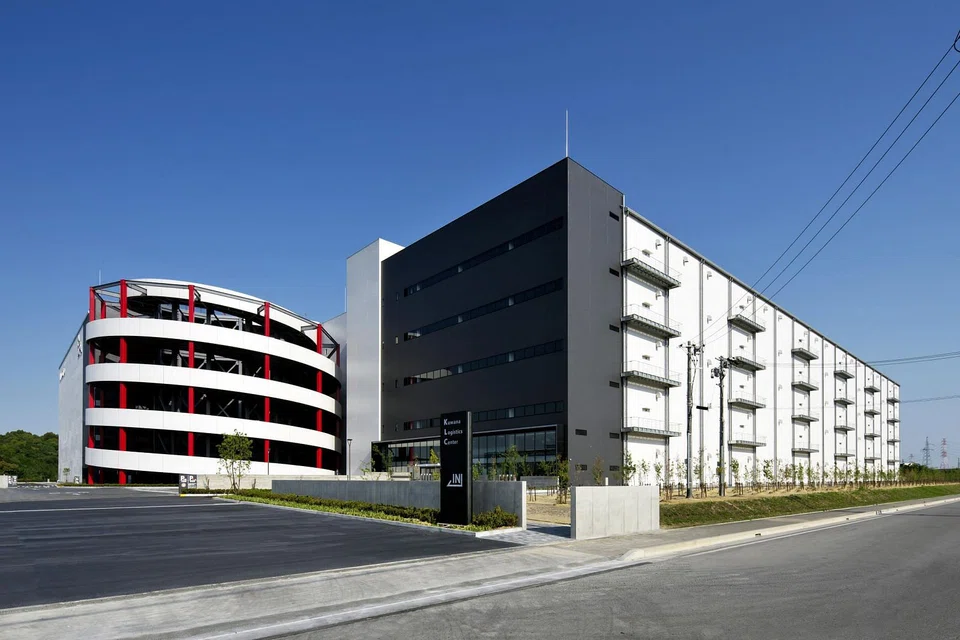
MAPLETREE Logistics Trust (MLT) does not appear to be the sort of real estate investment trust (Reit) that would face much difficulty raising capital to acquire assets and expand its property portfolio.
With Mapletree Investments as its sponsor, MLT theoretically has access to a "pipeline" of high-quality assets across the region.
MLT's units have also held up relatively well through the pandemic, ostensibly putting it in a good position to tap investors for equity capital.
From the beginning of 2020 to Dec 10, MLT has delivered a total return of 19.5 per cent (on a distributions reinvested basis). The Straits Times Index and the FTSE ST Reit Index have returned 4.6 per cent and 0.7 per cent, respectively.
Yet, a close reading of MLT's announcements over the past month might leave some investors doubting its supposed ability to raise funds and make acquisitions on attractive terms; and disappointed about the manner in which it has justified these transactions.
On Nov 22, MLT's manager said it plans to purchase 17 modern Grade-A logistics assets - 13 of which are in China, 3 in Vietnam and 1 in Japan - for S$1.47 billion, including acquisition-related expenses.
The manager of MLT said the acquisition is expected to be financed through a combination of equity and debt.
The Mapletree Investments group, as a vendor of the assets in China and Vietnam, has agreed to receive part of the consideration for those assets in the form of new MLT units.
MLT's manager said on Nov 22 that the precise funding structure was yet to be decided, but that the acquisitions are expected to be accretive to MLT's distribution per unit (DPU) and its net asset value (NAV) per unit.
Specifically, MLT's manager stated in a presentation deck dated Nov 22 that the Reit's DPU for FY2021 ended Mar 30 would have been boosted by 2.2 per cent on a pro forma basis - from S$0.08326 to S$0.08511.
MLT's NAV per share would have been lifted by about 4 per cent - from S$1.33 to S$1.38.
Pro forma assumptions
These pro forma figures, however, were based on assumptions that may give investors pause.
For one thing, MLT's manager stated that the acquisition of the Japan-based property alone would lift its pro forma DPU from S$0.08326 to S$0.08409.
But that assumes the Japan-based asset had an occupancy rate of 100 per cent. As at Nov 11, the property had an occupancy rate of 82.5 per cent.
Based on an occupancy rate of 82.5 per cent, the Japan-based asset would lift MLT's pro forma DPU from S$0.08326 to only S$0.08341.
Separately, MLT's manager said 7 of the China-based properties the Reit is to acquire are currently "undergoing stabilisation", and will receive income support of up to RMB20.9 million (or S$4.4 million) for a period of 1 year.
This income support was included in the overall pro forma DPU of S$0.08511. Without the income support, the overall pro forma DPU would have been S$0.08409 - that is, unchanged from the pro forma DPU reflecting the acquisition of the Japan-based asset.
Furthermore, one key underlying assumption of the pro forma figures is that all the units MLT will issue will be priced at S$1.92 each.
On Nov 23 - only 1 day after announcing the acquisitions - MLT's manager launched a S$700 million equity fundraising exercise, comprising a placement to be priced between S$1.86 and S$1.911 per unit and a preferential offering to be priced between S$1.82 and S$1.87 per unit.
MLT's manager subsequently said S$400 million had been raised through the placement of nearly 212.8 million new units at S$1.88 each. A further S$292.8 million will be raised through a preferential offering of 159.1 million new units at S$1.84 each.
Given the lower price at which MLT is issuing units in its equity fundraising exercise, it seems logical to me that the actual accretion in DPU will fall short of the pro forma DPU used to justify the acquisitions.
In fact, given that the overall pro forma DPU accretion was only 2.2 per cent, I cannot help but wonder if the acquisitions will deliver any immediate DPU uplift at all.
Questions raised
The fundamental issue here is not just that the assumptions behind MLT's pro forma DPU and NAV per share might have been too optimistic.
Among the questions investors should ask are: Did MLT's manager know that the price range for the placement and preferential offering was going to be less than S$1.92 when it announced the acquisitions?
Should MLT have even been allowed to launch a placement at a price range that did not encompass S$1.92?
Would MLT's manager have been able to justify the proposed acquisitions under the assumption that the Reit would raise equity at less than S$1.92 per unit?
The pro forma DPU and NAV per share figures that Reit managers provide when they propose acquisitions are not forecasts. And, acquisitions that do not result in a higher pro forma DPU or NAV per share could well prove to be attractive deals over the long term.
Investors are, nevertheless, comforted when acquisitions result in even a marginal improvement in a Reit's pro forma DPU and NAV per share - as it suggests that the market value of the Reit's units should not fall in the wake of the deal.
For Reit managers, being able to show that an acquisition and accompanying equity raising exercise would boost the Reit's pro forma DPU and NAV per share is an important means of justifying the whole deal.
Unfortunately, by giving investors reason to doubt that its proposed acquisitions will be immediately accretive, MLT's manager might have made it harder for the market value of Reit's units to gain traction as it pursues the rest of its equity fundraising plans.
It might also have made investors nervous about its future acquisitions and equity fundraising exercises.
MLT closed Friday at S$1.90.
For more on recent acquisitions and placements by Singapore-listed Reits, download the latest Mark To Market podcast at: bt.sg/mark2mkt