

Margin relief lifts outlook for DBS, OCBC and UOB, extending Singapore bank rally
Sentiment remains largely positive on the sector amid resilient asset quality, steady capital returns
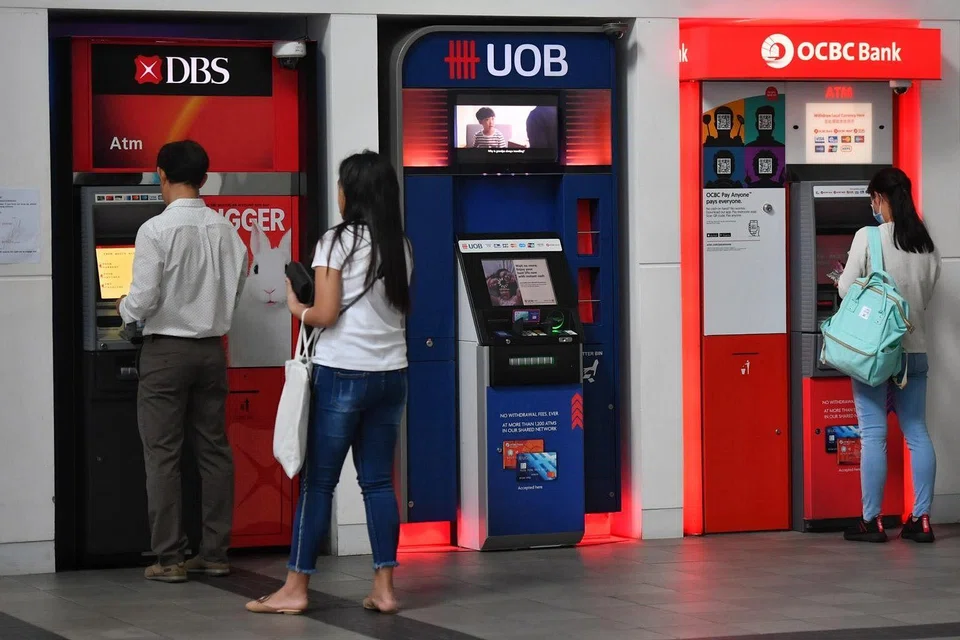
[SINGAPORE] The three local banks may be nearing the end of the margin squeeze that has weighed on earnings over the past year, as interest rates stabilise and funding pressures ease, analysts said.
Ahead of the banks’ fourth-quarter results, sentiment remains largely positive on the sector, supported by resilient asset quality and steady capital returns, but analysts caution that clear growth drivers for the next stage of growth remain elusive.
The banking trio are set to release their fourth-quarter and full-year 2025 results in February, beginning with DBS on the 9th, then UOB on the 24th and OCBC on the 25th.
Lim Rui Wen, analyst at DBS Group Research, noted that Singdollar short-term rates appear to be bottoming out, having held steady even as the US delivered further rate cuts in late 2025.
In the longer term, rates may rise as investors rethink the “sell America” or “rebalancing” trade, she said.
“Coupled with the ongoing repricing of flagship current accounts, wholesale and fixed deposits, we believe these factors will culminate in a turning point for the net interest margin (NIM) downtrend.”
Funding costs are also set to retreat further in 2026, due to abundant liquidity and the flow-through of deposit-rate cuts against modest loan demand, said Rena Kwok, senior credit analyst at Bloomberg Intelligence (BI).
Meanwhile, non-interest income will likely be seasonally softer in Q4, analysts said.
Overall trading income should be supported by high levels of volatility, however, especially from client flows, said Maybank Securities’ head of research Thilan Wickramasinghe.
Among the three, OCBC may bear the least loss in momentum due to support from loan fees as well as brokerage income, he said.
UOB could also reap improved credit card fees following a low base, he added.
Further legs
Lim expects further legs in the rally, as dividends and stable capital returns remain attractive.
In 2025, shares of DBS rose 28 per cent and OCBC was up 19 per cent. UOB fell 4 per cent, weighed by earnings disappointment and concerns over asset quality in Q3.
Lim said ongoing fund inflows – as a result of the Singdollar being a safe haven – should continue to benefit Singapore banks as earnings remain resilient.
Deployment of Equity Market Development Programme (EQDP) funds are also tailwinds for the sector, she added.
BI’s Kwok added that healthy capital levels through 2026, supported by resilient earnings, could result in more active capital management and shareholder returns.
Still, the Singapore research team at RHB expects modest returns for the sector ahead, citing the lack of drivers for higher returns on equity and share price outperformance against peers in Malaysia and Indonesia in 2025.
They noted that DBS’ rally was driven by dividend visibility and attractive yields; with OCBC, investors were optimistic about its wealth management prospects and room for further capital returns.
DBS’ Lim also warned that it may be premature to conclude that UOB’s asset-quality issues are entirely resolved.
The bank has a relatively larger exposure to US commercial real estate compared to its peers, and the remaining book of Greater China real estate exposures.
Even so, the RHB team noted positives for the sector, including a sanguine macroeconomic backdrop, wealth management businesses that should benefit amid a low interest rate environment, positive investor sentiment, continued inflows, and stable asset quality.
Looking ahead to 2026, BI’s Kwok said asset quality should remain sound despite tariff uncertainties and pockets of stress in overseas commercial real estate.
This is driven by prudent provisioning, strong underwriting and risk controls, with no signs of major stress among small and medium-sized enterprises, unsecured retail, or commercial real estate portfolios so far.
Meanwhile, non-interest income will likely remain a key driver of operating income, said the RHB analysts.
Domestic loans demand will likely “stay decent” as a lower rates environment should bode well for mortgages and non-trade corporate loans, while the wealth management business is a key driver for fees, RHB said.
However, a modest loan growth and some NIM pressure should also keep net interest income muted for 2026, it added.
On Thursday, shares of DBS closed 0.6 per cent higher at S$59.66, OCBC was up 0.1 per cent to S$21.45, and UOB ended 0.2 per cent higher at S$38.65.






