

MariBank taps Sea’s ecosystem to build regional banking group from Singapore
This edge is even more important now as digital bank seeks to differentiate itself from traditional lenders
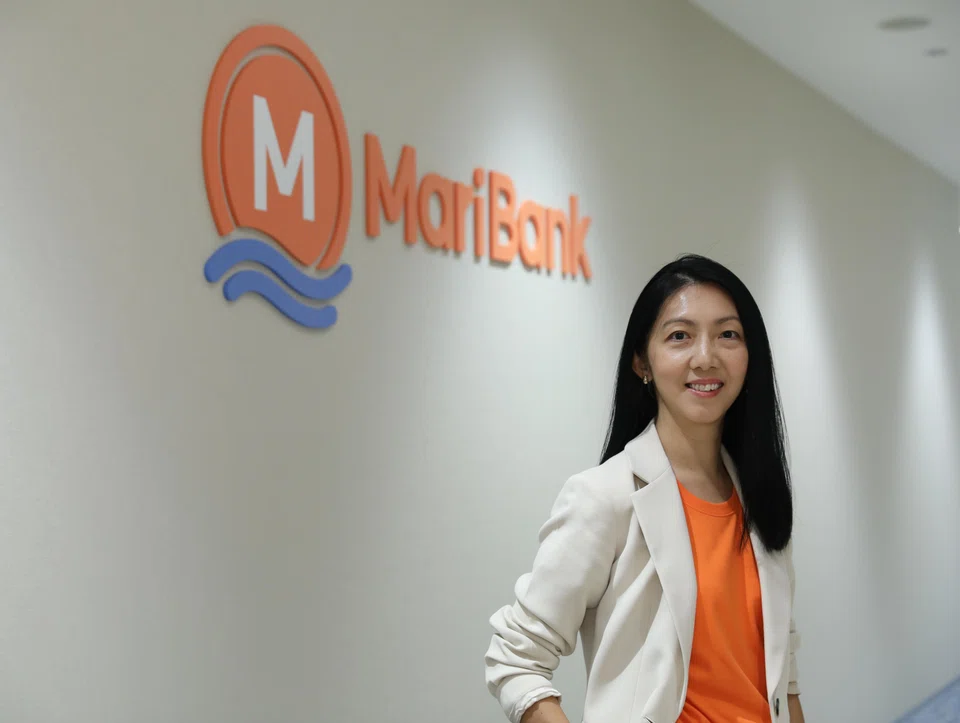
[SINGAPORE] MariBank is increasingly tapping its parent Sea’s ecosystem as it charts a path to profitability in Singapore – using data from e-commerce platform Shopee to grow its lending business while laying the foundations for a regional banking group based out of the Republic.
Access to Shopee’s data has given the digital bank an advantage in assessing creditworthiness for some small and medium-sized enterprises (SMEs), said Natalia Goh, CEO of MariBank.
“(For) merchants that sell on Shopee, we can see their sales, which gives us more data points on how we can underwrite them and manage risk around that,” Goh told The Business Times.
This ecosystem edge has grown in importance as MariBank seeks to differentiate itself from traditional lenders.
While being part of Sea has been helpful in sourcing business customers, about half of MariBank’s SME customer base now comes from outside the group ecosystem, reflecting growing traction in the broader market.
One particular sub-segment of SMEs that the digital bank is targeting is young businesses that have been operating for less than three years. They often struggle to obtain financing due to a lack of revenue or credit history.
About 17 per cent of MariBank’s SME lending has gone to such businesses.
“That really demonstrates how we’re trying to meet certain needs that we see in the market that are not fully served by traditional banks,” said Goh.
On the consumer side, MariBank has also deepened its integration with Shopee, offering a bonus rate of 0.4 per cent for MariBank customers who are also ShopeeVIP members, bringing the total interest rate to 1.28 per cent.
ShopeeVIP is a subscription programme that gives members benefits such as free delivery and priority customer service on the e-commerce platform.
The bonus is applied automatically through back-end integration between Shopee and MariBank, said Goh.
She added that 80 per cent of MariBank customers have linked their bank accounts with Shopee, integrating their banking services into their daily routines. And about 60 per cent of MariBank’s credit card users who make payments on Shopee have used the instalment plan exclusive to cardholders.
“This speaks to the point about the ecosystem as our strength, and also how we’re trying to embed banking within customers’ everyday lives and make it seamless and easy for them,” the CEO said.
MariBank’s assets under administration have grown about 40 per cent to S$4.2 billion as at Dec 31, 2025, with 30 per cent of its customers also holding an investment account with the bank.
Building a banking group
While it continues to roll out products for both retail and business banking, MariBank’s focus remains on scaling – including building out a South-east Asian banking group, said Goh.
“The vision is to build a regional banking group that’s based out of Singapore, with the city-state being the hub for talent and innovation,” she added.
MariBank acquired SeaBank Philippines in 2025, and the subsidiary was renamed MariBank Philippines. Other banks within the Monee – Sea’s financial services arm – structure, such as SeaBank Indonesia, could join this regional banking group.
The rationale for creating such a group is partly about driving innovation strategy out of Singapore, leveraging its strong digital and financial infrastructure.
MariBank will develop and build out capabilities and ideas in the city-state before scaling to the rest of the region.
“With a banking group, you have a common technology infrastructure, which you can build once and reuse to deploy to other markets,” explained Goh.
Singapore is a natural starting point for MariBank, as it offers more products and services than its Philippine arm, such as investments and credit cards.
The products built in Singapore can be localised and deployed in the Philippines quite quickly, noted Goh, with products tweaked to offer lower ticket sizes or other features that the market requires.
There is also some capital efficiency in building out a regional banking group, as each digital lender does not have to build products from scratch.
Said Goh: “The idea of the formation of the banking group is also to unify corporate governance and risk management frameworks across the banks, and bring it under the same brand name.”
For now, MariBank is concentrating on integrating MariBank Philippines and building out the regional banking group. It will approach any other opportunities or geographical expansion with a more strategic lens, she added.
Trust and engagement
Profitability is still important for MariBank, but Goh said it is focused more on building customer trust and engagement than maximising short-term gains.
“We don’t want to prioritise immediate economics at the expense of the customer or long-term business sustainability,” she added.
“We do look at profitability, but we also look at other metrics.”
This philosophy has shaped how MariBank approached the design of its products, such as allowing customers to start investing with just S$1 or taking a consumer loan from as low as S$100 – decisions that may not make sense from a purely commercial lens.
These decisions have resonated with customers. Since launching publicly in March 2025, MariBank’s instalment cash loan balances have grown about 600 per cent.
Among its new credit card customers this year, 90 per cent remain active users six months after opening their account.
This means that customers are not signing up solely because of promotional offers, noted Goh.
“Some of the metrics we track may not necessarily directly contribute to the immediate profitability number, but we believe this builds a sustainable path to profitability.”
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

What role can Japan play in Asean’s future?

