

Maybank initiates ‘buy’ coverage on Soon Hock with S$0.75 target
The real estate player’s profit is expected to surge, given its project pipeline
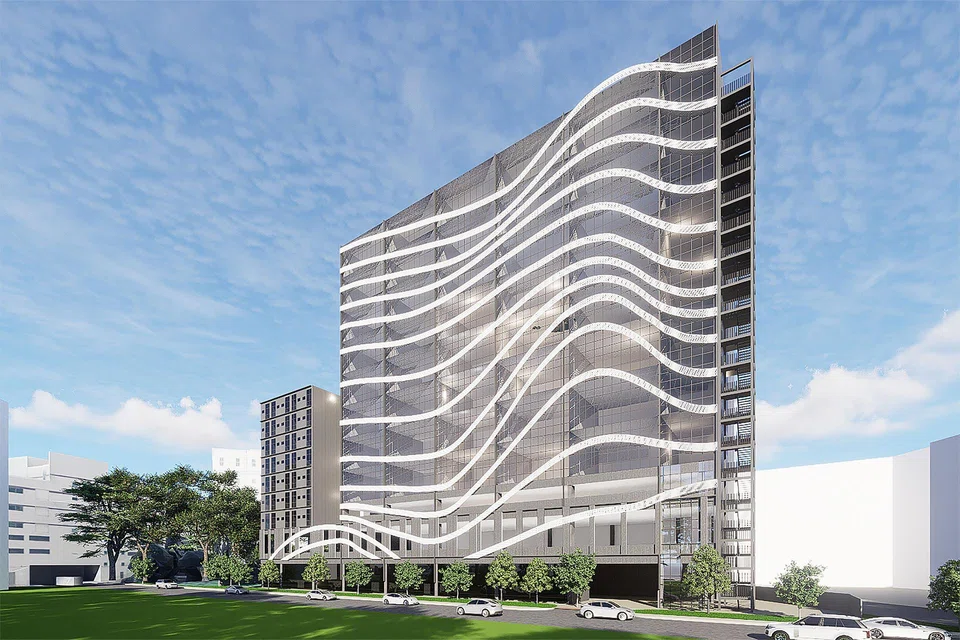
[SINGAPORE] Maybank Research has initiated coverage on industrial real estate specialist Soon Hock Enterprise with a target price of S$0.75, citing strong visible earnings from its development pipeline and a strengthening manufacturing sector.
The target price represents a potential upside of about 20 per cent from the counter’s closing price of S$0.63 on Tuesday (Jan 13).
In a Tuesday report, analyst Toh Xuan Hao said the group’s net profit is forecast to accelerate at a three-year compound annual growth rate of 299 per cent between FY2024 and FY2027.
Maybank expects the group’s bottom line to rise to S$47.2 million in FY2026, from S$3.3 million in FY2024.
Dividend yield could also increase to 6.2 per cent in FY2026, as management has proposed a 25 per cent dividend payout ratio for FY2025 and FY2026.
Upcoming projects
Maybank’s optimism is anchored by a “healthy pipeline” of projects that are already converting into sales.
“Soon Hock is well-positioned to expand its market presence through a steady pipeline of upcoming development projects,” Toh noted.
These future developments are “strategically designed to address unmet demand in the industrial real estate sector, while delivering enhanced value to both end-users and investors”, he observed.
The analyst highlighted the group’s flagship development Stellar@Tampines, a property meant for heavy industry use with an estimated gross development value of S$326.5 million.
Pre-sale momentum for the project is “positive”, with about 71 per cent of available units sold, he added. The strong early-stage sales provide “strong visibility into future cash flows”, reducing the reliance on heavy leverage during the construction phase.
The group plans to finance its remaining pipeline through a mix of internal and external funds.
Long-term uptrend of factory growth
Maybank believes that Soon Hock is well-positioned to ride the long-term uptrend in the Singapore factory market.
“As Singapore advances into more value-added activities such as research and development, specialty chemicals and additive manufacturing, demand for specialised logistics and warehouse facilities are expected to rise,” Toh noted.
The confluence of resilient demand, moderated future supply and continued rental growth presents a “compelling opportunity” for developers with access to land, construction capabilities and end-user insight to capture long-term value.
The group acquired multiple industrial properties at Senang Crescent and completed an en bloc purchase at Shaw Road, which is within walking distance of Tai Seng MRT station.
“The site offers excellent connectivity and long-term redevelopment potential,” Toh added.
Soon Hock is ranked among the top five strata industrial developers in Singapore, holding about 6 per cent of the market share.
Maybank remains wary of potential downsides, such as the cyclical nature of the Republic’s industrial property market and interest rate volatility, which might have an impact on borrowing costs.
In December 2025, UOB Kay Hian also initiated a “buy” call on Soon Hock, with a target price of S$0.68, implying an upside of around 15 per cent from the S$0.59 it was trading at then.
Shares of Soon Hock were down S$0.005 or 0.8 per cent at S$0.625 on Wednesday at 11.20 am.
TRENDING NOW
China recruited exec at Singapore data centre firm to spy on Nvidia CEO Jensen Huang: US intelligence
DBS, OCBC, UOB’s big sell-off: Was it their Q3 numbers or a broader market de-rating?

Could Japan trigger the next global financial crisis?
Philippines’ FDI slowdown exposes uneven investment prospects across S-E Asia

