

MNACT unitholders appeased by all-cash option of S$1.1949 per unit in proposed merger with MCT
MCT to make preferential offering of S$2.0039 per unit to fund the additional cash requirement of up to S$2.2b
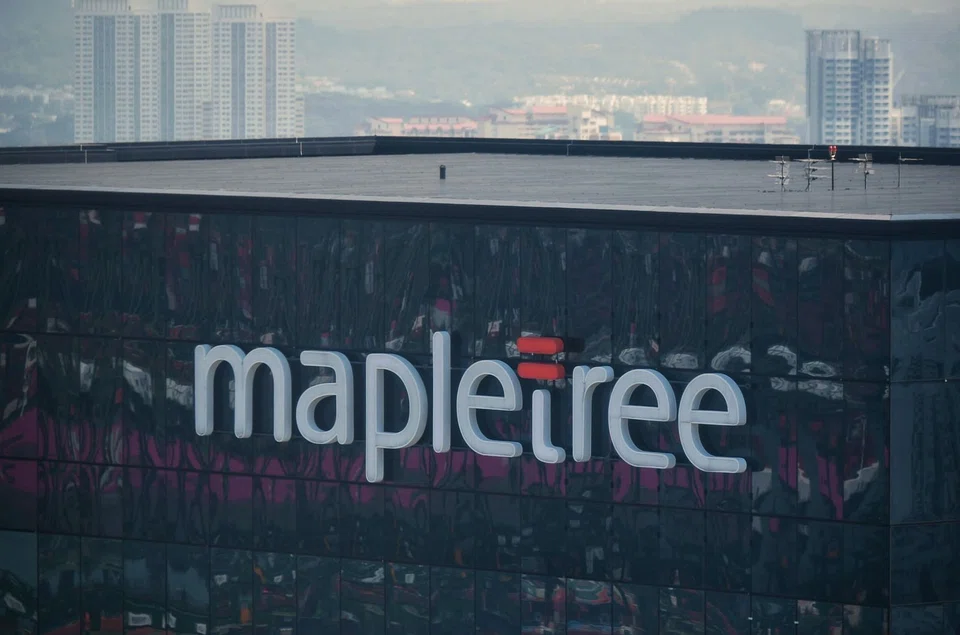
THE managers of Mapletree Commercial Trust (MCT) and Mapletree North Asia Commercial Trust (MNACT) are now offering MNACT unitholders the option to receive the entire scheme consideration of their proposed merger, of S$1.1949 per unit, wholly in cash.
MCT will also make a preferential offering of S$2.0039 per unit to fund the additional cash of up to S$2.2 billion required in the new cash-only option.
MNACT and MCT had in December proposed a merger of both real estate investment trusts (Reits), a move that has been criticised by unitholders on both sides and questioned by the Securities Investors Association (Singapore) (Sias).
Previously, the proposed trust scheme would see MNACT unitholders receive a scheme consideration of S$1.1949 for each MNACT unit held - either in the form of 0.5963 new MCT units at an issue price of S$2.0039 each, or a combination of 0.5009 consideration units and S$0.1912 in cash.
The new cash-only consideration will provide MNACT unitholders "greater flexibility to elect the form of scheme consideration that is most suited to their investment needs", the managers said in a joint statement on Monday (Mar 21).
The value of the scheme consideration remains unchanged at S$1.1949 per MNACT unit.
The all-cash option comes days after activist fund manager Quarz Capital Management late last week sought the intervention of the Monetary Authority of Singapore (MAS) to ensure that the manager of MNACT fulfils its fiduciary duty to its unitholders.
Quarz argued that the deal undervalues MNACT's assets, and questioned whether the manager of MNACT would have recommended to sell the Reit at the same value if the merger talks were not with related party MCT but with a third party.
"The cash offer is fair and a win-win for all parties," Quarz said in response to queries from The Business Times (BT). It added that it supports the merger and looks forward to being a long-term unitholder of the enlarged entity.
"The merger provides a successful platform that MCT can leverage on to undertake attractive and accretive acquisitions in Asia Pacific," Quarz said. "We thank the Mapletree manager and sponsor for taking prompt actions in addressing the concerns of unitholders with regard to the proposed merger."
Quarz was not the only group to question the merger. In February, Sias asked the Reit managers why the proposed merger was necessary, given that there are "no apparent operational synergies" between them. MCT's manager said the merger was to bring about long-term sustainable growth for MCT.
In response to queries from BT, MAS said that it "closely monitors corporate actions undertaken by Reits, and will take appropriate follow-up action where there are areas of supervisory concern".
"When presented with a merger proposal, the offeree Reit manager and its directors have the responsibility to properly evaluate the proposed terms, and to carefully assess all relevant factors in deciding whether to support and present the proposal to unitholders," the MAS spokesperson said.
"It is also incumbent on them, when presenting the merger proposal to unitholders, to explain clearly how they had arrived at their assessment to support the merger proposal," the spokesperson added.
The Reit managers noted that the decision to include the cash-only consideration came after a request from the MNACT manager amid prevailing market conditions and feedback from MNACT unitholders. The managers added that typically takes in comments from all unitholders, and not just feedback from individual investors.
"We have obviously been monitoring the market," said Cindy Chow, chief executive officer of MNACT's manager, at a briefing following the announcement. "We thought it was appropriate and timely to make the request to the MCT manager for them to review the terms and also to consider an all-cash option for our MNACT unitholders.
"Eventually, we came to a conclusion and agreed between both parties that this was a suitable option to be offered to MNACT unitholders. It certainly does give a higher certainty to our unitholders and also gives them the flexibility to elect the form of the scheme consideration that is most suited to their investment needs."
Sharon Lim, chief executive officer of the MCT manager, said the Reit remains "very committed" and "believes very strongly" in the rationale and financial benefits of the merger.
"The cash-only option is only possible to be offered on a table with the backing of sponsor Mapletree Investments, who will undertake to pick up the maximum number (of) units under the preferential offering, which is our source of funding for the all-cash option," Lim added.
Post-merger, the merged entity will be managed by the MCT manager. Lim will continue to lead the Reit manager following the completion of the merger.
To fund the additional cash requirement of up to S$2.2 billion, MCT will make a preferential offering of up to 1.09 billion units at S$2.0039 each, which is the same as the scheme issue price of each consideration unit, to its unitholders.
The offer price represents a 6.3 per cent premium to the volume weighted average price of S$1.8843 per MCT unit for all trades done on Mar 18, being the preceding market day up to the offer announcement.
Mapletree Investments, the sponsor of both MCT and MNACT, has provided an undertaking to subscribe up to S$2.2 billion in the preferential offering at the issue price.
It also agreed to a 6-month lock-up of its unitholdings in the merged entity upon the completion of the trust scheme or the preferential offering, whichever is earlier, on top of its earlier undertaking to fully receive the scrip-only consideration.
The funds raised are in addition to the S$417.3 million to be funded through the issuance of perpetual securities and/or debt funding, which were required under the original terms of the trust scheme.
The managers noted that the preferential offering will not be undertaken if all MNACT unitholders choose to receive either the scrip-only consideration or the cash-and-scrip consideration.
In the revised trust scheme, the cash-only consideration will be the default form of the scheme consideration, the managers said.
"If successful, the merged entity would become one of the largest Reits by market capitalisation listed in Asia, with a significantly larger scale and platform which is better positioned to unlock upside potential," OCBC's research team said in a report on Monday.
"That said, we believe MCT would gain new exposure to riskier markets and see dilution to its pure-play Singapore status," it added. OCBC is keeping its "buy" recommendation on MCT, with a fair value estimate of S$2.04.
"The addition of the third full-cash option provides MNACT unitholders with greater flexibility in choosing to either stay invested in the merged entity, or fully realise their investment," the research team said.
Units of MNACT ended 8.9 per cent or S$0.10 higher at S$1.22 on Monday, while units of MCT rose 0.5 per cent or S$0.01 to close at S$1.90.
READ MORE:
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

