Mega merger of Sembmarine, Keppel O&M simplified to ensure deal certainty, quicker completion
THE mammoth plan to merge Singapore’s home-grown offshore and marine (O&M) giants Sembcorp Marine (Sembmarine) and Keppel Corp ’s O&M unit has been drastically simplified, with Sembmarine gaining a sweeter deal, six months after the details of the merger were first revealed. Greater deal certainty and speed to close the proposed merger of Sembmarine and Keppel O&M – set to create a powerhouse with a sizeable net order book of S$18 billion – plus a rosier sector backdrop and uncertain macro headwinds were cited by top officials from both companies as the rationale for the revised transaction structure and terms.
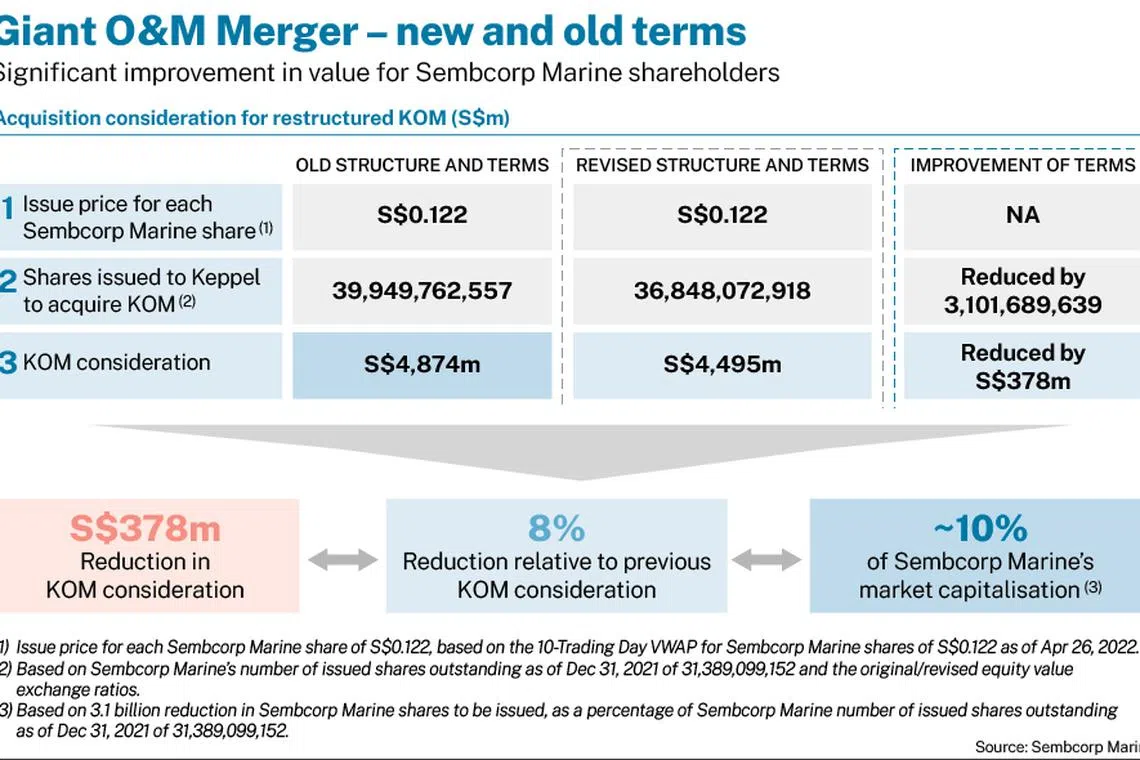
Most significantly, Sembmarine will directly acquire Keppel O&M (KOM) from Keppel Corp at an improved equity-value exchange ratio (46:54 versus the earlier 44:56 SembMarine:KOM). This translates to an 8 per cent or S$378 million reduction to S$4.50 billion for the purchase consideration of KOM.
Sembmarine will also retain its listing status on the Singapore Exchange mainboard, and directly issue 36.8 billion new shares to Keppel. These new shares have been reduced by 3.1 billion – some 10 per cent of Sembmarine’s market capitalisation.
There will no longer be a “combined entity”, and the proposed one-for-one share exchange between this entity and Sembmarine as well as a transfer of Sembmarine’s listing status to the combined entity.
Under the revised deal, Sembmarine shareholders will own 46 per cent of the enlarged entity. Keppel will own 54 per cent, of which it will retain 5 per cent and distribute 49 per cent of the enlarged Sembmarine shares in specie to its shareholders.
Sembmarine said that this improved exchange ratio would deliver better value upfront to existing shareholders, as fewer shares will be issued for the acquisition; also, they would retain a larger stake in the company after the deal is completed.
Sembmarine chairman Hassan Marican said at a media and analyst briefing on the deal’s revised terms on Thursday evening: “While the operating environment of the sector has improved, macroeconomic conditions have deteriorated. In these volatile and uncertain times, it is even more critical for the proposed combination to be completed as soon as possible.” The revised transaction could take the deal about two months less time to be completed, so it could possibly take place by year’s end.
Keppel Corp’s chief executive Loh Chin Hua said at a separate briefing on Thursday that it may have been “almost impossible” to close the deal in its original form this year, given that Sembmarine’s earlier proposed scheme would have also involved a court process.
“These are very important points – deal certainty and speed to completion. The sooner we can get the transaction completed, the better it would be, in the sense that we can start (reaping) the synergies between the two companies,” he said, adding that the substance and strategic intent of the merger plan have not changed.
“While the exchange ratio for Keppel has been lowered slightly, this is still a very positive outcome for Keppel and its shareholders,” he said.
A plus point under the revised terms for Keppel is its “Asset Co transaction” is no longer inter-conditional on the merger deal. Keppel previously signed a definitive agreement with Baluran (an indirect wholly-owned subsidiary of ASM Connaught House Fund V) and Kyanite Investment Holdings (an indirect wholly-owned subsidiary of Temasek Holdings) for the sale of Keppel O&M’s legacy completed and uncompleted rigs, and the receivables associated with certain legacy rigs to a separate Asset Co.
Baluran and Kyanite, the external investors, will respectively own 74.9 per cent and 15.1 per cent of Asset Co. Keppel will hold a 10 per cent equity interest in Asset Co and receive vendor notes and perpetual securities. The combined value of approximately S$3.93 billion in vendor notes, some S$120 million in perpetual securities, and the 10 per cent equity interest in Asset Co is approximately S$4.05 billion.
In addition, to reflect the higher interest rate environment, the parties have agreed that the coupon for the S$3.9 billion in vendor notes to be received by Keppel will be raised from 2 per cent to 4 per cent, which translates into about S$79 million of additional interest earned per annum, or about S$236 million to S$393 million over three to five years.
Loh, referring to the S$378 million reduction in the acquisition consideration for KOM, said: “This is a very positive outcome for Keppel and its shareholders... the additional interest will more or less pay for the difference in terms of the consideration that we’re receiving...
“While it is quite natural to look at the details – like who gets what, who gets something more or something less – the big picture is that the combined entity now is much stronger. And we are in a very strong position now for (a) combined entity, and the future is bright. So more importantly... is that the combined entity continues to do well, which would lead to a better outcome for everybody.”
Terence Chua, senior research analyst at Phillip Securities Research, said: “As a whole, despite the lower exchange ratio, the greater certainty for deal completion will be a plus for Keppel Corp shareholders, who stand to benefit from the monetisation of its O&M business.
“We believe the revised terms between KOM and Sembmarine is a sweetener for Sembmarine shareholders. With this sweetened deal, the certainty of deal completion should be higher now.”
Sembmarine shares rose 1.7 per cent, or S$0.002, to close at S$0.12 on Thursday. Keppel shares increased 0.8 per cent, or S$0.05, to S$6.65.