Most analysts positive on Keppel's rig-building exit but trim targets; shares sink 8.2%
They believe it could be a catalyst for growth in the long run, but others see risks from a prolonged O&M restructuring
Singapore
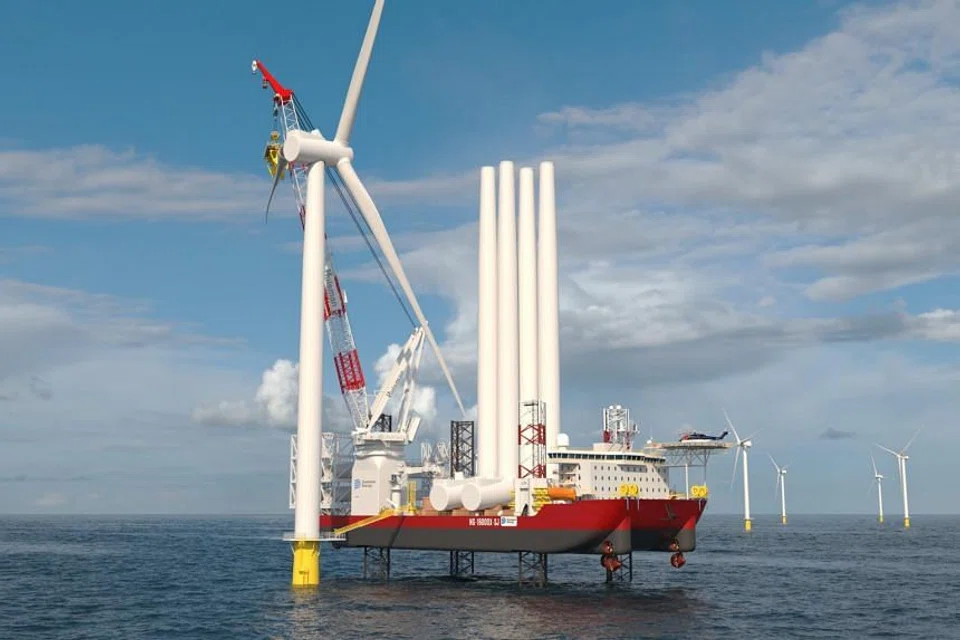
KEPPEL Corp shares hit a two-month low on Friday after the conglomerate announced it intends to exit the rig-building business and instead focus on green energy.
The move drew mixed reactions from analysts. Most believe the group's decision to exit the rig business and restructure subsidiary Keppel Offshore & Marine (Keppel O&M) could be a catalyst for growth. But they are not expecting Keppel's prospects to improve overnight. And at least three analysts have lowered their target prices for the stock.
Shares of Keppel sank as low as S$5 on Friday - its lowest level since Nov 16, 2020. The counter did, however, regain some ground to close at S$5.01, on a cum-dividend basis, down 8.2 per cent or 0.5 Singapore cent for the day.
UOB Kay Hian (UOBKH) and CGS-CIMB remain positive on Keppel's outlook but lowered their target prices on the conglomerate. UOBKH lowered its target price (TP) to S$6.10 from S$6.30, and CGS-CIMB cut its TP to S$6.40 from S$6.46.
UOBKH maintained its "buy" call on the conglomerate, saying the stock remains "inexpensive". The group's net profit decline of 13 per cent, following a hit from impairments, was better than the research house had expected. Analyst Adrian Loh also believes the exit strategy is a positive move for Keppel as he expects the outlook for the rig-building sector to remain bearish for the next year or so.
"Rig day rates and utilisation rates for all asset classes declined throughout 2020 despite starting the year with already poor numbers. In our view, these figures are not expected to recover in the medium term," said Mr Loh.
CGS-CIMB analyst Lim Siew Khee was similarly positive on Keppel's announcement, but noted that the market had hoped for Keppel to fully divest the O&M business instead.
Ms Lim has maintained her "add" call on Keppel in its report on Jan 28. She noted that Keppel had successfully divested S$1.2 billion worth of assets since Oct 20, with an estimated gain of more than S$120 million.
Potential catalysts for Keppel, she said, would include the successful sale or chartering of rigs, as well as the clinching of additional orders in the renewables space. The downside risks to investors, on the other hand, would come from a prolonged O&M restructuring.
DBS, meanwhile, downgraded its "buy" call to "hold", but raised its TP to S$5.85 from S$5.50 previously.
Analyst Ho Pei Hwa noted that Keppel's shares had risen some 30 per cent since she upgraded her call on the counter in September last year. She therefore believes the stock is now fairly valued, although she has raised her TP slightly to reflect her new earnings estimates for FY2021.
Ms Ho believes Keppel is en route to recovery as economic activities pick up with gradual vaccination rollouts, but she believes investors should await better positive indicators as the conglomerate restructures.
Separately, OCBC maintained its "hold" call on the conglomerate and lowered its fair value to S$5.20 from S$6. The change in its call reflects the reduced upside potential from here, while the lower fair value comes following Keppel's reorganisation of its business segments. "At current levels, we see most of the positives priced in," OCBC said in a report on Friday.