

MPACT Q2 DPU falls 8.2% to S$0.0224 on higher interest rates
Renald Yeo &
Raphael Lim
THE manager of Mapletree Pan Asia Commercial Trust (MPACT) reported a distribution per unit (DPU) of S$0.0224 for the second quarter ended Sep 30, 2023, down 8.2 per cent from S$0.0244 a year earlier.
This was due primarily to higher interest rates, the manager said in a bourse filing on Thursday (Oct 26).
Contributions from the trust’s overseas assets were also weighed down by foreign exchange effects resulting from a stronger Singapore dollar during the quarter.
The amount distributable to unitholders in Q2 FY23/24 rose 0.3 per cent year on year to S$118 million, from S$117.7 million.
Gross revenue grew 10.1 per cent to S$240.2 million from S$218.2 million. Net property income (NPI) rose 8.7 per cent to S$183.2 million from S$168.5 million. Net finance costs during the quarter grew 37.5 per cent to S$57.6 million from S$41.9 million.
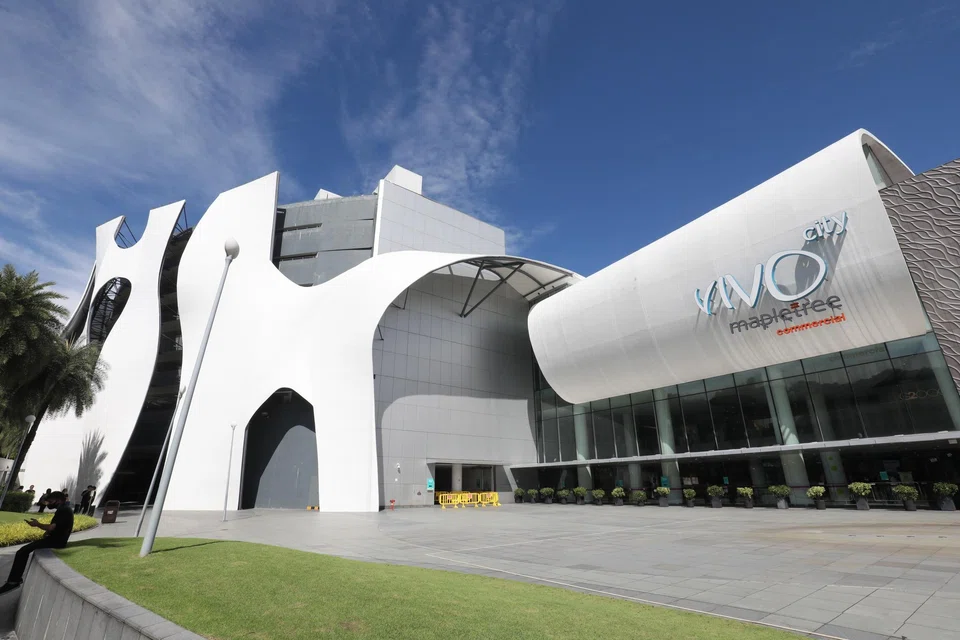
MPACT’s core assets in Singapore include Mapletree Business City (MBC) and VivoCity. Gross revenue from MBC came in at S$58.5 million in Q2, compared to S$58 million in the preceding quarter.
VivoCity, meanwhile, contributed S$57.8 million in gross revenue, compared to S$56.3 million in the first quarter.
For the six months ended Sep 30, the amount distributable to unitholders grew 15.8 per cent year on year to S$232.8 million. But DPU was down 10.5 per cent to S$0.0442.
Gross revenue for H1 FY23/24 rose 35.1 per cent to S$477.3 million, while NPI grew 31.7 per cent to S$362.4 million.
“Higher interest rates exerted pressure on the DPU, leading to year-on-year declines for the second quarter and the first half,” MPACT’s manager said.
Sharon Lim, chief executive of the manager, said during the results briefing that the real estate investment trust (Reit) is relatively stable in terms of operations, but the two issues that would continue to affect it would be foreign exchange and interest rates.
“Interest will continue to move up, because we got old hedges that we need to roll into new ones. It will slowly creep up, although we have suffered most of the pain,” she added.
As at end-September, MPACT’s portfolio committed occupancy stood at 96.3 per cent, up from 95.7 per cent as at end-June. The overall weighted average lease expiry for the trust is 2.5 years.
On the capital management front, MPACT’s aggregate leverage ratio was 40.7 per cent as at end-September, unchanged from end-June.
Meanwhile, adjusted interest coverage ratio fell to three times as at end-September from 3.2 times in end-June.
To navigate the rising interest rate environment, the trust’s ratio of fixed-rate debt was lifted to 79.9 per cent as at end-September, compared to 74.2 per cent as at end-June, the manager said.
Lim said that the manager is not considering any equity fundraising. “We will always look internally, what else we can do, without thinking of touching the investors,” she added, noting that investors have said that they are not ready to pump in too much money in today’s context. “I don’t think that is the strategy we will be taking. I think our gearing and capital structure is still ok today and we don’t need to do such a move.”
In terms of divestments, she said that it is something that would be good to have but the Reit is not in “dire straits” where something has to be done. “If I were to do any form of divestment, it is potentially to shore up and build up my balance sheet for the future,” the chief executive said.
She pointed out that it is currently an “uphill task” to sell anything in China as investors are more cautious. The only market that investors are more interested in is Singapore. “If the price is right, and it helps me in strengthening my balance sheet, (divestment) is something that I would consider. But if these two conditions are not in place, I don’t see the need to let go of something that doesn’t solve anything.”
The Reit’s distribution for Q2 will be paid on Dec 8.
Units of MPACT closed unchanged at S$1.30 on Thursday, prior to the announcement.






