

Nearly half of S-Reits suffer DPU declines in H2 – more pain for investors lies ahead
Jude Chan
NEARLY half of the Singapore-listed real estate investment trusts (S-Reits) have reported a year-on-year (y-o-y) decline in distribution per unit (DPU) for the latest period ended Dec 31, 2022.
But even as S-Reit managers – and investors – keep their fingers crossed for an end to interest-rate hikes, the data suggests it might get worse before it gets better: nearly two-thirds of the real estate investment trusts (Reits) have seen their DPU retreat compared to the preceding quarter or half-year periods.
This implies that while S-Reits are still doing better than they did in the previous year, momentum is not on the side of the optimists – and DPU looks headed for further decline ahead.
Of the 35 S-Reits that reported gross revenue figures for the latest quarter or half-year period, 26 saw an improvement – mostly due to the revival of economic activity with the reopening of borders in most countries.
Among the 36 that reported net property income (NPI) data, 25 did better year on year. Much of these gains, however, were decimated by higher financing costs amid rising interest rates.
Of the 34 S-Reits that reported DPU figures, 16 saw improvements, while another 16 posted declines, and two others had DPUs unchanged from the previous year.
Smoothed out over the full year, the figures were more encouraging: 25 out of 29 reported higher gross revenue for FY2022, 24 out of 30 saw higher NPI, and 15 out of 29 posted higher DPU.
“Plateauing rates, an appreciating Singapore dollar (SGD) and reopening of borders globally add to our positive view of S-Reits,” said Maybank analysts Krishna Guha and Li Jialin.
“That said, sticky inflation and a higher-for-longer thematic, a sluggish SGD bond market, potential recession and tight spreads make us pause,” they added.
Losing momentum
On the face of it, the figures are not half bad. But the slowdown in the latest period might be cause for concern.
Only 19 out of 32 S-Reits reported higher gross revenue compared to the preceding half or quarter. And of the 33 that reported NPI figures, only 15 saw improvements half-on-half (h-o-h) or quarter-on-quarter (q-o-q).
More alarmingly, only a third – or 11 out of 33 S-Reits – saw DPU improvements h-o-h or q-o-q. In contrast, 20 of these S-Reits saw their DPUs slip compared to the preceding period.
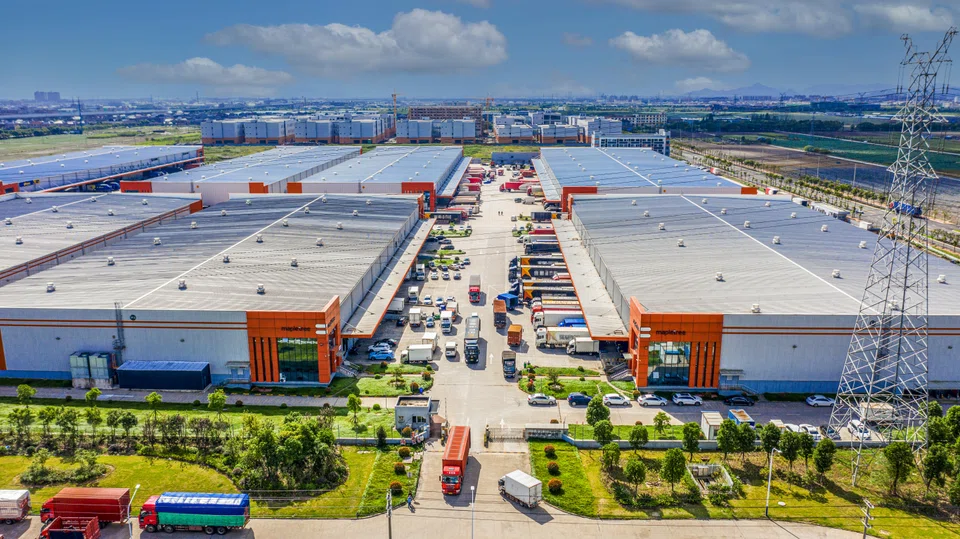
For example, Mapletree Logistics Trust (MLT) recorded a seemingly stellar third quarter, with an 8 per cent y-o-y increase in gross revenue to S$180.2 million on the back of accretive acquisitions, while NPI rose 7.3 per cent to S$157.2 million.
MLT’s Q3 available DPU was 1.9 per cent higher at S$0.02227, including income support of S$616,000. Excluding income support, Q3 DPU would be S$0.02214.
However, MLT’s Q3 figures were lower than the gross revenue of S$183.9 million and NPI of S$160 million in Q2 ended Sep 30, 2022.
The latest DPU was also lower than Q2’s available DPU of S$0.02248, including income support of S$974,000. Excluding income support, Q2’s DPU would have been S$0.02228 – higher than that of the latest quarter ended December.
“Notwithstanding the attractiveness of a regional network of warehouses in trade and consumption-oriented geographies, the near-term outlook is tempered by foreign exchange volatility, new supply and a difficult environment for accretive deals,” Guha said, as he downgraded his recommendation on MLT to “hold”, from “buy” previously.
Another examples of S-Reits that performed better y-o-y but declined h-o-h are CapitaLand India Trust (Clint) and Starhill Global Reit .
Meanwhile, the hospitality and healthcare S-Reits were among the best performers in the latest period.
For example, CapitaLand Ascott Trust (Clas) reported a 47 per cent increase in distribution per stapled security (DPS) to S$0.0333 for the half year ended December, from S$0.0227 the previous year.
Including adjustments for one-off items as well as a divestment gain of S$25 million, adjusted DPS would have near doubled to S$0.03 in H2, from S$0.0151 in the year-ago period.
Clas’ H2 revenue climbed 69 per cent to S$353.8 million, with revenue per available unit increasing 81 per cent on the back of the international travel recovery.
For the full year, Clas’ DPS was up 31 per cent to S$0.0567, while revenue was 58 per cent higher at S$621.2 million.
Similarly, hospitality peers such as Ara US Hospitality Trust , CDL Hospitality Trusts and Far East Hospitality Trust all reported improvements in gross revenue, NPI and DPU for their respective second-half and full-year periods.
On the healthcare front, Parkway Life Reit led the way with a 2.7 per cent increase in DPU to S$0.0732 for the second half ended December, compared to S$0.0713 in the previous year.
H2 gross revenue grew 14.2 per cent to S$69.8 million, while NPI was 18 per cent higher at S$65.8 million.
For the full year, Parkway Life Reit’s DPU was 2.1 per cent higher at S$0.1438, with gross revenue up 7.7 per cent to S$130 million and NPI increasing 9.6 per cent to S$121.9 million.
The improvements were attributed to higher rent from recently acquired properties and the group’s Singapore hospitals under new master lease agreements, as well as adjusted hospital revenue for Parkway East Hospital’s 15th year lease, which outperformed its minimum guaranteed rent.
On the other hand, office S-Reits were among the worst performers in the latest round of results.
Of the 6 that reported their H2 results, only one – Keppel Reit – managed to eke out positive distributable income and DPU growth year on year.
However, this was only due to a special S$10 million anniversary distribution for the period. Distributable income from operations, without the anniversary distribution, would have been 3.8 per cent lower in H2.
Results were mixed across the other sub-sectors.
Some of the better performing S-Reits that reported both y-o-y and h-o-h improvements across gross revenue, NPI and DPU include CapitaLand Integrated Commercial Trust , CapitaLand Ascendas Reit , ESR-Logos Reit and Keppel DC Reit .
TRENDING NOW

8 public officers referred to police over property buys near unannounced MRT stations: Chan Chun Sing
DBS tops trades in smaller board lots on debut of revised SGX framework

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Retrenched PMETs who return on lower pay see median 25% wage cut

