No major impact from Johor data centres, US export ban: Keppel DC Reit manager
The real estate investment trust’s H2 DPU is up 13.2% at S$0.04902
NEW data centres in Johor, Malaysia, and the US chip export ban are unlikely to have a big impact on Keppel DC Reit , said the manager on Friday (Jan 24).
The workloads in Johor are different from those in Singapore, with the data centres in the Republic doing artificial intelligence (AI) inference work rather than training, the manager said in its fourth quarter 2024 earnings call. Singapore and Johor are targeting different market segments, which would be good for the entire ecosystem.
Loh Hwee Long, chief executive of Keppel DC Reit Management, said: “This is the higher-value type of AI computing work that will continue to reside in Singapore because of the very strong connectivity features we have here, as well as the ease of doing business and stability.”
The manager posted a distribution per unit (DPU) of S$0.04902 for the second half ended December, up 13.2 per cent from S$0.04332 in the previous corresponding period.
This brings total DPU for FY2024 to S$0.09451, up 0.7 per cent on the year.
Excluding the impact from the new units raised via a pro-rata preferential offering prior to the completion of the acquisition of Keppel DC Singapore 7 and Keppel DC Singapore 8, DPU for H2 2024 would have been S$0.04955, up 14.4 per cent from the previous corresponding period.
Total DPU would have increased by 1.3 per cent to S$0.09504.
Factors behind higher full-year DPU
The higher full-year DPU comes amid a rent increase, distribution arising from the settlement sum related to the dispute that the real estate investment trust (Reit) has with DXC Technology Services Singapore, as well as contributions from Tokyo Data Centre 1.
But it was partially offset by loss allowances for the Reit’s Guangdong data centres, higher finance costs in H1 2024, as well as the depreciation of foreign currencies against the Singapore dollar.
Based on its closing price of S$2.18 on Dec 31, 2024, the Reit’s distribution yield for FY2024 was 4.3 per cent.
The distribution for H2 will be paid on Mar 17, after the record date of Feb 5.
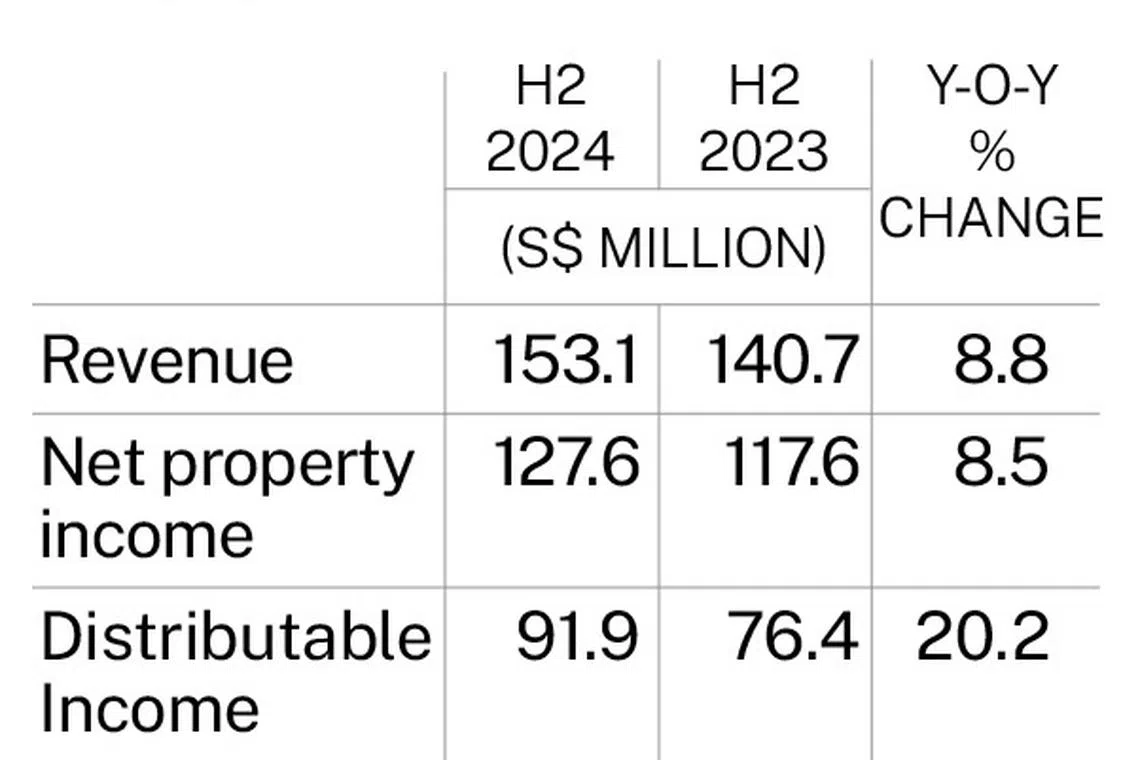
Distributable income rose 20.2 per cent to S$91.9 million for H2, from S$76.4 million in the corresponding period of the year before.
Revenue rose 8.8 per cent on the year to S$153.1 million, from S$140.7 million, mainly due to strong reversions and escalations across the Reit’s portfolio, as well as contributions from the Tokyo data centre.
But gains from the purchase of the Japan asset were partially offset by the sale of its Sydney data centre, Intellicentre Campus.
Net property income (NPI) was up 8.5 per cent at S$127.6 million for H2, from S$117.6 million, although property operating expenses rose 10 per cent on higher facility management fees from the Singapore assets.
For the full year, NPI was up 6.3 per cent at S$260.3 million, from S$245 million previously. Revenue rose 10.3 per cent on the year to S$310.3 million. Distributable income was up 3 per cent at S$172.7 million, from S$167.7 million previously.
In April, the Reit divested its Sydney data centre for A$174 million (S$152.1 million), and reinvested some of the proceeds into an Australian data centre note with an initial yield of about 7 per cent.
Loh believes the Reit is “well-positioned” to capture the rising demand for more advanced, artificial intelligence-ready data centres.
The recent news of the US’ export limits on graphics processing units (GPUs) is also unlikely to have a major impact on the Reit. Singapore is classed as a Tier 2 country, with a cap on the maximum computing power of about 50,000 GPUs. Companies can bypass the limit if they apply for validated end-user status, which will not count towards the national cap.
“Of course, I think that news will come into play as we evaluate (the situation) on a forward basis in terms of our acquisition strategy, which we’ll look out for,” he said.
The recent sale of Basis Bay Data Centre in Malaysia is expected to be completed around Q3 2025.
The Reit’s portfolio by assets under management, which is worth some S$5 billion as at end-December 2024, stood at 80.7 per cent in the Asia-Pacific and 19.3 per cent in Europe.
As at Dec 31, 2024, portfolio occupancy stood at 97.2 per cent. The weighted average lease expiry by lettable area of its overall portfolio was 6.3 years.
In FY2024, the Reit recorded positive portfolio reversion of about 39 per cent.
Keppel DC Reit’s aggregate leverage as at Dec 31 stood at 31.5 per cent, down 820 basis points from Sep 30, 2024. This was mainly due to the purchase of the Singapore 7 and 8 data centres, which was largely funded by equity fundraising.
Its average cost of debt was 3.1 per cent for Q4 2024 and 3.3 per cent for the year to date. Its weighted average debt tenor is 3.2 years. Some 66 per cent of the Reit’s borrowings are fixed through interest rate swaps.
As at Dec 31, 2024, Keppel DC Reit had an interest coverage ratio of 5.3 times.
Outlook
Looking ahead, the Reit manager said that vacancy rates for data centres will continue to decline across global markets due to strong demand for cloud adoption by both governments and businesses.
The global outlook remains risky, it added, noting that there could be new spikes in commodity prices amid persistent geopolitical tensions, as well as trade tensions.
But the manager said it will continue to grow its portfolio of data centres and strengthen its presence across key international data centre hubs.
Units of Keppel DC Reit ended Friday 2.3 per cent or S$0.05 higher at S$2.27.