

OCBC’s Indonesia deal boosts wealth push, may herald more M&A under new CEO Tan Teck Long: analysts
Industry watchers say the bank might look to high-growth Asean markets for more acquisitions
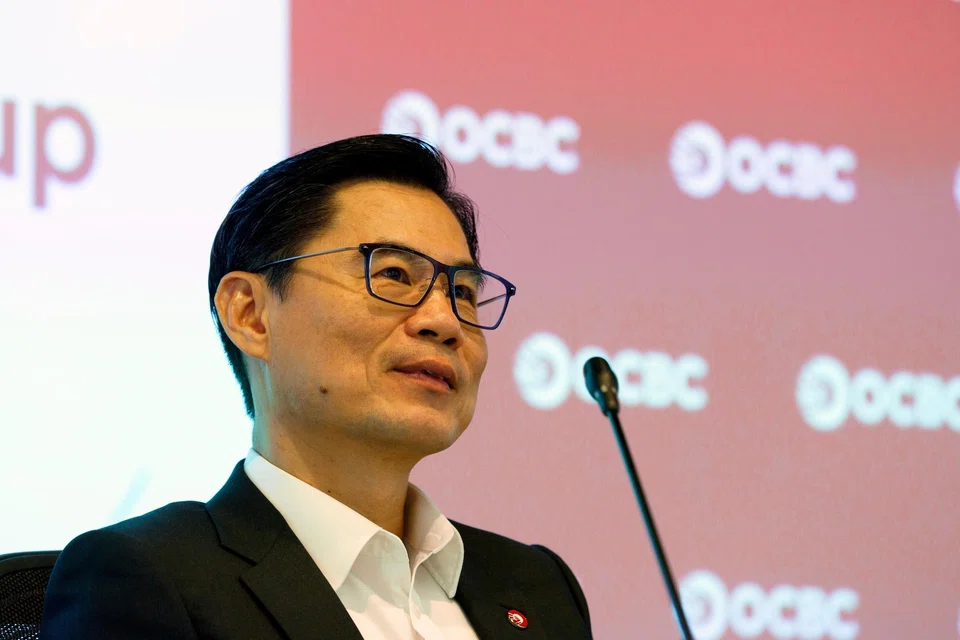
[SINGAPORE] OCBC’s latest Indonesian acquisition is expected to strengthen its fee income base and expand its wealth franchise in South-east Asia’s largest economy, as pressure on lending margins pushes banks to diversify earnings.
Analysts said the “bolt-on” deal could also signal more acquisitions to come, particularly in high-growth Asean markets where global banks are trimming their retail and wealth operations.
On Monday (May 4) night, OCBC announced that its Indonesian subsidiary, Bank OCBC NISP Tbk, would acquire HSBC’s retail and wealth management operations in Indonesia.
The total consideration will be based on the net asset value of the Indonesian business upon completion, plus a premium of up to 6.5 trillion rupiah (S$481.1 million). The deal is expected to close in the second quarter of 2027.
Some analysts have welcomed the acquisition, which is expected to be earnings-accretive and add S$6.6 billion to OCBC Indonesia’s assets under management. This comprises S$4.3 billion of customers’ investments in mutual funds and bonds, as well as insurance and customer deposits of S$2.3 billion.
A retail customer loan book of S$300 million will also be transferred to OCBC Indonesia, along with a customer base of about 336,000.
On the talent front, around 1,300 staff are expected to join OCBC Indonesia’s wealth management pool.
The Singapore lender’s latest acquisition is a “good fit to incrementally grow its Indonesia franchise”, particularly in wealth management, wrote S&P Global Ratings analysts Ivan Tan and Sue Ong in a Tuesday note.
“We believe wealth management is attractive in a low-interest-rate environment because it augments recurring income to cushion earnings, especially at a time when Singapore banks are facing net interest margins compression,” they added.
They added that the “immediate financial impact” on OCBC is limited, given the “small size” of the acquisition.
Lim Rui Wen, an equity research analyst at DBS Group Research, called Monday’s deal a “highly synergistic bolt-on acquisition” that is focused on adding affluent customers and strengthening OCBC Indonesia’s domestic wealth capabilities.
The insurance and customer deposit base of S$2.3 billion should also provide stable, low-cost funding to OCBC Indonesia, said Lim.
The acquisition builds on the bank’s earlier expansion in Indonesia. In 2024, OCBC acquired Bank Commonwealth Indonesia, adding more than 1.2 million customers.
But not all analysts were positive on this move. UBS analysts Aakash Rawat and Benjamin Tan wrote in a report that the deal looks “a bit overvalued”, based on the reported profit before tax of S$3.9 million in 2025 for HSBC Indonesia’s retail and wealth business.
They pointed out that profit before tax declined from S$30.8 million in 2023 to S$9 million in 2024. “This suggests that OCBC is buying a business which has been witnessing declining profitability over the last couple of years,” the UBS analysts added.
More deals possible
Beyond the latest acquisition, analysts said OCBC could continue to look for similar opportunities.
In the near term, the lender is “likely in a consolidation phase”, said Bloomberg Intelligence senior credit analyst Rena Kwok.
“In the medium term, I believe the group may keep a keen eye on similar portfolios in high-growth Asean markets if the valuation is right,” said Kwok.
Kathy Chan, equity analyst at Morningstar, noted that Monday’s deal was “actually quite in line” with OCBC’s updated strategy, unveiled by group chief executive Tan Teck Long at the lender’s fourth-quarter results briefing in February.
OCBC is scheduled to release its first-quarter results for the three months ended Mar 31 on Friday, before the market opens.
At the February briefing, Tan – who took over as chief executive of South-east Asia’s second-largest bank on Jan 1 – laid out OCBC’s Asean ambitions under its new “Next Frontier” strategy.
These included possible acquisitions in the region, funded in part by conserving capital after its existing capital return plan concludes. In FY2025, OCBC announced a two-year, S$2.5 billion capital return plan, which runs till the end of FY2026.
Tan said in February that the lender would revert to its historical 50 per cent dividend payout policy after the current capital return plan ends. The bank would retain funds that might otherwise have gone towards another capital return plan – equivalent to around 10 per cent of annual net profit – partly to support acquisitions that fit its corporate strategy.
The CEO added then: “If there’s any inorganic opportunity in Asean, we will certainly want to take a look.”
The S&P analysts noted that OCBC remains well-capitalised after the acquisition, with sufficient buffers to fund inorganic growth opportunities.
Morningstar’s Chan concurred: “OCBC mentioned in the media release that they don’t expect the transaction to have (a) material impact on OCBC’s capital, so we think further portfolio acquisitions in their key markets are possible with the ample capital they have.”
However, JP Morgan analysts expect a “small negative reaction” for the stock since the upside from the deal is more long-term and incremental, while the probability of lower dividends may be more immediate.
Global bank exits
DBS Group Research’s Lim noted that global banks undergoing group-wide restructuring have started to retreat from certain locations, creating potential opportunities for Singapore’s three local lenders.
In 2022, Citigroup closed deals to sell its Taiwan consumer business to DBS, and its consumer franchises in Indonesia, Malaysia, Thailand and Vietnam to UOB. The latter transaction, valued at S$4.9 billion, was completed in 2025.
“We believe in some of the locations within Asia, global banks may lack scale to compete due to subscale economics alongside the complexity for some of these global banks to operate in every single location footprint,” said Lim.
“For the Singapore banks, having bolt-on acquisitions in geographies they already operate in, may be complementary to their existing offerings,” she added.
Shares of OCBC closed down 0.2 per cent or S$0.04 at S$21.83 on Tuesday.

