

Quarz's campaign may help rather than hinder the proposed merger of MCT and MNACT
Its insistence that MNACT is being undervalued might - perversely - mollify disgruntled MCT unitholders inclined to vote against the merger
THE proposed merger of Mapletree Commercial Trust (MCT) and Mapletree North Asia Commercial Trust (MNACT) made headlines again this past week as Quarz Capital Management urged unitholders of MNACT to demand better terms or vote against the deal.
Quarz grumbled in a letter to MNACT's manager dated Feb 9 that the merger values MNACT at discount to its net asset value (NAV), and that the transaction will destroy value for unitholders.
This is an interesting twist. When the proposed merger of the two Mapletree real estate investment trusts (Reits) was announced on Dec 31, the consensus in the market seemed to be that the terms of the deal favoured unitholders of MNACT over those of MCT.
Will Quarz's campaign now rally MNACT unitholders to oppose the merger too? Or, could Quarz's insistence that MNACT is being undervalued - perversely - mollify disgruntled MCT unitholders inclined to vote against the merger?
Under the proposed merger, unitholders of MNACT will exchange each unit they own for 0.5963 of a new MCT unit; or 0.5009 of a new MCT unit plus S$0.1912 in cash.
Based on MCT's closing price before the announcement of S$2.00, each unit of MNACT was effectively being valued at about S$1.193. This was some 7.5 per cent more than MNACT's closing price before the announcement of S$1.11.
It was also very close to MNACT's NAV per share as at Sep 30, 2021, of S$1.1949 - adjusted for H1 FY2022 distribution per unit (DPU) paid on Dec 24, 2021, and the valuation of MNACT's assets as at Sep 30, 2021, as announced on Dec 31, 2021.
On Jan 3, the first post-announcement trading day, MNACT climbed 3.6 per cent to close at S$1.15 while MCT fell 4 per cent to close at S$1.92.
Since then, MCT has fallen further and pulled MNACT down with it. On Friday (Feb 11), MCT closed at S$1.83 while MNACT closed at S$1.09.
With this correction in MCT's market price, Quarz now wants the terms of the merger adjusted such that the implied valuation of MNACT is pushed back up towards its NAV. Specifically, Quarz has suggested that each unit in MNACT be exchanged for 0.68 of a new unit in MCT.
But wouldn't such a change in the merger terms only spark a further sell-off in MCT? And, wouldn't that make it even harder to convince already sceptical MCT unitholders to vote for the deal?
Bullish on MNACT
Quarz does not accept that MCT's market price sank because of the proposed merger alone.
Quarz said last week that rising interest rates have weighed heavily on the market value of several Singapore-listed Reits that were trading at compressed DPU yields - including Mapletree Logistics Trust, Mapletree Industrial Trust, Parkway Life Reit and Keppel DC Reit.
Quarz also suggested the market might be realising MCT has relatively limited growth potential, and its units were simply overvalued compared with those of its peers.
Before the merger was unveiled, MCT was trading at an annualised H1 FY2022 DPU yield of 4.4 per cent and a 16.3 per cent premium to its NAV as at Sep 30, 2021.
On the other hand, MNACT was trading at an annualised H1 FY2022 DPU yield of 6.2 per cent and a 12.3 per cent discount to NAV as at Sep 30, 2021.
MCT's superior market valuations compared to MNACT seemed justified. For one thing, MCT had delivered higher annualised growth in its DPU and NAV per share than MNACT since their respective initial public offerings.
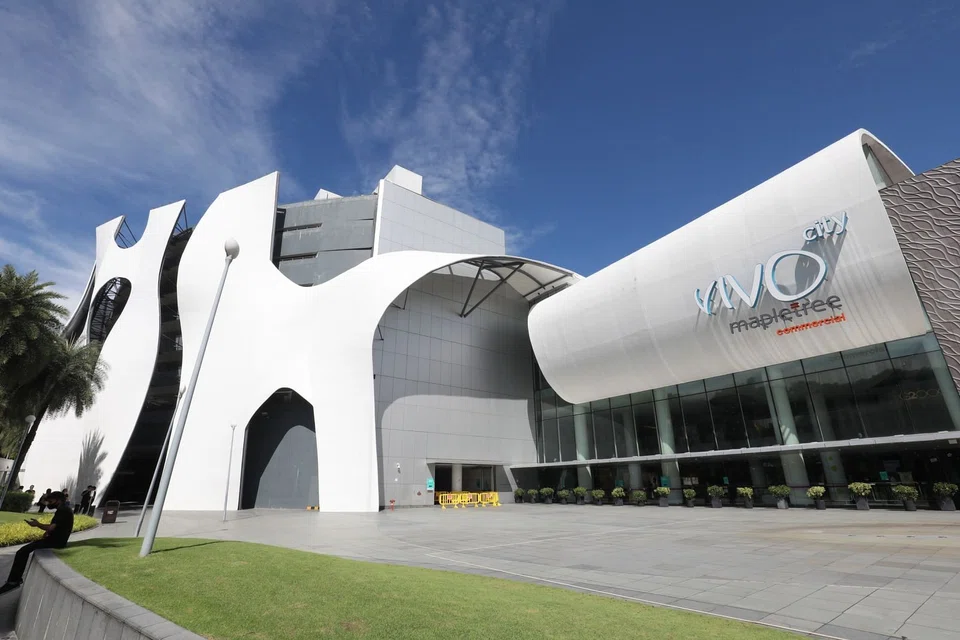
MCT also achieved a positive 2.3 per cent portfolio rental reversion in H1 FY2022. Its office and business park assets saw a 1.5 per cent reversion. Its retail properties - including its flagship asset, VivoCity - benefited from a 3.5 per cent rental reversion.
By contrast, MNACT still seems to be reeling from the impact of Hong Kong riots in 2019 and the pandemic that began in 2020. In particular, the shopping mall at Festival Walk suffered rental reversions of negative 30 per cent in H1 FY2022.
Quarz insists things are looking up for Festival Walk though. The asset manager is betting the Covid-19 pandemic will continue waning, and the Hong Kong-China border will soon reopen.
The way Quarz sees it, MCT is acting opportunistically by proposing a merger with MNACT now. "We are confident and bullish that MNACT's NAV, DPU and unit price will stage a strong recovery from H2 2022," Quarz said in its letter of Feb 9.
Sufficient support?
The big question is whether Quarz will be able to garner sufficient support from fellow MNACT unitholders to block the merger.
So far, Quarz has only been willing to say that it is among the top 10 unitholders of MNACT.
MNACT's last annual report shows that its sponsor group Mapletree Investments had a deemed interest in 37.6 per cent of its units as at May 28 2021.
The merger is to be effected by a scheme of arrangement. Amendments to MNACT's trust deed to facilitate the scheme require 75 per cent support of all units voting at an extraordinary general meeting.
The scheme itself needs the support of the majority of unitholders holding 75 per cent of the units voting at the scheme meeting. Mapletree Investments will abstain from voting at the scheme meeting.
Neither the manager of MCT nor the manager of MNACT seem too concerned about Quarz's campaign though.
MNACT's manager said last week that it "appreciates the perspectives and feedback of unitholders, and notes that Quarz regards positively the strategic rationale of the proposed merger".
MCT's manager hinted that Quarz might be helping it dispel the notion that acquiring MNACT would be detrimental for MCT's unitholders. "We note that Quarz acknowledges the deal rationale, as stated in the joint announcement made on Dec 31, 2021, and sees value in MNACT."
It would be ironic if Quarz's campaign ultimately does more to persuade MCT unitholders to support the merger than it does to convince MNACT unitholders to vote against the deal.
- The writer owns units in Mapletree North Asia Commercial Trust.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

